
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Benchmark Electronics (BHE) Stock May Look Pricey Given Its Earnings Premium
Benchmark Electronics has delivered a powerful share price run in recent years, which now puts a sharper spotlight on whether that performance is backed up by its earnings power. With the stock recently closing at US$72.63, the key issue is how much of the past enthusiasm is already embedded in the current valuation.
- Over the past 3 years the share price has gained 218.6%, which raises the question of how closely that rise lines up with the underlying earnings profile.
- The business model, which relies on manufacturing execution, cost discipline and the ability to convert revenue into consistent profits, can have a direct influence on how durable its earnings base appears to investors.
- The analysts covering Benchmark Electronics have run their own numbers. See what analysts think Benchmark Electronics's shares could be worth.
The stock's next move may depend on whether Benchmark Electronics' current price can be explained by its earnings when set against the Fair Ratio benchmark.
If you want to stress test this same earnings question beyond Benchmark Electronics, you can compare it with 34 high quality undervalued stocks.
Is Benchmark Electronics Getting Expensive on Earnings?
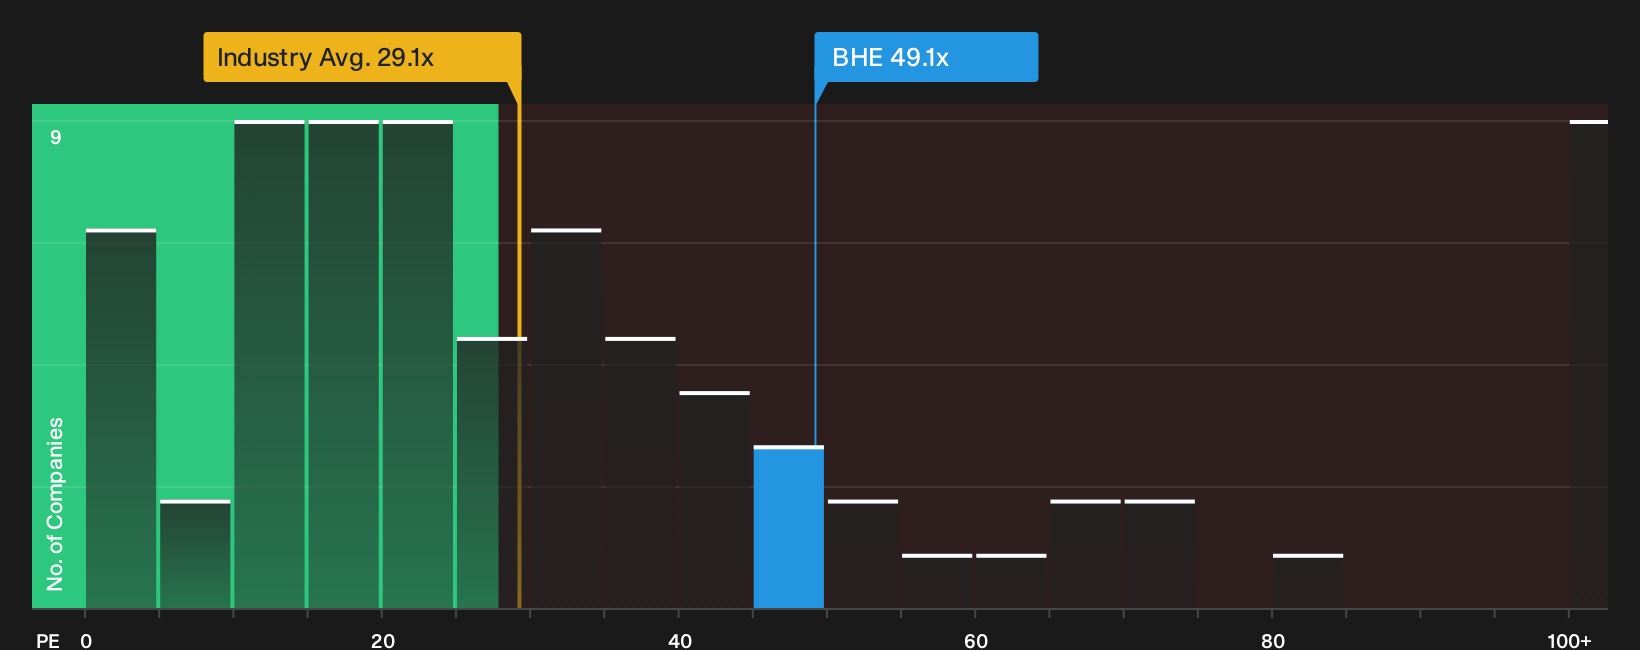
The P/E ratio tends to suit a manufacturer like Benchmark Electronics because earnings are a central yardstick for how efficiently it turns contracts into profit. At the recent share price, Benchmark Electronics trades on a P/E of about 49.1x, compared with an industry average near 29.1x. That is also slightly above the peer group, which clusters around 48.5x, so the equity is not priced as a clear outlier against close comparables, but it is well above the wider sector backdrop.
The Fair Ratio framework, which weighs factors such as profitability profile, sector, size and risk, points to a lower P/E than where the stock trades today. This gap suggests the market is placing a richer earnings tag on Benchmark Electronics than that model implies, and investors would need to judge whether the business quality and future earnings potential justify paying that kind of premium. Explore the numbers behind Benchmark Electronics's P/E valuation.
The Benchmark Electronics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Benchmark Electronics valuation puzzle leaves off by spelling out which combinations of future growth, margins and earnings would need to hold for the stock to be worth materially more or materially less than it is today, and they sit on the Community page so you can see different viewpoints laid out side by side. Rather than a single multiple or model output, each one surfaces the assumptions behind its fair value so you can compare those expectations with reported results over time.
One of the top community narratives on Benchmark Electronics: 16% undervalued
"Benchmark is positioned to benefit from the surging demand for advanced computing and AI infrastructure, as evidenced by recent contract wins…"
Discover why this Narrative puts Benchmark Electronics at 16% undervalued.
One more Benchmark Electronics question that could matter
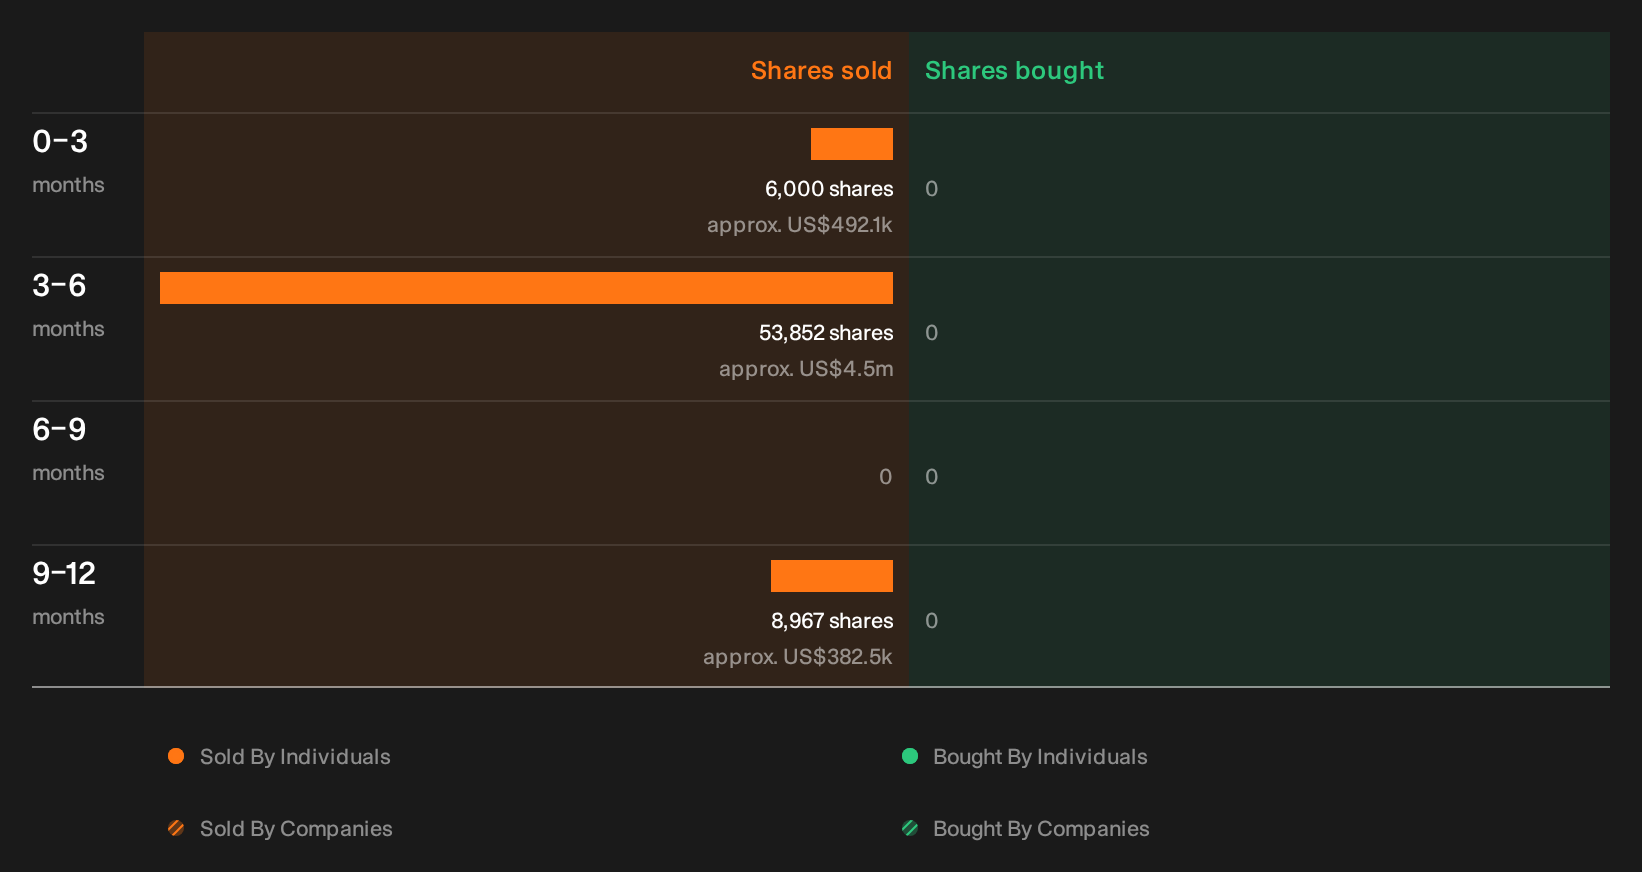
Before closing the file on Benchmark Electronics, it is worth checking one more signal that our checks have flagged, which involves recent share dealings by people on the inside of the business. See the recent insider selling flagged for Benchmark Electronics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com