
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Entegris (ENTG) Expensive Following Its Recent Pullback And Flat Sales?
Entegris (ENTG) sits in an awkward spot. The business supplies materials that keep advanced semiconductor production clean, yet sales have been broadly flat for two years and free cash flow has stayed tight.
Recent trading shows that enthusiasm around Entegris has cooled in the short term, with the share price down 19.9% over 30 days and 17.6% over 90 days. However, the year-to-date share price return is 44.8% and the 1-year total shareholder return is 40.5%, which points to longer-term holders still being comfortably ahead despite the pullback.
Scan beyond Entegris and compare it with a curated 60 AI infrastructure stocks that could also be exposed to semiconductor manufacturing demand shifts.
So with Entegris shares giving back a chunk of recent gains while sales and cash generation tread water, does the current valuation still compensate you for the bumpier ride ahead?
Most Popular Narrative: 25% Undervalued
On the most followed narrative, Entegris screens as undervalued, with a fair value of $173.36 against a last close of $129.64, which concentrates attention on what could shift earnings and cash generation from here.
Investments and leadership in advanced materials for next-generation nodes, including CMP slurries, selective etch, and deposition materials, position Entegris to capitalize on upcoming node transitions (e.g., advanced logic, 3D NAND, HBM) and increasing semiconductor complexity, supporting higher ASPs and improved gross margins.
See why 13 investors see Entegris as 25% undervalued.
Result: Fair Value of $173.36 (UNDERVALUED)
Still, Entegris carries some clear pressure points, including elevated gross leverage near US$4b and heavy exposure to Asia, where trade policy shifts can disrupt demand.
Find out about the key risks to this Entegris narrative.
Another View: What Entegris’ Current Multiple Is Telling You
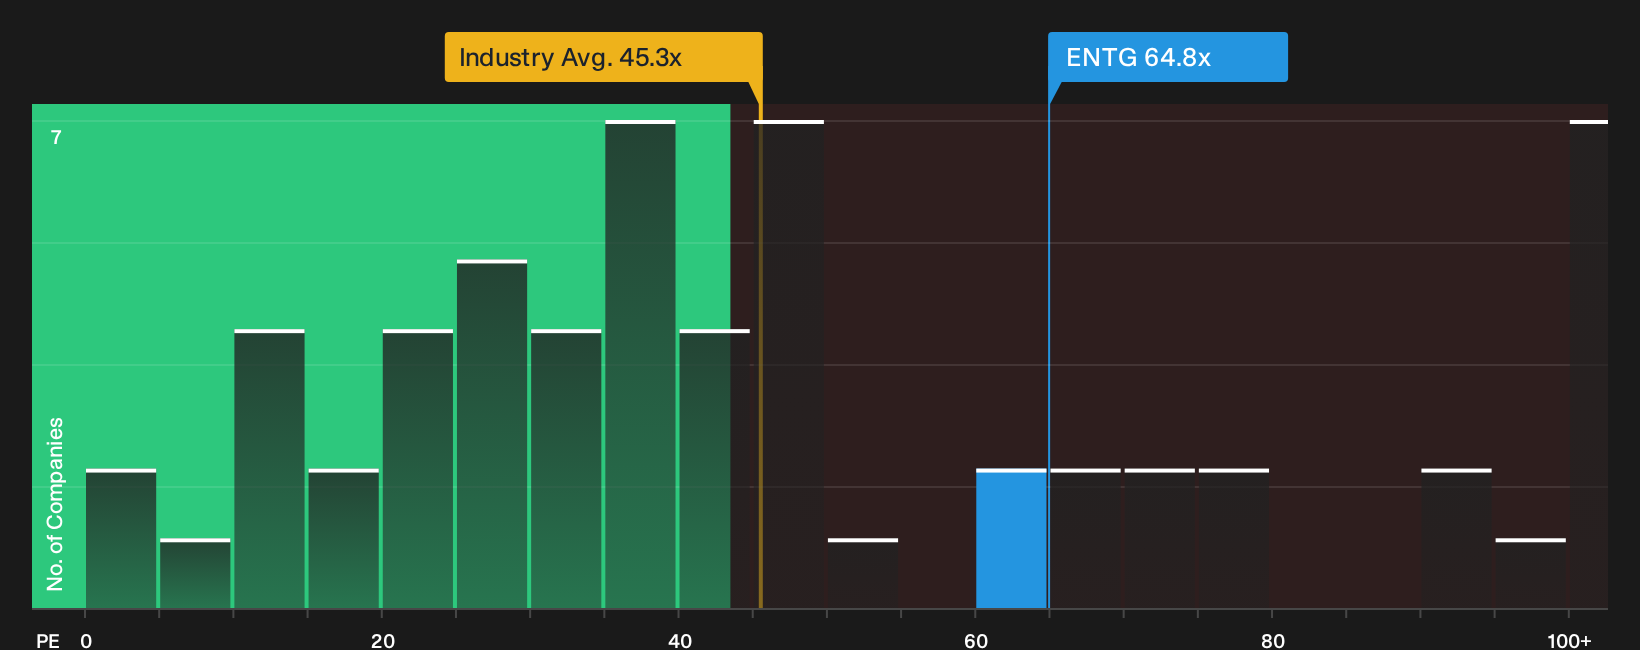
Step away from fair value models for a moment and look at what the market is already paying for Entegris. The stock trades on a P/E of 64.8x, which is richer than both its peer group at 46.9x and an estimated fair ratio of 33.8x.
That gap suggests investors are already baking in a lot of good news, so any disappointment on earnings or cash generation could hurt more than it helps. The question is whether you think Entegris has enough earnings power to grow into that valuation or if the starting point simply leaves too little room for error.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Unsure whether Entegris’ risk and reward signals balance out in your favour today? Take a closer look at the full picture with 2 key rewards and 2 important warning signs.
Looking for more Entegris-like investment ideas?
Do not stop your research with Entegris. Broaden your watchlist with fresh ideas from the Simply Wall Street screener so you are not relying on a single opportunity.
- Target stronger upside potential by scanning a curated 16 high quality undiscovered gems that pairs robust fundamentals with companies the wider market may not be watching yet.
- Prioritise resilience by reviewing a 11 resilient stocks with low risk scores focused on businesses with steadier risk profiles that might better suit a smoother ride through volatility.
- Strengthen your core holdings by checking a list of solid balance sheet and fundamentals (22 results) that filters for companies with sturdier financial foundations and healthier fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com