
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Vulcan Materials (VMC) Stock Trades Above Fair Value After Legal Win
Vulcan Materials has seen its share price fall back in recent months, yet over a 5 year stretch the stock is still meaningfully higher. This puts the focus squarely on whether the current valuation is supported by the cash the business can generate. With investors digesting a fresh legal win in Mexico and a softer near term share performance, the question now is how the market price lines up against the cash flow profile implied by a Discounted Cash Flow (DCF) view.
- Over the past 5 years Vulcan Materials has delivered a total return of about 51.2%, so a lot of long term value creation is already embedded in the share price and needs to be weighed against the cash it can produce.
- The recent arbitration ruling in favor of Vulcan Materials over its Quintana Roo quarry dispute may support expectations around future cash generation if it improves clarity on access to assets and any potential recoveries.
- What if you looked at Vulcan Materials through its earnings instead? See what Vulcan Materials's 28.9x P/E says about the price.
The issue now is whether Vulcan Materials' current share price can be fully explained by the cash flows implied by a Discounted Cash Flow (DCF) intrinsic value estimate.
Vulcan Materials is one way to think about whether today's price is justified by its cash flows, but it can help to compare that theme against 34 high quality undervalued stocks
Is Vulcan Materials Getting Expensive on Cash Flow?
The Discounted Cash Flow (DCF) approach here looks at what Vulcan Materials might return to shareholders through future free cash flows. Latest twelve month free cash flow sits at about $1.0b, and the model assumes those cash flows continue to grow from that base rather than shrink or spike sharply, which fits a more mature infrastructure supplier.
Projections for Vulcan Materials reach into the 2030s and point to gradually higher annual free cash flow in dollars. Yet the DCF outcome still comes in modestly below the current share price of $249.20. The recent international arbitration win in Mexico helps clear a major question around the Quintana Roo quarry, but the model still suggests the market is already pricing in a fair amount of future cash generation at today's level. Find out what Vulcan Materials could be worth using our Discounted Cash Flow (DCF) estimate.
The Vulcan Materials Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Vulcan Materials pick up where the DCF puzzle leaves off and explain what would need to happen to growth, margins and earnings for the stock to be worth materially more or less than it is today. Rather than relying on a single model output, each narrative outlines the specific assumptions behind its view of Vulcan Materials' value, so you can compare those expectations with the financial results as they are reported on the Community page.
One of the top community narratives on Vulcan Materials: roughly fairly valued
"The relatively low difference between the current share price and the analyst consensus price target indicates that they believe on average, the company is fairly priced..."
Discover why this Narrative puts Vulcan Materials at roughly fairly valued.
One more Vulcan Materials signal that could change how you see the story
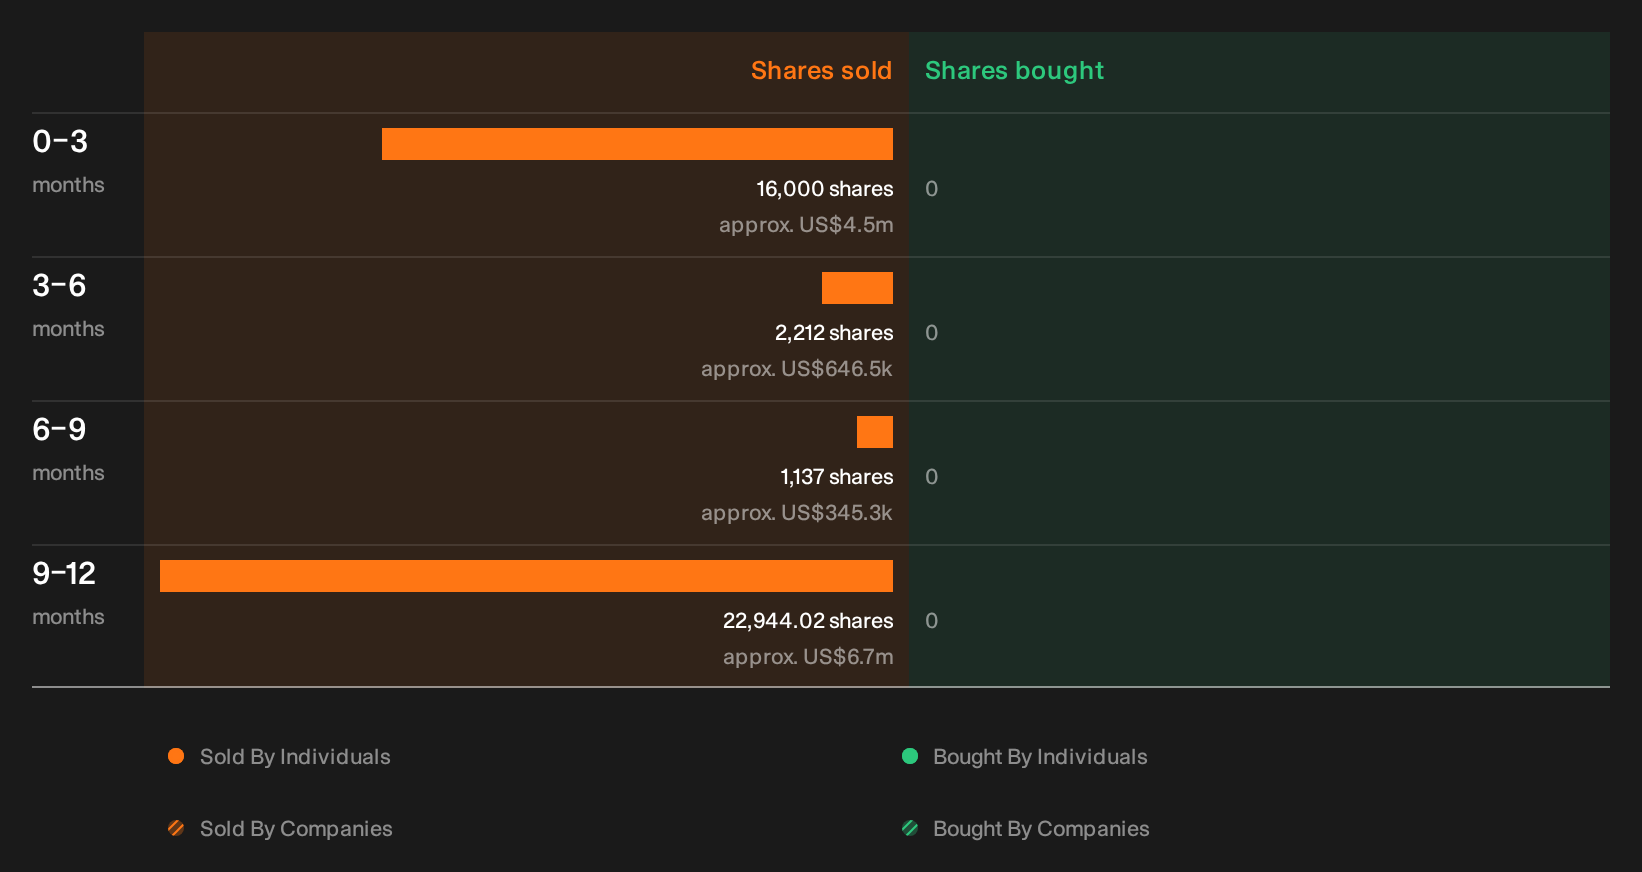
There is a final thread to pull on with Vulcan Materials, as recent transactions by people inside the business have been flagged and the identities, sizes and possible takeaways are still for you to unpack. See the recent insider selling flagged for Vulcan Materials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com