
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
IPG Photonics (IPGP) Stock Looks Overvalued As AI Demand Optimism Builds
IPG Photonics has seen its share price under pressure in recent years, even as new excitement around artificial intelligence related hardware has crept into the story. That gap between a choppy share track and changing sentiment now raises a direct question for investors who care about earnings driven valuation.
- Over the past 5 years the stock has fallen 53.2%, which puts the focus squarely on whether today's valuation still lines up with the business IPG Photonics has built.
- Recent optimism tied to projected AI infrastructure spending and improving macro signals can shape expectations for how efficiently the company may convert demand into future earnings power.
- There is a second opinion on IPG Photonics worth weighing. See what analysts think IPG Photonics's shares could be worth.
The issue now is whether the current US$75.14 share price is justified by IPG Photonics' earnings when set against the Fair Ratio benchmark.
To test whether IPG Photonics' earnings based valuation question is unique or part of a wider pattern in AI hardware, compare it directly with 60 AI infrastructure stocks.
Has IPG Photonics Run Too Far on Earnings?
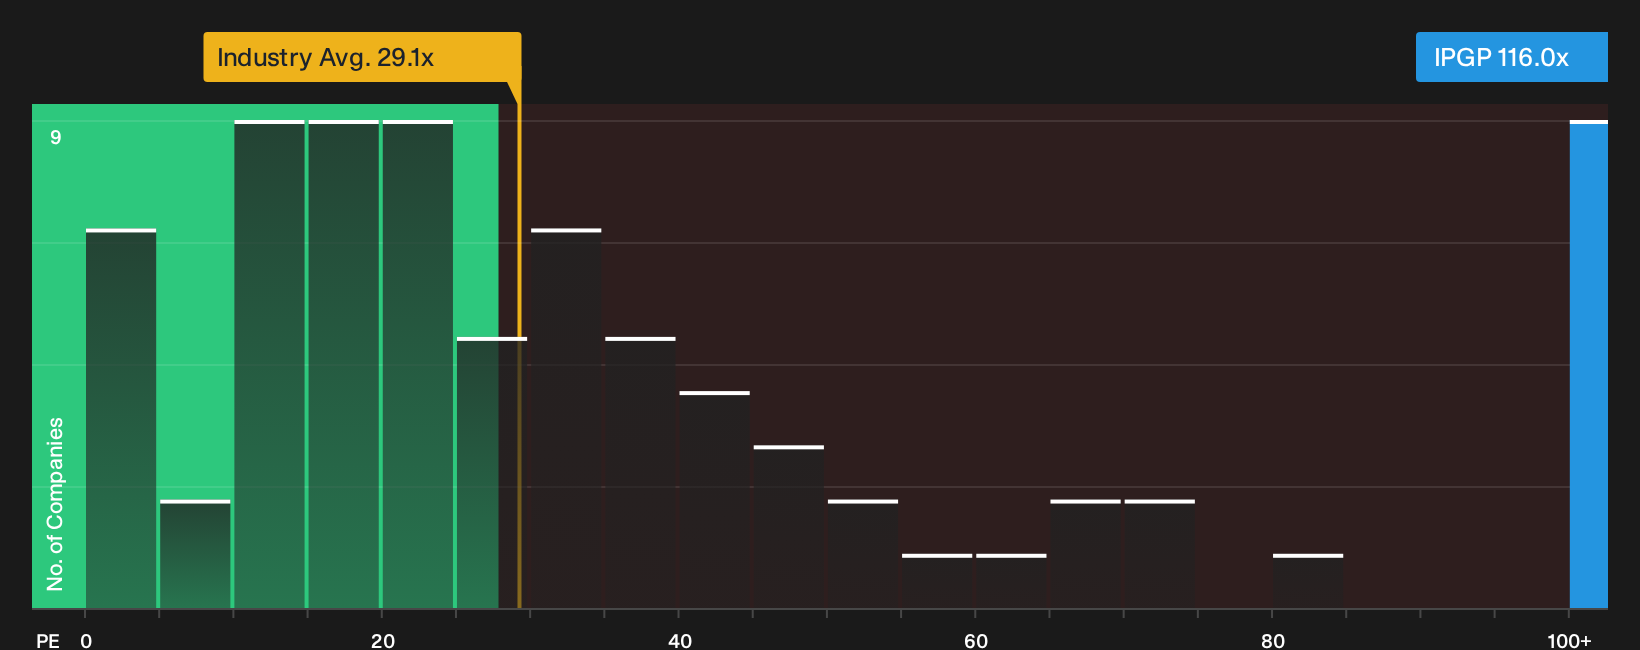
The P/E ratio fits IPG Photonics because investors are clearly focused on what each dollar of earnings might be worth as AI related demand builds into the story. On this lens, the stock trades on about 116.0x earnings, which is much higher than the Electronic industry average of roughly 29.1x and also above the peer group on about 35.0x. The Fair Ratio, which reflects what a more tailored multiple might look like after factoring in growth prospects, margins, size and risk, sits below the current level, so the shares screen as overvalued on this framework.
Recent enthusiasm around large AI infrastructure forecasts has helped sentiment toward IPG Photonics, yet the current P/E already prices the business at a premium to both sector and peer benchmarks. That leaves investors paying up heavily for each dollar of earnings today relative to similar hardware stocks, which raises the bar for how the story needs to develop from here. Explore the numbers behind IPG Photonics's P/E valuation.
The IPG Photonics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle for IPG Photonics leaves off by spelling out which concrete assumptions about future growth, profitability and earnings would need to play out for the stock to be worth meaningfully more or less than it is today. Each scenario ties its number to a clear view on how IPG Photonics' growth, margins and risk profile might shift over time, which you can return to on the Community page as fresh information emerges.
One of the top community narratives on IPG Photonics: 51% undervalued
"Bullish analysts point to the agreed US$348.8M acquisition of Lumibird Medical as aligned with IPG Photonics' existing approach to medical applications…"
Discover why this Narrative puts IPG Photonics at 51% undervalued.
One more IPG Photonics check that belongs next to the price tag
Numbers tell only part of the IPG Photonics story, because the people deciding where to invest cash, how much risk to take and how they are rewarded for it can tilt long term outcomes in ways the P/E ratio never shows. See who runs IPG Photonics and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com