
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Quantum Computing (QUBT) Stock May Be Below Fair Value As Qatar Partnership Starts
Quantum Computing has delivered a very large 3 year share price gain, yet recent weakness now puts the focus squarely on whether the current US$7.84 price still lines up with the company’s book value. For anyone following Quantum Computing stock today, the issue is less about headline moves and more about what the balance sheet says about that valuation.
- Over the past 3 years, the share price has climbed by roughly 7x. This raises the question of how much of that strength is supported by the underlying net assets.
- The new three year collaboration with Hamad Bin Khalifa University in Qatar may support future adoption of Quantum Computing’s technology. This could influence how investors weigh the firm’s asset base against its potential to generate returns on that capital.
- There is a second opinion on Quantum Computing worth weighing. See what analysts think Quantum Computing's shares could be worth.
The stock’s next move may depend on whether Quantum Computing’s current market value can be squared with what its book value suggests the business is worth.
If you want to stress test this same book value question beyond Quantum Computing, scan a wider set of companies using 34 high quality undervalued stocks.
Does Quantum Computing Look Undervalued on Book Value?
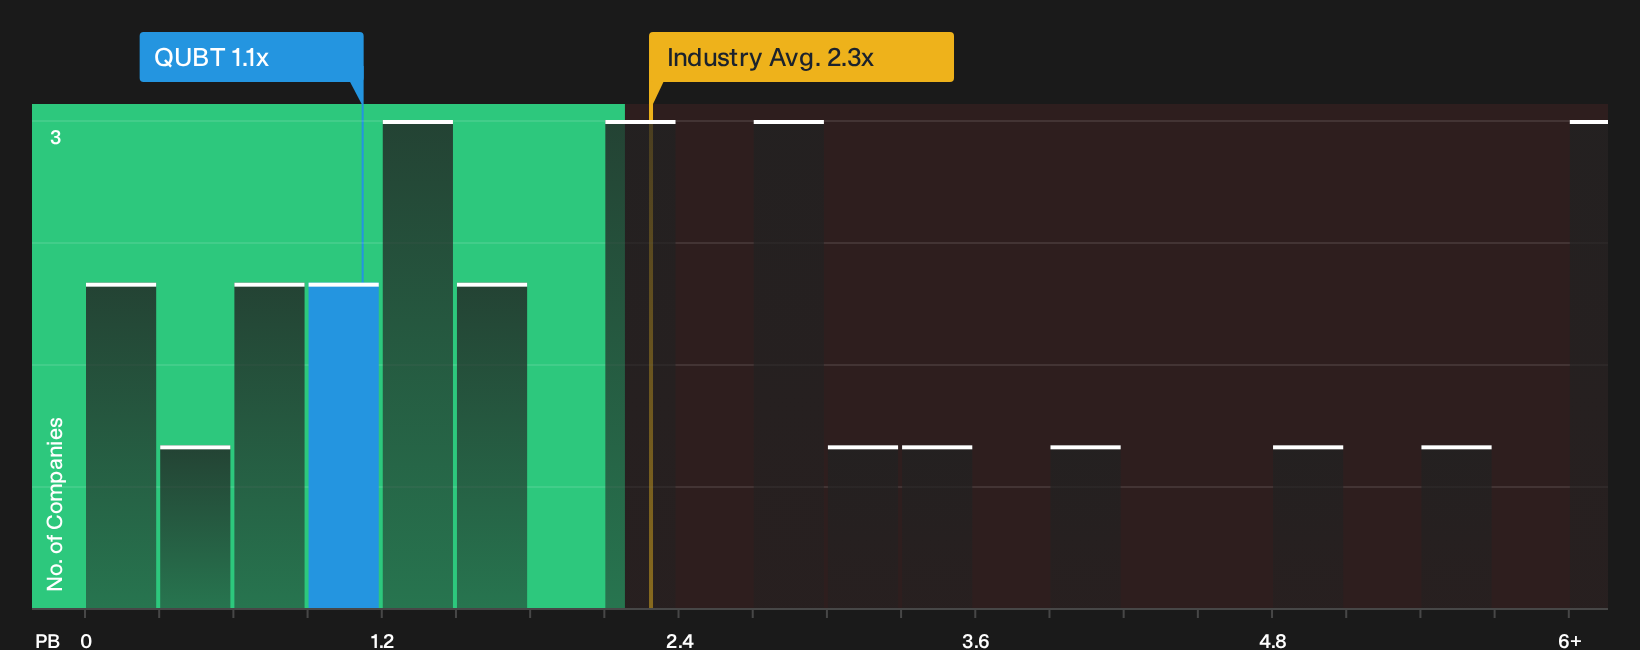
P/B is a useful lens for Quantum Computing because the business is still focused on building out its asset base rather than producing steady profits. On this yardstick, the stock trades on a P/B of about 1.1x, which is below both the wider Tech sector average of roughly 2.3x and the peer group near 2.5x. That gap suggests the market is valuing each dollar of Quantum Computing’s net assets at a discount to many listed technology companies.
Because the new Qatar collaboration gives the firm a clear asset backed route into research and deployments, the modest 1.1x P/B multiple implies investors are not paying a high premium for that platform compared with the sector. For you as a shareholder or potential buyer, the key question is whether the current balance sheet and future use of that capital justify a valuation more in line with the industry or continue to trade at a discount. Explore the numbers behind Quantum Computing's P/B valuation.
The Quantum Computing Narrative: What Would Justify Today's Price?
Quantum Computing’s valuation puzzle sets up the role of Simply Wall St Narratives, which sit on the Community page and spell out the future growth, margin and earnings paths that would need to hold for the stock to be worth materially more or less than today’s market price. Each scenario ties its numbers to a clear view on where revenue expansion, profitability and key risks might head next, giving you a reference point to revisit as fresh information comes through.
One of the top community narratives on Quantum Computing: 57% undervalued
"Quantum Computing Inc. completed a US$73.1m cash and stock acquisition of NHanced Semiconductors, with potential earnout payments tied to revenue and EBITDA milestones..."
Discover why this Narrative puts Quantum Computing at 57% undervalued.
One more Quantum Computing angle worth checking next
There is a separate lens on Quantum Computing that comes from where professional analysts think revenue, margins and cash generation might sit a few years from now, giving you another benchmark to compare with today's price. Explore where analysts expect Quantum Computing to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com