
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Can Paycom Software (PAYC) Sustain An Earnings Premium After Q2?
Paycom Software has delivered a sharp long term setback for holders, with the stock down 52.7% over 5 years. That puts fresh focus on whether the current share price is now aligned with what its earnings can support. With the business back in the spotlight after recent updates, the key issue is how that profit stream compares with where the stock trades today.
- A 52.7% share price decline over 5 years raises the question of whether Paycom Software's earnings profile has kept pace with how far sentiment has shifted.
- Recent revenue outperformance and higher profit expectations may support a case that the earnings base is evolving in a way that could affect how investors think about what they are paying for each dollar of profit.
- Your read on Paycom Software is one view; the desks covering it have another. See what analysts think Paycom Software's shares could be worth.
The stock's next move may depend on whether Paycom Software's current earnings are strong and durable enough to justify the market value placed on it today.
If you are weighing whether Paycom Software's earnings justify its current P/E, it can help to compare it with other companies using the same lens through the 34 high quality undervalued stocks
Where Does Paycom Software Sit on Earnings?
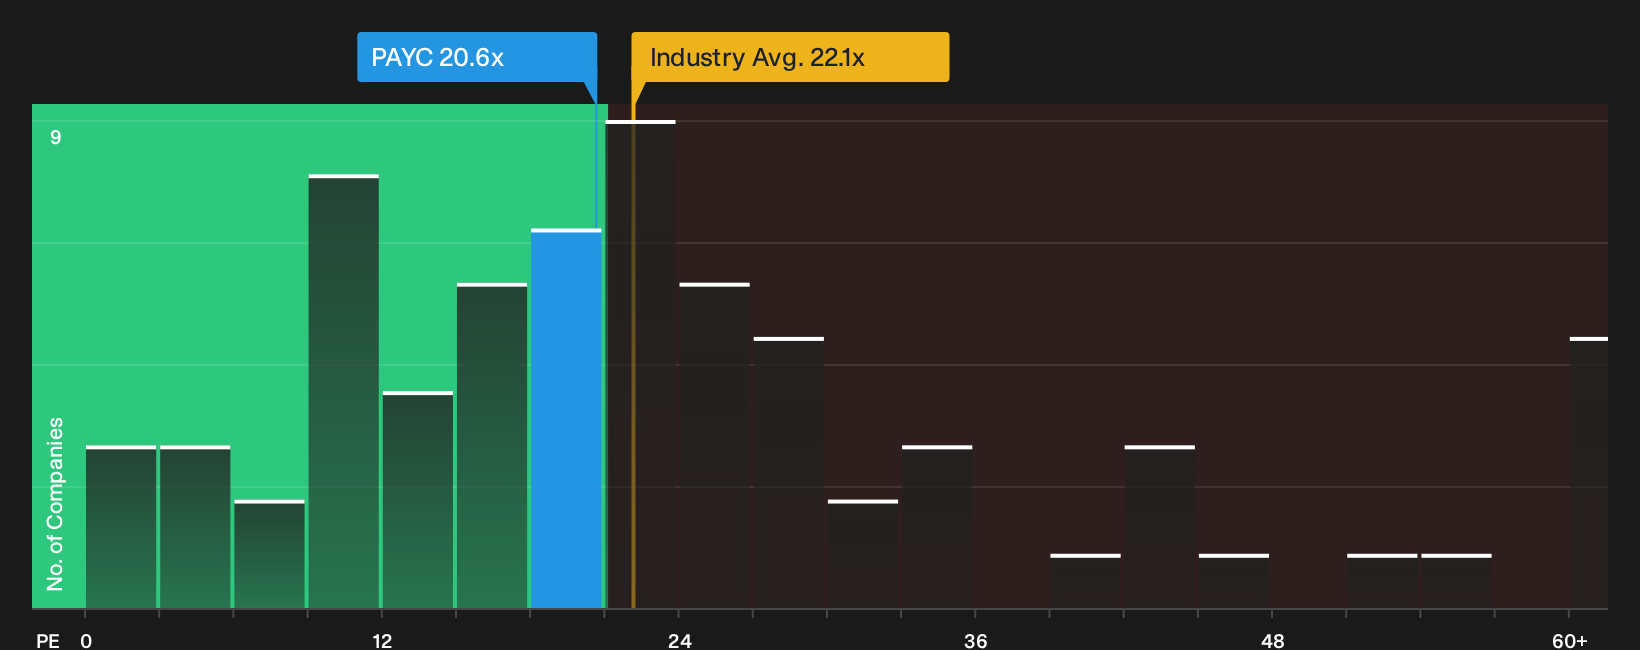
The P/E ratio is a useful lens for Paycom Software because earnings sit at the center of how investors usually value this type of software platform. Paycom Software trades on a P/E of 20.6x, which is slightly below the Professional Services industry average of 22.1x and just under the peer group at 21.9x.
Recent Q2 revenue of $531.2 million and the guidance lift on EBITDA have put fresh attention on how much you are paying for each dollar of profit, because those results helped the firm outperform HR software peers on analyst expectations. The current multiple sits close to the level suggested by a tailored fair ratio that already bakes in factors such as margins, risk profile and market size, so the market is not applying a clear premium or discount on this earnings base. Because the recent earnings beat has come without a large gap opening up versus these benchmarks, the P/E points to a valuation that hinges on how durable investors think this profitability and guidance will be over time. Explore the numbers behind Paycom Software's P/E valuation.
The Paycom Software Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Paycom Software pick up where the P/E puzzle leaves off by spelling out which growth paths, profitability levels and earnings patterns would need to play out for the stock to look meaningfully cheaper or more expensive than it does today. Each narrative links its number to a clear view on how Paycom Software's expansion, margins and risk profile might evolve, giving you a reference point you can return to when new results or guidance arrive on the Community page.
Community views on Paycom Software split between one group that sees meaningful upside driven by AI and efficiency gains, and another that thinks expectations already look full.
Bull case: 16% undervalued
"Broad rollout of IWant across the entire client base, with millions of employee, manager and C suite queries already flowing through the system, positions Paycom to deepen product usage and support recurring revenue…"
Discover why this Narrative puts Paycom Software at 16% undervalued.
Bear case: 50% overvalued
"Accelerating adoption of AI-driven HR automation across the industry could commoditize voice-enabled and command-driven interfaces like IWant, eroding Paycom's competitive differentiation and placing downward pressure on pricing and net margins…"
Explore why this Narrative puts Paycom Software at 50% overvalued.
One more piece of the Paycom Software puzzle before you decide
You have a view on what Paycom Software looks like today, but the projections that research analysts build for the next few years offer a separate lens on what you might be paying for. Explore where analysts expect Paycom Software to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com