
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Etsy (ETSY) Stock Looks About Right Despite Its 66% Five Year Fall
Etsy has delivered a mix of recovery and disappointment for shareholders, with the share price at about US$74 after a long stretch of uneven returns. With that backdrop, the live question is whether the current market value makes sense once you line it up against the earnings the business is actually producing.
- The stock has fallen 66.5% over the past 5 years, which puts the focus squarely on whether the earnings outlook can support today’s price after such a long reset.
- The marketplace model still relies heavily on turning gross merchandise volume into profitable net income, so any shift in take rates, cost discipline or marketing efficiency can feed directly into how much earnings investors are effectively paying for.
- Your read on Etsy is one view; the desks covering it have another. See what analysts think Etsy's shares could be worth.
The stock’s next move may depend on whether Etsy’s current earnings justify the valuation investors are being asked to accept today.
If you are questioning whether Etsy’s 5 year share price reset lines up with its earnings, it can help to compare that same valuation lens across 34 high quality undervalued stocks
Where Does Etsy Sit on Earnings?
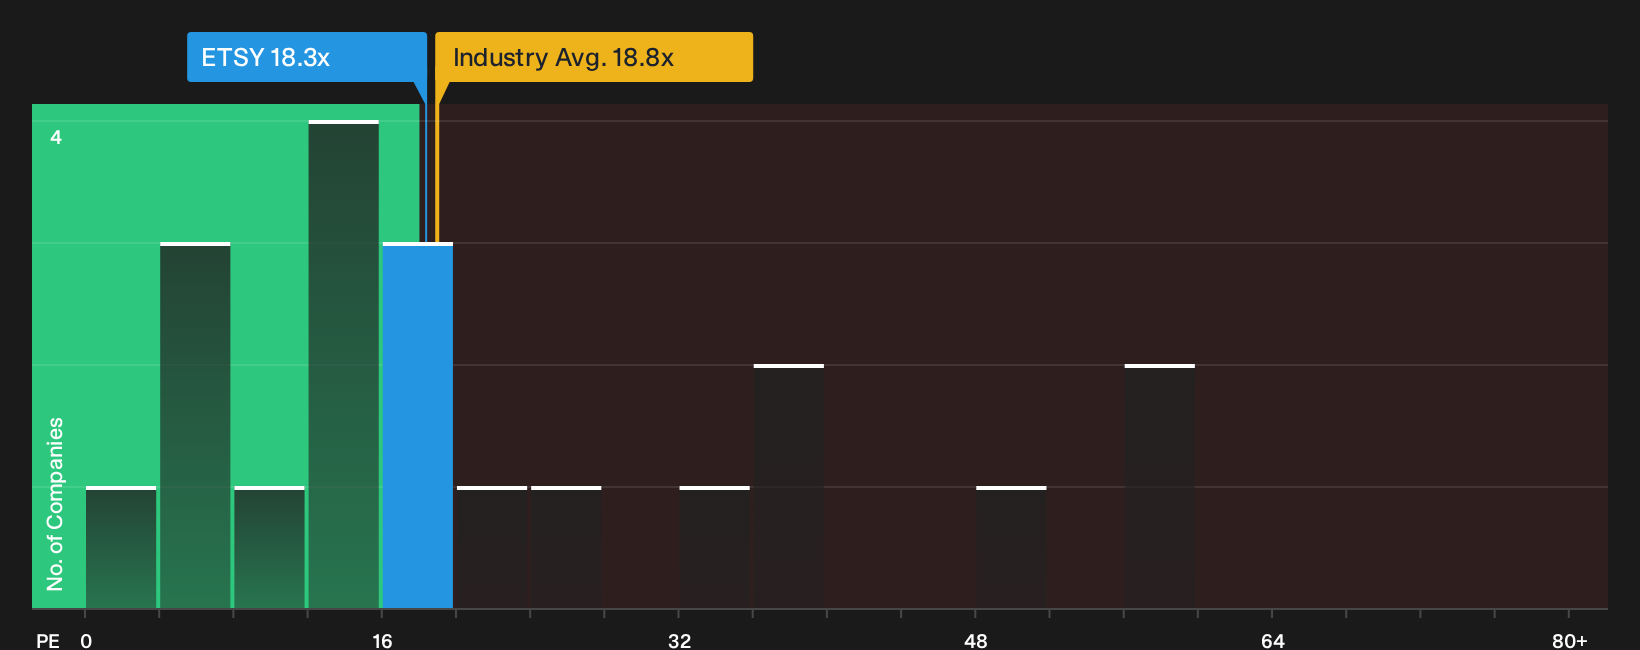
P/E suits Etsy because earnings are the anchor for what buyers are really paying for each dollar of profit. On that lens, the stock trades on a P/E of 18.3x, which is slightly above the peer group average of 16.7x and a touch below the broader multiline retail industry on 18.8x. That puts Etsy in a band where the market is neither treating it as a clear bargain nor as an obvious outlier on price alone.
The Fair Ratio, which adjusts for Etsy’s own mix of growth profile, margins, size and risk, lands close to the current P/E. So the multiple sits near the level you might expect for this business rather than flashing a strong discount or premium relative to its fundamentals. For an investor, the real question becomes whether Etsy’s marketplace economics and competitive position justify paying roughly this kind of earnings tag or whether a different multiple would feel more comfortable. Explore the numbers behind Etsy's P/E valuation.
The Etsy Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where the P/E puzzle leaves off by spelling out which future paths for Etsy's growth, margins and earnings would need to play out for the current share price to look materially higher or lower. Each scenario ties its valuation anchor to a specific view on how Etsy's profitability profile and risk mix could shift, giving you a concrete reference point you can revisit as fresh information comes through.
Community views on Etsy split between a measured recovery story and a tighter, more cautious read on the risks around its marketplace model.
Bull case: 15% undervalued
"Etsy's increasing investment in AI-driven personalization and recommendations, leveraging large language models to understand buyer interests at a deeper level, is designed to materially boost conversion rates, buyer frequency, and lifetime value..."
Discover why this Narrative puts Etsy at 15% undervalued.
Bear case: 15% overvalued
"Etsy has periodically adjusted fees to fund marketing, platform improvements, and trust initiatives. While these moves strengthen infrastructure, they also test seller tolerance..."
Explore why this Narrative puts Etsy at 15% overvalued.
One more angle on Etsy that could change the story
Price tags and profit multiples only tell part of the story for Etsy, because the people setting priorities and how they are rewarded can tilt outcomes in ways the P/E alone never flags. See who runs Etsy and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com