
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Royalty Pharma (RPRX) Below Fair Value After The Pelacarsen Trial Miss?
Royalty Pharma (RPRX) is back in focus after Novartis reported that the Phase 3 HORIZON trial for pelacarsen missed its primary endpoint in patients with elevated lipoprotein(a).
Royalty Pharma’s share price has eased in the short term, with a 7 day share price return of 3.5% and a 30 day share price return close to flat. However, the 90 day share price return of 8.9% and year to date gain of 50.5% signal momentum that reflects investors weighing the pelacarsen setback against the long run royalty portfolio, supported by a 1 year total shareholder return of 68.3% and a 3 year total shareholder return of 130.2%.
Scan other cash flow focused royalty and healthcare licensors that share some of Royalty Pharma's defensive traits using our curated list of 11 resilient stocks with low risk scores.
Royalty Pharma’s recent pullback after the pelacarsen news sits against a much stronger multiyear run. Is the latest move about sentiment resetting or about what the business is actually worth?
Most Popular Narrative: 9.7% Undervalued
Royalty Pharma’s most followed narrative pegs fair value at $64.75 compared with the last close of $58.47. This frames the pelacarsen reaction against a model that still sees upside under its own assumptions and a discount rate of 7.24%.
The robust scientific pipeline, driven by advancements in biologics, gene therapies, and next-generation medicines like daraxonrasib, creates high-value assets that can enter into blockbuster status. Participation in these early, high-impact assets (as in the Revolution Medicines deal) positions Royalty Pharma for long-duration, high-growth royalty streams, directly benefitting long-term revenue and earnings.
See why 27 investors see Royalty Pharma as 10% undervalued.
Result: Fair Value of $64.75 (UNDERVALUED)
Still, the narrative around Royalty Pharma can shift quickly if the Alyftrek royalty dispute drags on or if competition in drug finance squeezes returns on new deals.
Find out about the key risks to this Royalty Pharma narrative.
Another View on Royalty Pharma’s Valuation
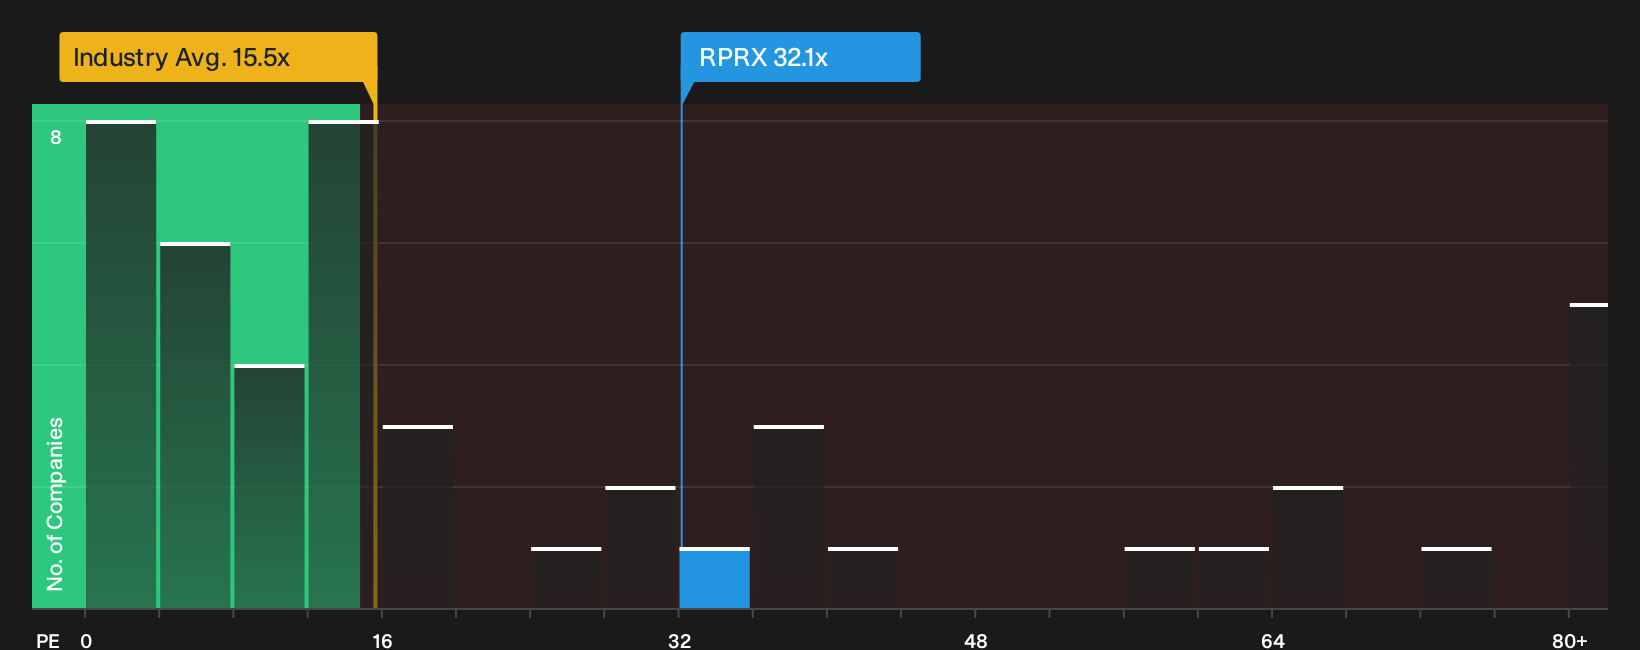
While the crowd narrative points to Royalty Pharma trading below a modeled fair value, the plain P/E math tells a different story. RPRX trades on a P/E of 32.1x versus 15.5x for the US Pharmaceuticals group and an estimated fair ratio of 25.4x. That is a rich premium. Is the royalty model solid enough to justify paying up?
For investors weighing this valuation gap, our earnings based approach raises questions about how much optimism is already in the price. This is where the detailed breakdown in our valuation work can help See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Royalty Pharma is clearly split, and that is where opportunity often hides for prepared investors. Weigh the full picture for yourself by checking both the concerns and the upside that others are focused on through 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Royalty Pharma?
If you stop with Royalty Pharma, you miss a wider set of opportunities. Use the Simply Wall St screener to pressure test your next move with data driven shortlists.
- Target potential mispricings by checking stocks on our 34 high quality undervalued stocks that combine solid fundamentals with room for a re rating.
- Strengthen portfolio resilience and reduce unpleasant surprises by scanning companies in the list of solid balance sheet and fundamentals (22 results).
- Spot early stage opportunities before the crowd by reviewing the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com