
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Ultra Clean Holdings (UCTT) Undervalued After Rising Outsourcing Demand Lifted Growth Expectations?
Fresh analysis around Ultra Clean Holdings (UCTT) is drawing attention to its role supplying outsourced subsystems to chip equipment makers, as investors weigh upbeat revenue and earnings expectations against recent share price volatility.
Ultra Clean Holdings has experienced sharp swings, with the share price falling 13.17% over the past week and 22.69% over the past month, yet still posting a 140.34% year to date share price return and a 151.47% 1 year total shareholder return. This points to strong momentum earlier in the year that has recently cooled as investors reassess growth expectations and risk around the current valuation.
Scan beyond Ultra Clean Holdings and compare this move with other specialists benefiting from outsourced semiconductor work using our curated list of 60 AI infrastructure stocks.
Ultra Clean Holdings now trades well below the average analyst target even after a strong run earlier this year. Is that a genuine discount, or a warning that the market doubts those optimistic forecasts?
Most Popular Narrative: 52% Undervalued
Analysts following Ultra Clean Holdings see a fair value of $137 per share, well above the last close of $65.66. This valuation places significant emphasis on multi year growth, margin recovery, and capital spending on wafer fab equipment.
A surge in AI-driven capital investment and strong expectations for new fab buildouts in 2026 support solid long-term demand for Ultra Clean's advanced process subsystems. This reinforces the company's exposure to the ongoing expansion of digital infrastructure and complex chip manufacturing (supports long-term revenue trajectory).
See why 20 investors see Ultra Clean Holdings as 52% undervalued.
Result: Fair Value of $137 (UNDERVALUED)
Still, the bullish Ultra Clean Holdings story leans on wafer fab demand and a small customer set, both of which could quickly pressure revenue and margins if conditions change.
Find out about the key risks to this Ultra Clean Holdings narrative.
Another View: DCF Model Flips The Script
The analyst narrative paints Ultra Clean Holdings as 52% undervalued, yet the Simply Wall St DCF model points the other way. On that framework, UCTT at $65.66 trades well above an estimated future cash flow value of $12.49, which frames the stock as expensive rather than cheap. That kind of gap forces a harder question: which set of assumptions do you trust more?
Look into how the SWS DCF model arrives at its fair value.
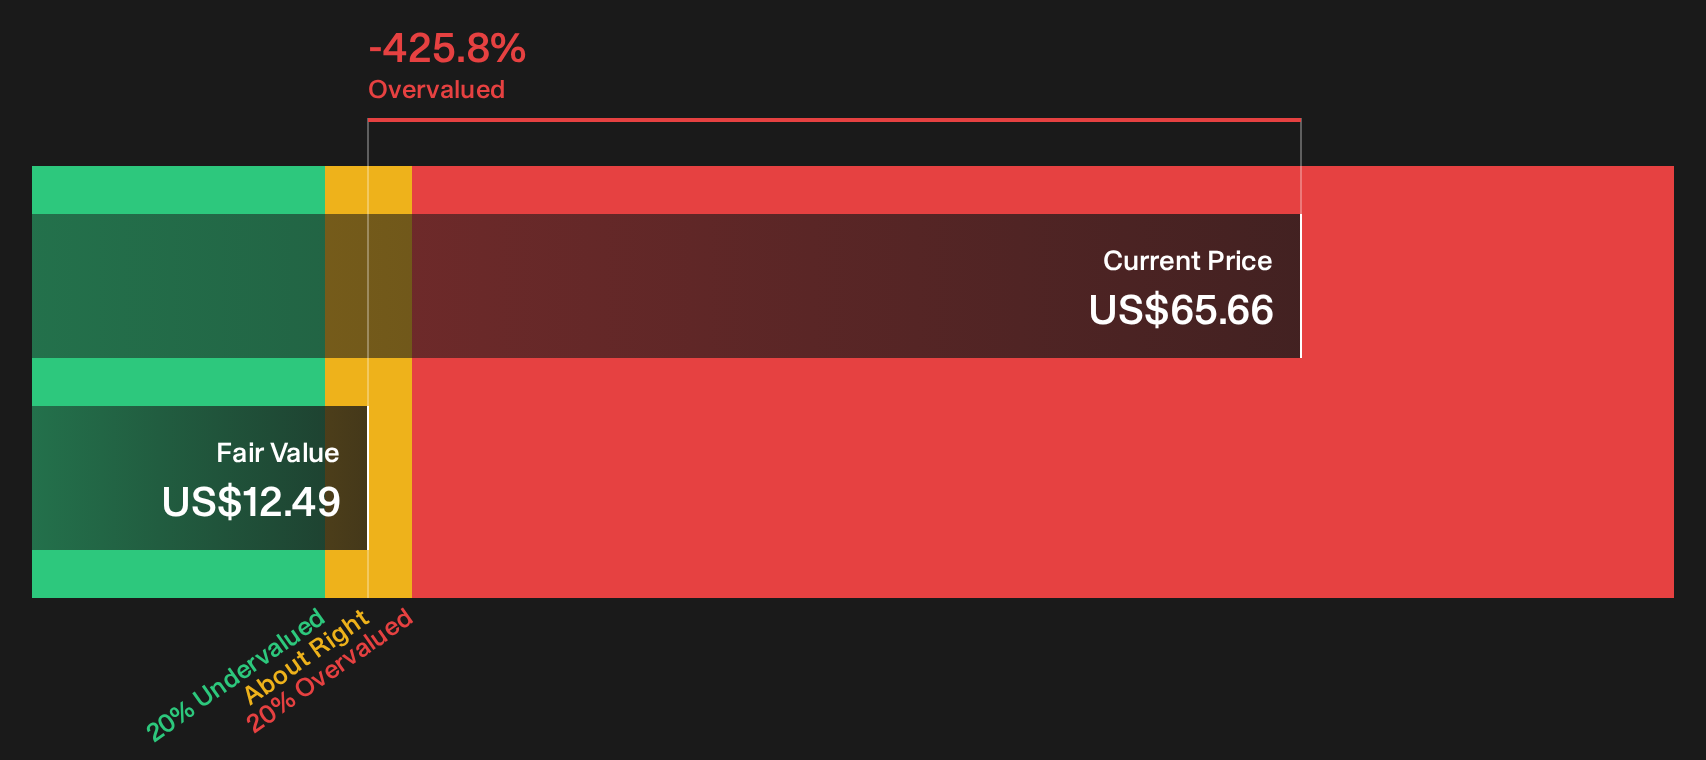
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ultra Clean Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals like this around Ultra Clean Holdings rarely stay unresolved for long. Weigh the upside case against the concerns and pressure test the data yourself with 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Ultra Clean Holdings?
If Ultra Clean Holdings has you thinking harder about opportunity and risk, widen your lens and pressure test fresh ideas with focused stock shortlists built from real fundamentals.
- Target companies that combine robust cash generation with appealing entry prices by scanning a curated set of 34 high quality undervalued stocks.
- Strengthen the defensive side of your portfolio by zeroing in on businesses highlighted in our list of solid balance sheet and fundamentals (22 results).
- Get ahead of the crowd by reviewing a curated pool of 16 high quality undiscovered gems while they are still under the radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com