
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Earnings Beat Require Action From Home Depot (HD) Investors?
- TP-Link Systems announced a partnership with Home Depot to sell four exclusive Tapo smart cameras in roughly 500 stores and online, with bundled hardware, storage, and app-based AI features included without extra subscriptions.
- The focus on AI-powered security, solar options, and simple, all-in-one bundles gives Home Depot another way to tie customers deeper into its ecosystem as smart-home demand evolves.
- Next, the focus shifts to how Home Depot's strong quarter and new AI-enabled smart home offering could influence the broader investment narrative.
Home Depot Investment Narrative Recap
To own Home Depot, you need to believe the business can keep turning a mature store base, heavy tech spend, and big Pro relationships into steady cash generation even as consumer demand feels uneven. The short term story still revolves around execution in core home improvement and managing gross margin amid higher fuel, freight, and input costs.
The TP-Link partnership fits that belief but does not change the main near term swing factors. It extends Home Depot’s reach in smart home, yet the bigger risk remains sluggish big-ticket remodeling and pressure on operating margin around 13% while inventory, capital spending, and debt all require tight control.
The most relevant recent development alongside the TP-Link news is Home Depot’s use of AI and automation across its supply chain and delivery network. Management has linked those tools to faster delivery and better productivity, which sit directly behind the appeal of in-store smart home offerings that promise easy setup, monitoring, and support.
Those technology investments are also central to the key catalysts and risks. Successful rollout of AI-driven logistics and Pro-focused services could help offset cost inflation and slower revenue growth. In contrast, missteps would leave earnings more exposed to soft renovation demand, elevated capital expenditure, and the company’s higher debt load.
Home Depot's narrative projects US$187.2b revenue and US$17.3b earnings by 2029. This is based on an assumption of 4.0% yearly revenue growth and an earnings increase of US$3.3b from US$14.0b today.
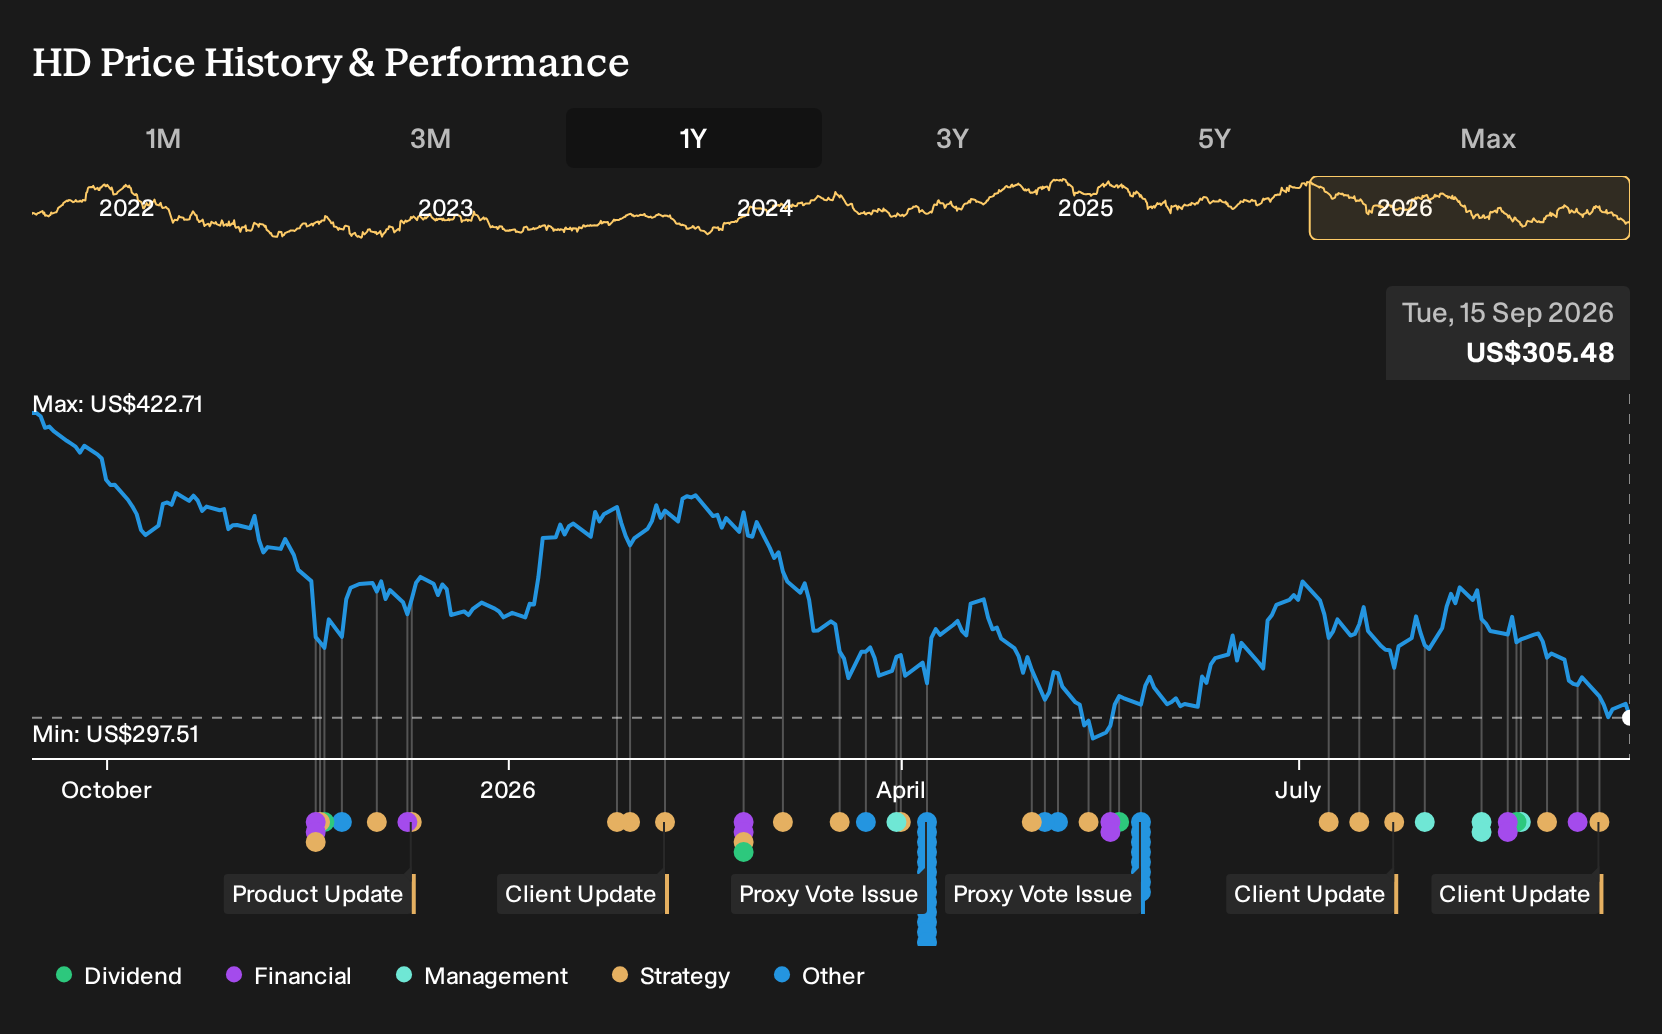
Uncover how Home Depot's fair value indicates a 21% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
The Simply Wall St Community currently contributes 2 fair value estimates for Home Depot, ranging from about US$275 to US$370. This spread shows how far apart private investors can be on the same stock. Set that against risks like slower big-ticket projects and heavy capital spending, then decide which scenario you think carries more weight.
Explore another Home Depot fair value estimate, including one that suggests as much as 10% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Home Depot research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Home Depot. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Home Depot's overall financial health at a glance.
Looking for more investment ideas beyond Home Depot?
Once the Home Depot story is clear, the next step is building a broader watchlist that fits your own risk tolerance and income goals. The Simply Wall St Screener can help you filter for specific traits so you are not just relying on headlines or a single stock.
- If capital preservation comes first for you, start with companies that score well on stability and balance sheet strength through the 11 resilient stocks with low risk scores.
- For investors hunting for quality at a reasonable entry point, use the screener focused on attractively priced high quality companies via the 34 high quality undervalued stocks.
- If you want ideas that the market may not be paying much attention to yet, look at financially sound smaller players using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com