
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
TransUnion (TRU) Stock Looks About Right On A 31% Five Year Slide
TransUnion shares have slipped in recent months, and over a longer stretch the stock has delivered a sizeable decline, which puts fresh attention on what investors are really paying for its earnings today. With the business reshaping how it scores consumer credit and highlighting cyber risk trends for corporate clients, the key issue for you is whether the current price fairly reflects that profit engine.
- The share price is down 30.8% over 5 years, which makes the current valuation hinge even more on how durable and valuable TransUnion's earnings stream proves to be.
- The rollout of a broader 0 to 999 credit scoring system and growing focus on cyber risk services can influence how quickly earnings grow and how predictable cash flows look to the market.
- Your read on TransUnion is one view; the desks covering it have another. See what analysts think TransUnion's shares could be worth.
For investors, the debate is whether TransUnion's current US$77.02 share price is adequately backed by the level and quality of its earnings.
If you want to sanity check TransUnion's earnings question against a wider field of companies, compare it with a curated list of 34 high quality undervalued stocks.
Does TransUnion Look Fairly Valued on Earnings?
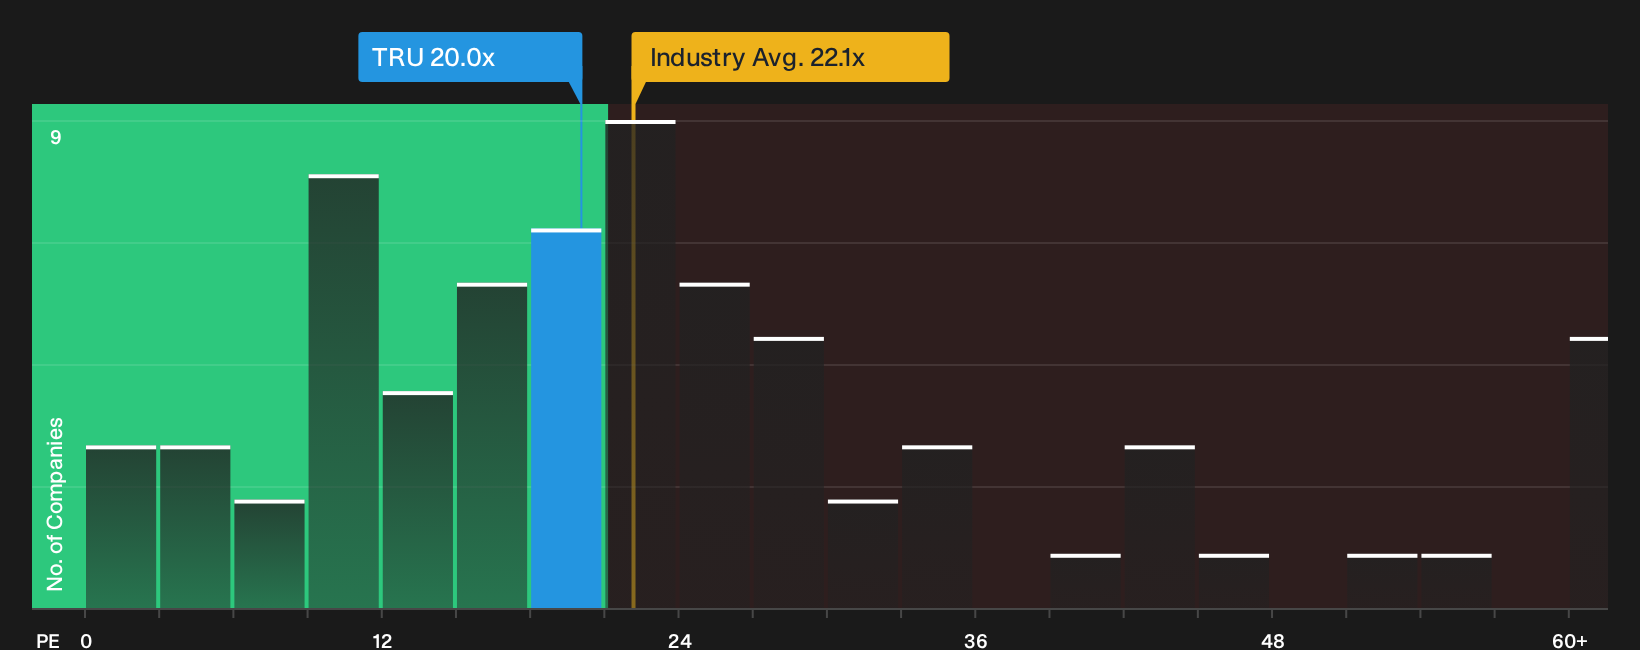
The P/E ratio is a useful lens for TransUnion because earnings are central to how investors view data and analytics businesses. At a P/E of 20.0x, TransUnion trades below the Professional Services industry average of 22.1x and below a peer group average of 27.8x, which suggests the stock is priced at a discount to what similar companies command on this metric.
The current multiple sits close to the level implied by a more tailored fair-value framework that factors in TransUnion's margins, risk profile and scale, so the market is not assigning a clear premium or penalty to its earnings right now. Because the new 0 to 999 credit scoring system is a major change in how the business presents its core product, the fact that the P/E only slightly undercuts that fair-value mark hints that investors are treating the overhaul as more of an evolution than a reset. Explore the numbers behind TransUnion's P/E valuation.
The TransUnion Narrative: What Would Justify Today's Price?
Simply Wall St Narratives continue the P/E discussion for TransUnion by outlining which paths for future growth, profitability and earnings would need to occur for the stock to be worth materially more or less than it is today. Each narrative explains the assumptions behind its fair value so you can compare them with TransUnion's actual results as they are reported, all within the Community page.
One of the top community narratives on TransUnion: 20% undervalued
"Strategic innovation in AI, machine learning, and the roll out of the global cloud native OneTru platform are driving efficiency and faster product launches..."
Discover why this Narrative puts TransUnion at 20% undervalued.
Before you log off, one more TransUnion check belongs next to the valuation story
Price and earnings only tell part of the picture for TransUnion, because the research also flags a set of cautionary checks that could matter for risk aware holders and potential buyers. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com