
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is IREN (NasdaqGS:IREN) Overvalued After Its 8x Three Year Run?
IREN Limited has been on a wild three year ride, with the stock now sitting at US$41.58 after a very large multi year gain and a recent pullback that has investors asking how the current price stacks up against the company’s sales. With fresh headlines around new AI infrastructure projects and funding, the key issue is whether today’s valuation still lines up with what the business is actually generating in revenue.
- Over the past three years, IREN has delivered a share price increase of more than 8x, which puts a lot of weight on whether its revenue base can justify such a step change.
- Recent upgrades from JPMorgan, large Nvidia related contracts and multi billion dollar funding for new GPU facilities all point to higher expected capacity and capital needs, which can shift how investors think about the multiple of sales they are willing to pay today.
- Your read on IREN is one view; the desks covering it have another. See what analysts think IREN's shares could be worth.
The issue now is whether IREN's current share price is properly supported by its sales when you weigh that sharp long term gain against the scale, timing and risk of its AI infrastructure build out.
If you are weighing IREN against other ways to play the AI build out theme, it can help to compare it with 60 AI infrastructure stocks.
Has IREN Run Too Far on Sales?
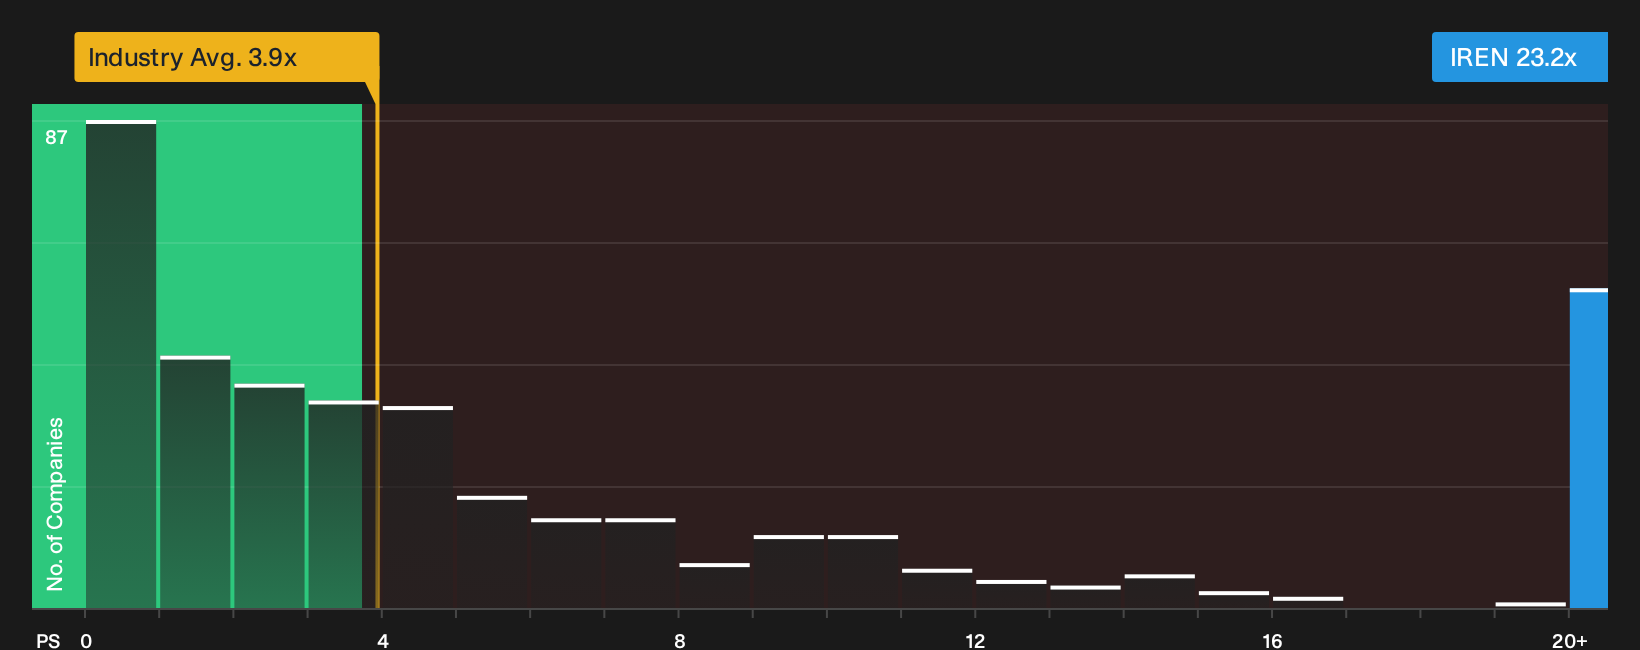
The P/S ratio is a useful lens for IREN because the business is still loss making and investors are effectively paying for revenue and contracted demand rather than current profits. At around 23.2x sales, the stock trades well above the broader software industry average of about 3.9x, and it also sits ahead of the nearer peer group, which clusters around 15.3x.
On this framework, the tailored fair multiple that blends IREN’s growth profile, margins, size and risk points to a lower P/S than where the shares change hands today, which means the stock screens as overvalued on sales. Because the recent JPMorgan upgrade and fresh AI capacity headlines focus attention on future contracts and GPU build outs, the current valuation implies investors are already paying a premium for that execution. To check how large that gap is and what it might mean for your own return expectations, you can compare IREN's present P/S to the modelled fair range with. Explore the numbers behind IREN's P/S valuation.
The IREN Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for IREN act as the link between today’s rich P/S ratio and the question of what would need to happen next on growth, margins and earnings for the stock to be worth materially more or materially less than the current share price. They sit on IREN's Community page. Rather than a single multiple or model output, each Narrative lays out the specific assumptions behind its view of fair value so you can track those expectations against actual results over time.
One of the top community narratives on IREN: 42% undervalued
"IREN represents an intriguing yet risky investment opportunity in the evolving landscape of Bitcoin mining and computational services..."
Discover why this Narrative puts IREN at 42% undervalued.
One more IREN puzzle piece worth checking
IREN’s future is not only about contracts and P/S multiples; it also hinges on who is steering the business and how their pay lines up with your interests. See who runs IREN and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com