
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Marsh Share Changes In Europe
- Marsh & McLennan Companies recently reshaped its European leadership, appointing Jens Florian-Jansen to a new head of European insurance role and naming Matthias Grass president of Marsh Risk Germany.
- These moves concentrate decision-making in Europe, which could affect how Marsh & McLennan allocates resources, prices risk services, and responds to regulatory complexity across the region.
- We will now assess how Marsh & McLennan's investment narrative could shift as European leadership centralizes under Jens Florian-Jansen.
Scan how Marsh & McLennan Companies reshaping its European leadership compares with peers by reviewing our hand picked 11 resilient stocks with low risk scores focused on steadier balance sheets and controlled risk profiles.
Marsh & McLennan Companies Investment Narrative Recap
To own Marsh & McLennan Companies, you need to be comfortable with a risk and consulting specialist that leans on complex global risks, recurring advisory work, and a sizable debt load. In the short term, the key swing factor is execution on fee growth while insurance pricing and consulting demand remain choppy. These new European leadership roles appear incremental rather than a material near-term catalyst.
The biggest operational risk remains pressure on margins if pricing in property and reinsurance stays weak and large acquisitions such as McGriff are harder to integrate. Centralising European decision making under Jens Florian Jansen could help coordination, but it does not directly change those integration or pricing challenges.
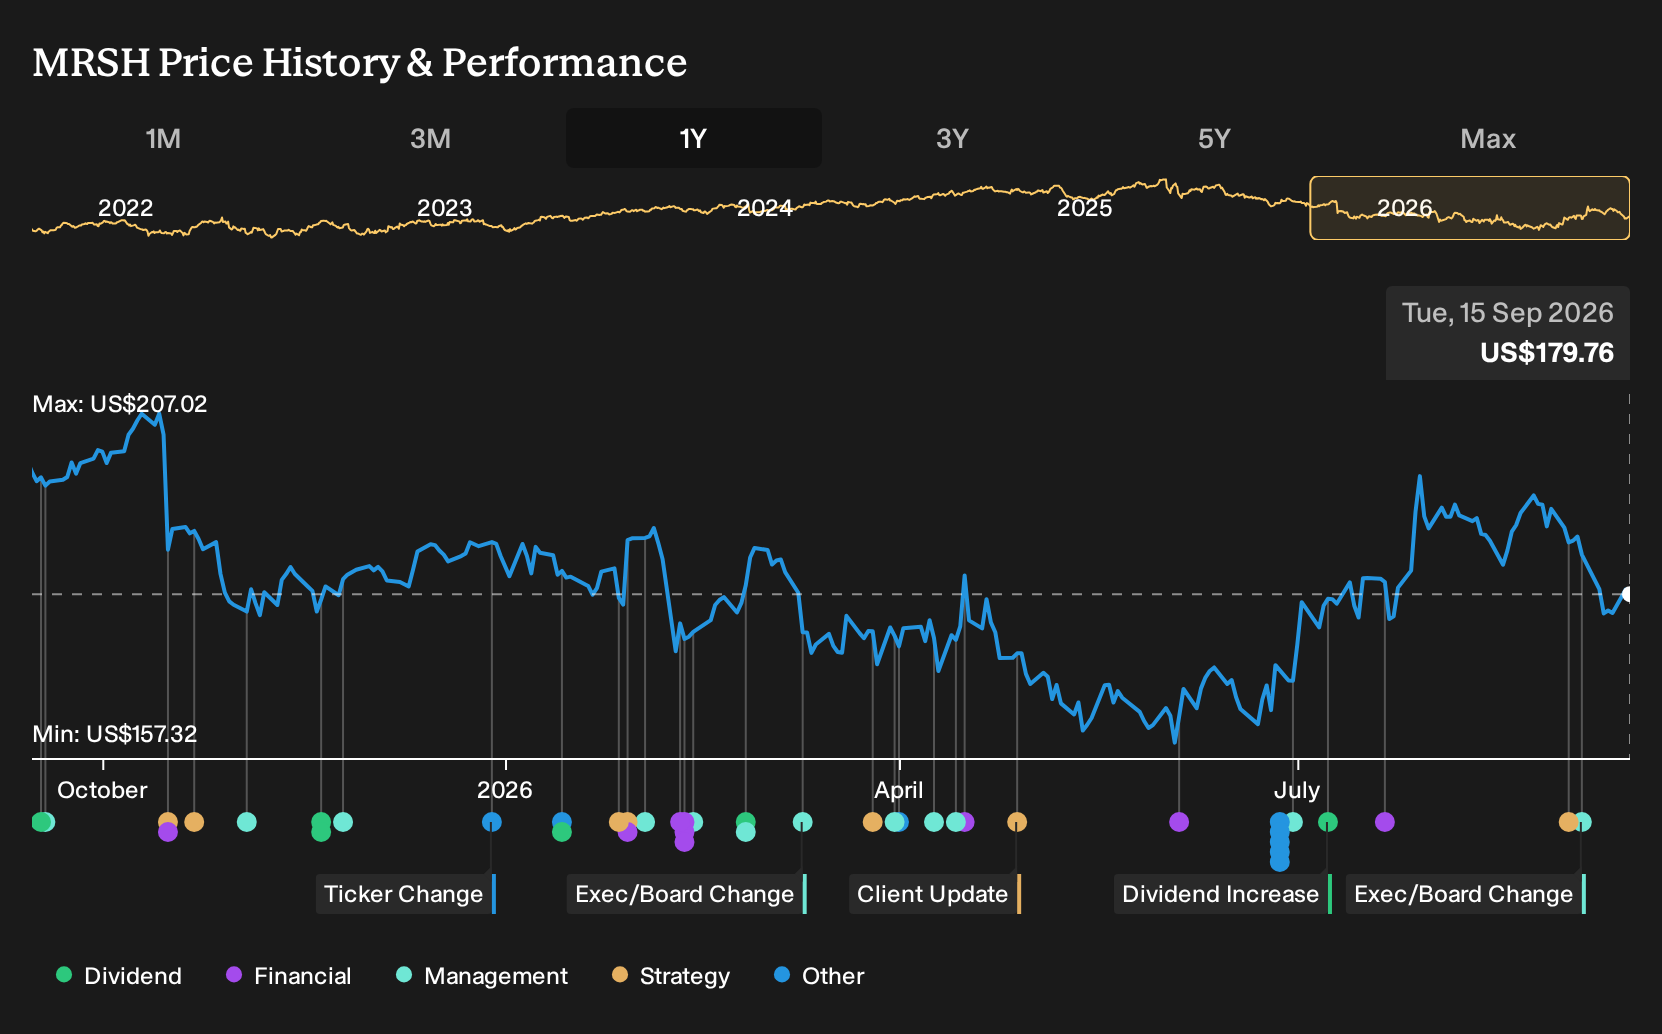
With no fresh financial announcements tied directly to this reshuffle, the most relevant reference point is still analysts’ expectations for Marsh & McLennan. They currently project earnings growth of about 10.4% a year and revenue growth of about 4.2% a year. Those expectations sit against a recent one-year total shareholder return that declined 6.8% and a three-year return that fell 4.6%.
The European appointments fit into that backdrop as an execution story. Investors following the stock can focus on whether this leadership structure helps the business win and retain European clients, protect consulting revenues in softer demand periods, and support the integration of acquired operations without adding to already high debt-related risk.
Marsh & McLennan Companies' current analyst storyline points to about US$31.5b in revenue and US$5.4b in earnings by 2029. This outlook is built on 4.1% yearly revenue growth and an earnings increase of roughly US$1.4b from US$4.0b today.
Uncover why Marsh & McLennan Companies' fair value indicates a 14% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster between roughly US$205 and US$285 a share, which signals a wide spread in what private investors think Marsh & McLennan is worth. Set that beside risks around softer property and reinsurance pricing, and you see how sharply opinions can diverge. Explore those alternative viewpoints before forming your own stance.
Explore 3 other Marsh & McLennan Companies fair value estimates, including one that suggests potential upside of as much as 58% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis and instincts.
- A great starting point for your Marsh & McLennan Companies research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Marsh & McLennan Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Marsh & McLennan Companies' overall financial health at a glance.
Looking for more Marsh & McLennan Companies style ideas?
If you want to stress test your thesis on Marsh & McLennan Companies, it helps to compare it with other businesses that share similar qualities or offer very different risk and return profiles.
- For investors who want potential mispricing with quality fundamentals, scan a curated group of 34 high quality undervalued stocks that may offer a more attractive entry point on a risk adjusted basis.
- If capital preservation is high on your list, weigh Marsh & McLennan Companies against a 11 resilient stocks with low risk scores that focuses on steadier earnings and more predictable balance sheets.
- Income focused readers can size up Marsh & McLennan Companies alongside a 6 dividend fortresses that screens for higher yield payouts supported by robust fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com