
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
British American Tobacco (LSE:BATS) Stock May Be Undervalued At Current Earnings Levels
British American Tobacco has seen its share price move over multiple time frames, and the stock most recently closed at £42.23. With that backdrop, the question for investors is whether that price is appropriately supported by the earnings the business is generating today.
- Over the past 5 years, British American Tobacco has delivered a total return of 131.1%, which puts a lot of weight on whether the current earnings base can support that kind of share price journey.
- The group relies heavily on its ability to convert profit into cash and manage debt, which can shape how durable its earnings look against the current P/E and any comparison to the Fair Ratio benchmark.
- There is a second opinion on British American Tobacco worth weighing. See what analysts think British American Tobacco's shares could be worth.
The stock's next move may depend on whether British American Tobacco's current earnings justify paying around £42 per share today.
If you want other context points for British American Tobacco's earnings-based price, it can help to line it up against 9 high quality undervalued stocks.
Is British American Tobacco Still Cheap on Earnings?
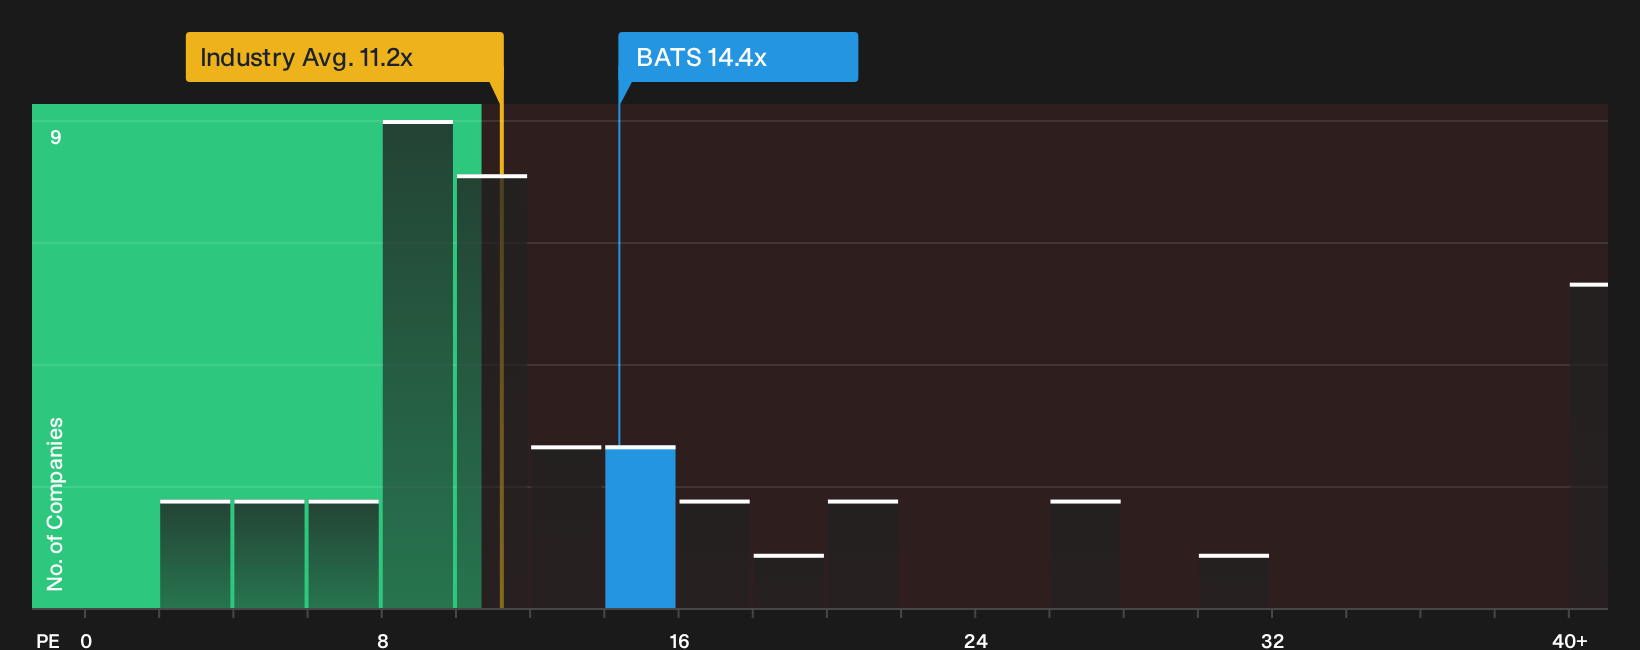
The P/E lens suits British American Tobacco because earnings remain a central anchor for how investors think about this kind of mature consumer business. On this measure, the shares trade on a P/E of about 14.4x, which is higher than the tobacco industry average near 11.2x but below the peer group average around 18.3x. That combination points to a stock that is not priced at the bottom of the sector, yet also not carrying the richer tag seen in some comparable companies.
A model that looks at British American Tobacco's own growth profile, margins, size and risk suggests a higher P/E would typically be expected for this earnings stream. As a result, the current 14.4x sits below that tailored benchmark. For a holder, that gap raises the question of whether the market is applying a cautious view to future profits, or simply offering exposure to the current earnings base without a large premium. Explore the numbers behind British American Tobacco's P/E valuation.
The British American Tobacco Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E discussion for British American Tobacco leaves off by spelling out the earnings, margin and growth paths that would need to unfold for the stock to be worth materially more or less than the current share price, and they sit on the company's Community page. Instead of a single output from a ratio or model, Narratives lay out the specific future that number assumes so you can watch over time whether that scenario actually plays out.
The community is split between those who see British American Tobacco as a cash engine in transition and those who focus on regulatory and ESG headwinds.
Bull case: 18% undervalued
"Digital transformation, operational streamlining, and targeted cost savings programs are releasing capital for reinvestment in high-return growth opportunities and innovation…"
Discover why this Narrative puts British American Tobacco at 18% undervalued.
Bear case: 7% overvalued
"Accelerating global regulation and legislative restrictions on both combustible and next-generation tobacco products are expected to further limit BAT's ability to grow volumes and raise prices…"
Explore why this Narrative puts British American Tobacco at 7% overvalued.
For British American Tobacco, the price is only one piece of the puzzle
British American Tobacco's current earnings and P/E tell only part of the story, since analyst expectations for where the business could be a few years from now offer a separate lens to compare with today's valuation. Explore where analysts expect British American Tobacco to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com