
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Vistra (VST) Stock May Be Undervalued Following Fresh AI Power Deal News
Vistra has delivered a very large 5 year return, yet the recent pullback in the stock brings the focus back to a simple question for investors. Is the current share price still in step with what the business earns today and what those earnings may reasonably support over time?
- Vistra's very large gain over the past 5 years puts a lot of expectations into the current valuation and raises the stakes on how much of that performance its earnings can support.
- Fresh attention on Vistra as a power supplier to data center operators, including a long term nuclear energy agreement with Amazon Web Services, can influence how durable investors think its earnings base may be and how predictable future cash flows might look.
- There is a second opinion on Vistra worth weighing. See what analysts think Vistra's shares could be worth.
The stock's next move may depend on whether Vistra's current earnings justify the price investors are being asked to pay today.
For context on Vistra's role in powering AI and data centers, it can help to line it up against other energy infrastructure players using the 38 power grid technology and infrastructure stocks.
Is Vistra Still Cheap on Earnings?
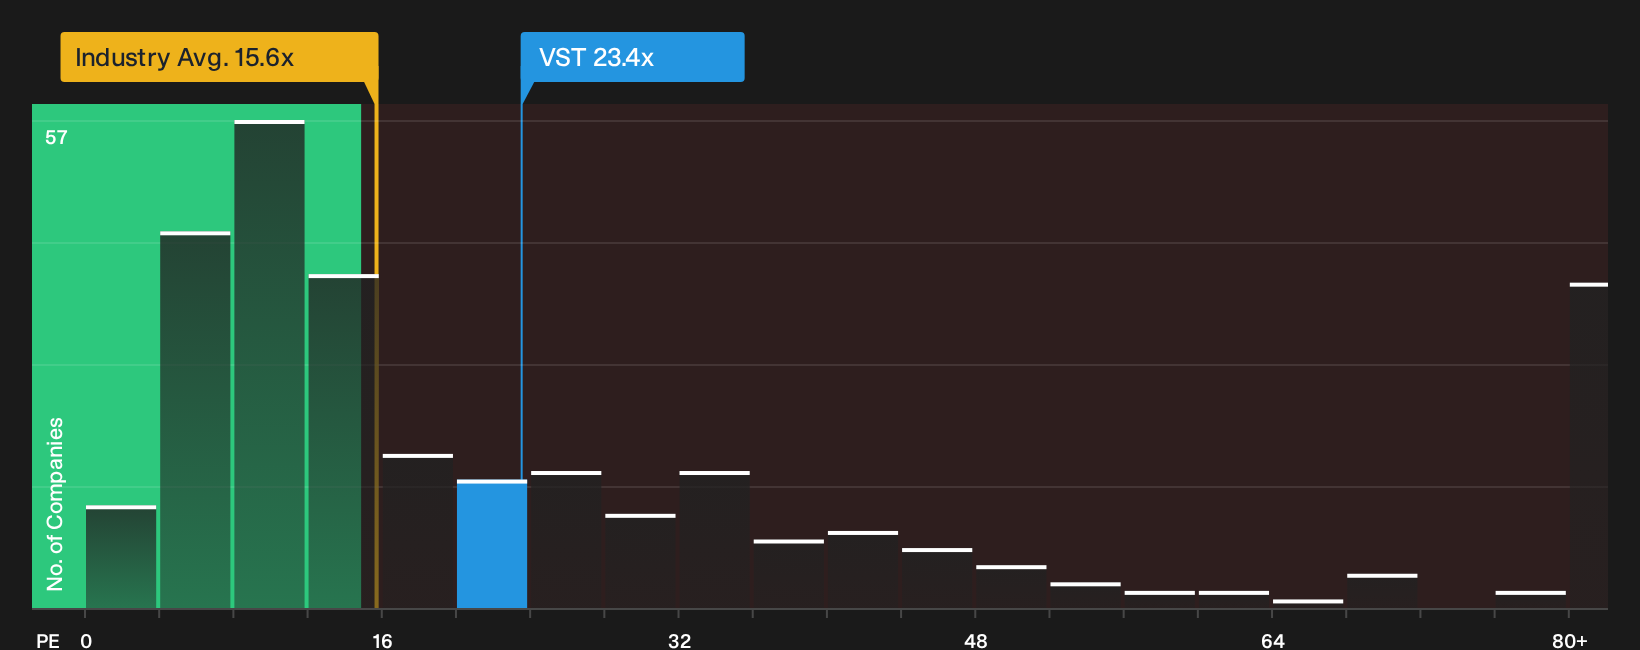
The P/E ratio fits Vistra because earnings are the key driver of value for a capital intensive power producer. On this measure, the stock trades on about 23.4x earnings, which is above both the renewable energy industry average of roughly 15.6x and the peer group level of about 17.7x. That gap suggests investors are paying a higher price for each dollar of Vistra's profit than for many comparable utilities.
The fair value framework, which estimates the multiple you might expect given Vistra's profit profile, balance sheet and risk mix, points to a higher P/E than where the shares trade today. On this specific lens, the current 23.4x screens as undervalued. Because the long term supply deal with Amazon Web Services puts real numbers behind Vistra's data center exposure, the market premium to the sector appears more tied to contracted earnings quality than to speculative enthusiasm. Explore the numbers behind Vistra's P/E valuation.
The Vistra Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St extend the valuation puzzle for Vistra by explaining what would need to happen to future growth, margins and earnings for the current share price to look meaningfully higher or lower over time. They sit within the Community page, where investors discuss those possibilities. Each scenario sets out the specific assumptions behind its fair value view so you can track how those expectations compare with Vistra's actual results as they are reported.
Community views on Vistra split between a strong upside story and a more restrained outlook that leans on policy and demand risks.
Bull case: 52% undervalued
"In January 2026, Vistra signed 20-year power purchase agreements to supply Meta with more than 2,600 megawatts of nuclear electricity across three PJM plants..."
Discover why this Narrative puts Vistra at 52% undervalued.
Bear case: 9% overvalued
"Accelerating renewable buildout and battery storage adoption are likely to continue pressuring wholesale electricity prices, eroding Vistra's pricing power and compressing net margins..."
Explore why this Narrative puts Vistra at 9% overvalued.
One more big question for Vistra that this valuation has not touched
Price multiples and scenarios tell you what the market is paying for Vistra today, but analyst projections a few years out give you a separate yardstick to compare with that price. Explore where analysts expect Vistra to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com