
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To CoStar Group Stock After Homes.com Leadership Change
- CoStar Group recently appointed portal veteran Felix Kusch as President of Homes.com, coinciding with the residential segment posting its first profitable quarter and 66% year-over-year revenue growth.
- The move signals a tighter focus on execution at Homes.com, where Kusch’s track record running major European portals could be central to scaling CoStar Group’s U.S. residential marketplace ambitions.
- We will now see how CoStar Group's investment narrative could be influenced by Homes.com's leadership change and residential profitability milestone.
Scan how CoStar Group fits into the broader real estate opportunity set by reviewing a curated list of solid balance sheet and fundamentals (22 results) that investors are watching as this sector evolves.
CoStar Group Investment Narrative Recap
To own CoStar Group, you need to be comfortable with a story built on real estate data, online marketplaces and heavy reinvestment. Residential is now showing early profitability, while commercial still leans on office markets where Canadian vacancy is forecast to ease from 9.8% in Q2 2026 to 8.7% by 2028. The near term catalyst is whether Homes.com and other platforms can convert product traction into cleaner margins after a period of higher spending.
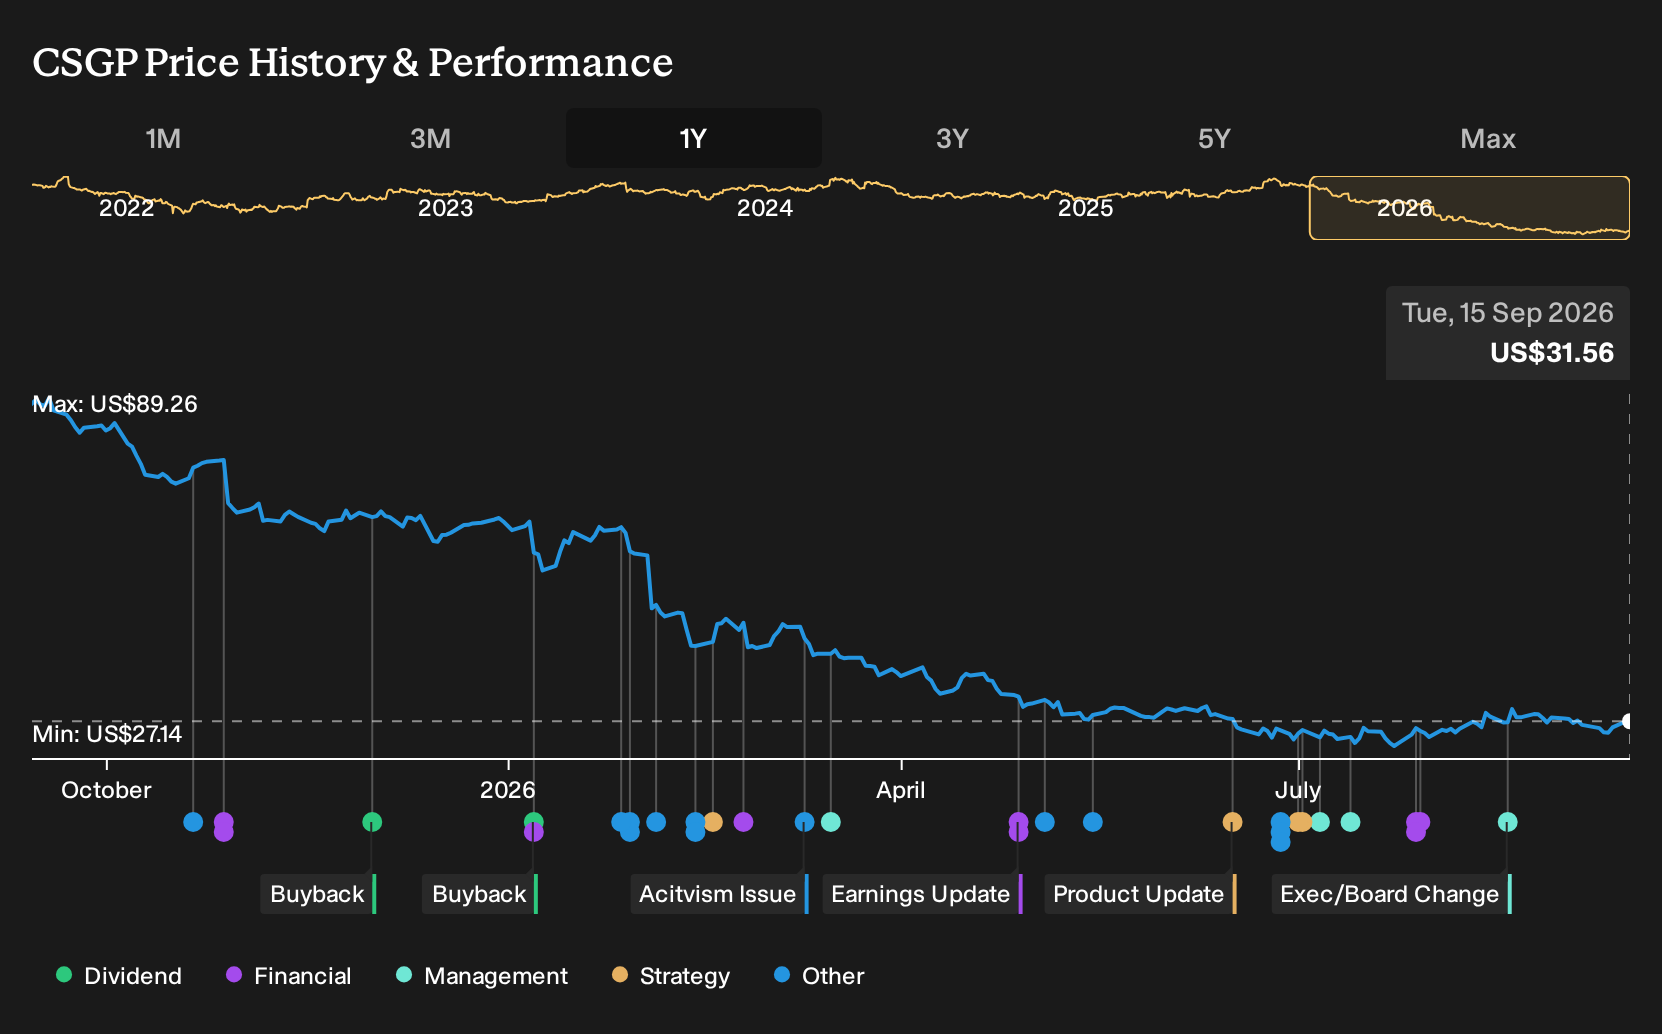
The key risk has not changed much. If Homes.com and integrated tools like Matterport do not scale efficiently, expenses can stay elevated against modest net income of US$74.0 million on US$3.6b of revenue. CoStar Group’s shares have also lagged the S&P 500 and the US real estate sector, so patience with underperforming total returns is still part of the thesis.
The leadership change at Homes.com looks most relevant. Felix Kusch now steps into a residential segment that just delivered its first profitable quarter and 66% year over year revenue growth, plus US$12 million in adjusted EBITDA. That gives investors a clearer operational proof point that the heavy sales and marketing build is starting to show through in the numbers.
Execution risk does not disappear with one profitable quarter. For the catalyst to matter, CoStar Group needs to show that Kusch can repeat and extend that performance without letting acquisition and headcount costs run away again. Competitive pressure from Zillow and others still hangs over customer acquisition costs, so the real test is whether Homes.com can grow while protecting group level profitability.
CoStar Group Forecasts and What They Assume
CoStar Group's narrative projects US$4.9b revenue and US$711.1 million earnings by 2029. This assumes 11.2% yearly revenue growth and an earnings increase of about US$637 million from US$74.0 million today.
Analysts are baking in a meaningful reset in profitability for CoStar Group by 2029. The forecast calls for profit margins to move from 2.1% today to 14.5% in three years. That would put the business on a very different earnings base even if top line growth hits only the consensus path.
The jump in earnings from US$74.0 million to US$711.1 million sits at the center of that story. That is a very large uplift in profit in absolute dollar terms, so any wobble in Homes.com monetisation, commercial leasing demand or cost control could leave actual results well short of the earnings curve implied in the models.
That same earnings line underpins how some analysts are looking at valuation. To get to their price targets, forecasts assume CoStar Group trades on a P/E multiple of 23.7x in 2029 compared with 171.2x today. This would still sit above the current 16.7x P/E for the broader US real estate industry.
Revenue expectations sit closer to the existing scale of the business. The consensus view points to about US$4.9b in sales by 2029. This lines up with an 11.2% annual growth rate over the next three years and a view that subscription churn, pricing and international expansion stay on a relatively steady track.
Those top down figures intersect with capital allocation choices. Analysts currently assume the share count contracts by about 4.39% per year. This would support earnings per share even if headline profit landed closer to the lower end of the US$711.1 million to US$860.0 million range.
All of these moving parts are then pulled into a single present value using an 8.5% discount rate. That is the lens used to translate future earnings, margin expansion and a lower P/E into the current analyst consensus target of US$37.3 per share, compared with a recent price around US$31.26 and a spread of US$25.0 to US$53.0 across the most cautious and most optimistic forecasts.
Uncover why CoStar Group's fair value indicates an 18% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
For CoStar Group, the bullish twist is AI. The most optimistic analysts were already pencilling in US$5.2b of revenue and US$837.7 million of earnings by 2029, partly on the idea that AI tools lift monetisation per visitor. With the Homes.com leadership change and fresh profitability, you can now ask whether those pre news assumptions feel closer or further away, and explore both sides of that debate.
Explore 4 other CoStar Group fair value estimates, including one that suggests potential upside of up to 394% from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CoStar Group research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CoStar Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CoStar Group's overall financial health at a glance.
Looking For More CoStar Group Style Ideas?
If the CoStar Group story has sharpened your thinking about quality, risk and payoff, you might want to widen the net across other listed businesses using the Simply Wall St Screener.
- For investors who want a starting universe of companies that already pass basic balance sheet and fundamentals checks, consider scanning a curated list of solid balance sheet and fundamentals (22 results) that can anchor deeper research.
- If you care most about resilience and are aiming to limit downside, filter for 11 resilient stocks with low risk scores that may better match a more defensive approach.
- Those hunting for potential future leaders with cleaner financial profiles can review a focused 16 high quality undiscovered gems that often sit outside the usual large cap lists.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com