
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Barrick Mining (B) Stock May Be Overvalued After Its 179% Run
Barrick Mining has delivered a powerful long term share price run, and that leaves investors weighing whether the current US$42.70 price can still be squared with the cash the business is expected to generate. After such a move, the central issue is how well the stock lines up with its own Discounted Cash Flow (DCF) based view of intrinsic value.
- The share price has climbed about 179.5% over the past 3 years, which puts a lot of past optimism and future cash flow expectations on the table for anyone looking at Barrick Mining today.
- The group’s ability to convert its mining assets into steady free cash flow, while funding ongoing projects and upkeep, can have a direct impact on how reliable any intrinsic value estimate based on those cash flows really is.
- What if you looked at Barrick Mining through its earnings instead? See why Barrick Mining's 10.7x P/E tells a different valuation story.
For investors, the debate is whether Barrick Mining’s current share price is properly aligned with what its cash flows suggest the business is worth over time.
If you want to test the same cash flow lens you are using on Barrick Mining across a wider field, line it up against 34 high quality undervalued stocks.
Is Barrick Mining Getting Expensive on Cash Flow?
The Discounted Cash Flow (DCF) approach here looks at the cash Barrick Mining is expected to generate for shareholders and discounts it back to today’s dollars. Over the latest twelve months the group produced about $4.6b of free cash flow, and the model assumes this does not keep climbing, but instead trends down over time from analyst forecasts into more muted estimates.
Those projections eventually move from analyst inputs to mechanically fading free cash flow estimates, which places more weight on Barrick Mining’s ability to sustain its current project pipeline rather than pursue aggressive expansion. When that stream of cash flows is discounted and aggregated, the resulting intrinsic value comes out meaningfully below the current $42.70 share price, which implies the market is paying a premium over what these cash flow assumptions support. Find out what Barrick Mining could be worth using our Discounted Cash Flow (DCF) estimate.
The Barrick Mining Narrative: What Would Justify Today's Price?
Narratives for Barrick Mining pick up where the DCF puzzle leaves off. They spell out which paths for growth, margins and earnings would need to unfold for the stock to be worth materially more or materially less than its current share price. They sit on Simply Wall St's Community page as a set of specific storylines. Each storyline links a particular mix of potential catalysts and risks to a single fair value marker so you can later see which scenario is actually tracking reality.
One of the top community narratives on Barrick Mining: roughly fairly valued
"Barrick Mining Corporation (NYSE: GOLD, TSX: ABX) delivered one of its strongest quarters in recent years, reinforcing its transformation from a traditional gold producer into a dual gold-copper powerhouse..."
Discover why this Narrative puts Barrick Mining at roughly fairly valued.
One More Piece Of The Barrick Mining Puzzle To Check
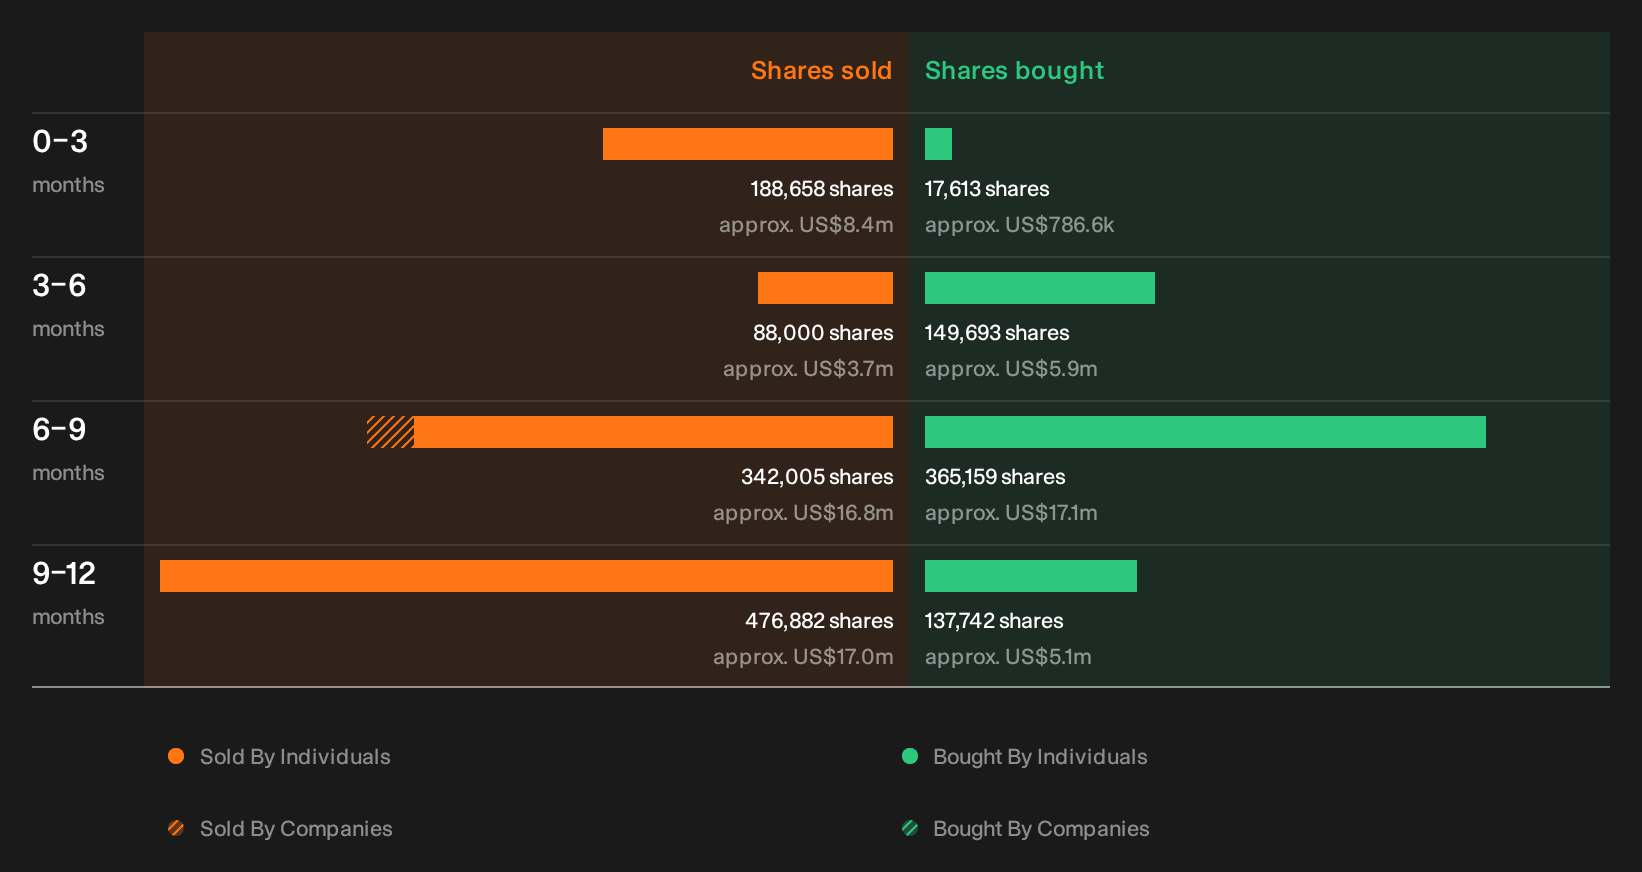
Before you move on from Barrick Mining, it is worth knowing that recent trades by people inside the business have been picked up by our checks, with the specific sellers, trade sizes and potential meaning left for you to explore. See the recent insider selling flagged for Barrick Mining.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com