
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Intapp Stock's AI Product Launch Means For Shareholders
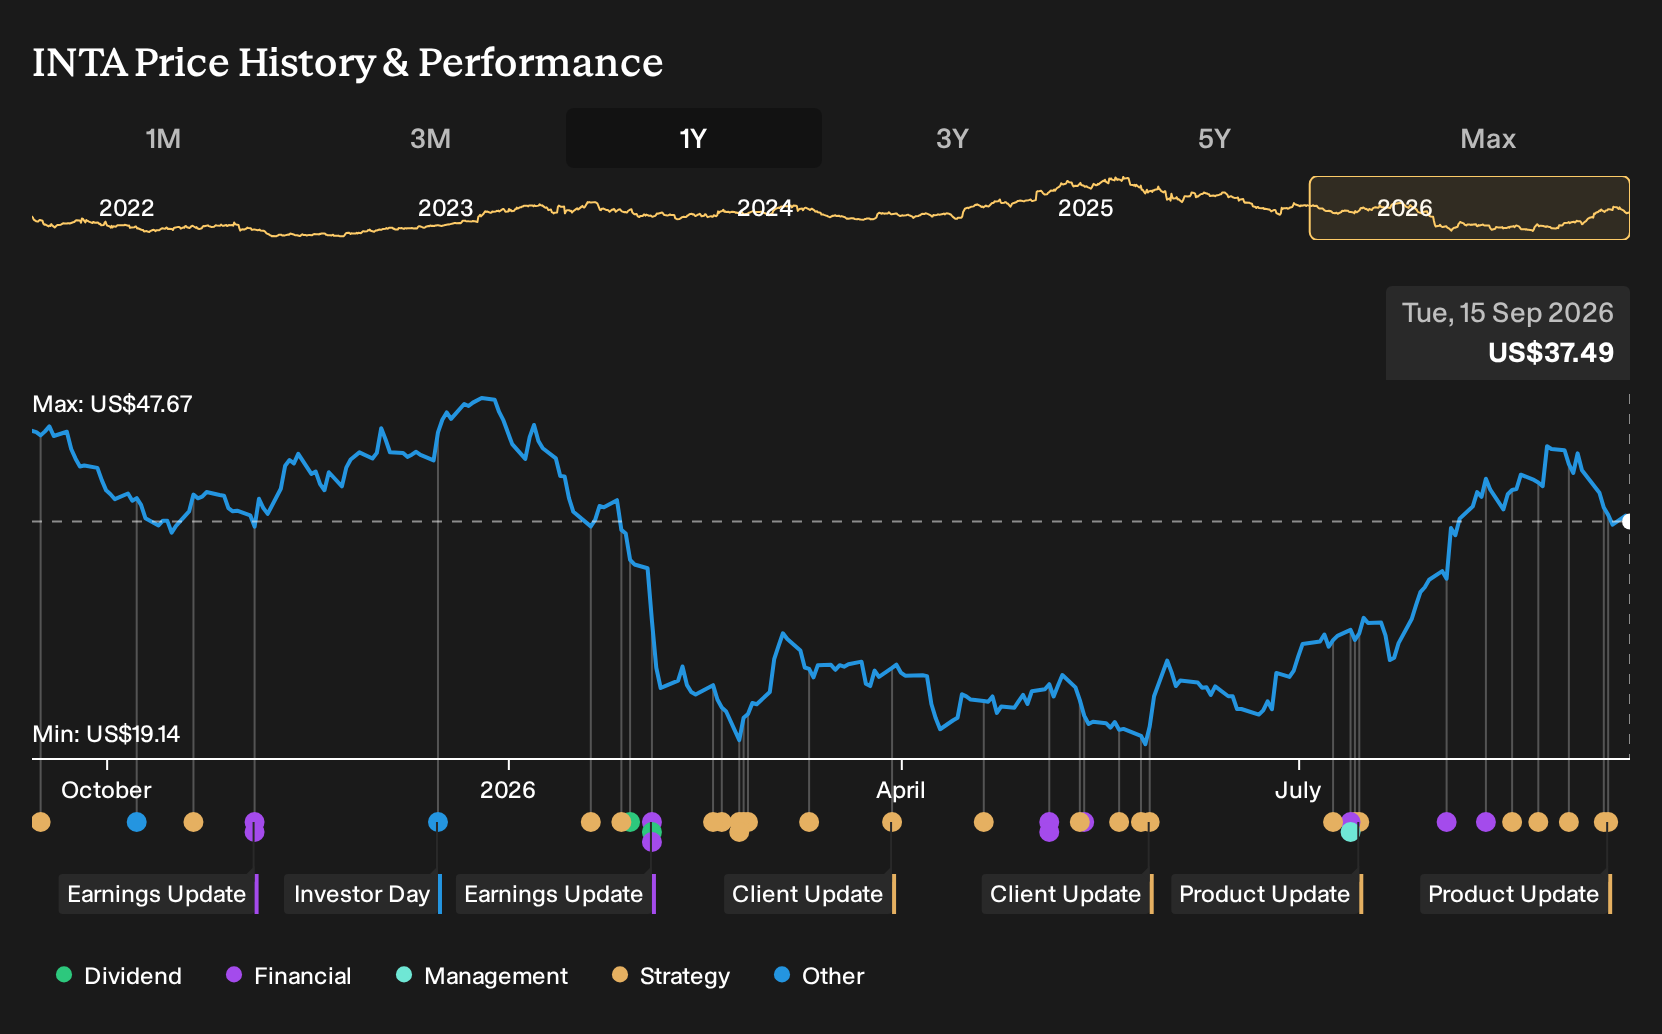
- Intapp has recently rolled out DealCloud with the Celeste plug-in for ChatGPT for Financial Services and launched the Intapp Profitability Network, tying its Firm AI tools into both financial and legal workflows for existing and future clients.
- The pairing of firm-specific AI, tight data governance, and a certified partner ecosystem suggests Intapp is pushing to embed itself deeper into clients’ everyday decision making and profitability management.
- We will now see how this push to embed Celeste across DealCloud and the Profitability Network could influence Intapp’s broader investment narrative.
Intapp Investment Narrative Recap
To own Intapp, you have to believe its vertical AI and cloud platform can turn a large installed base into durable, higher margin subscription economics. The key near term catalyst is whether these Firm AI products, including Celeste, deepen usage across existing legal and financial clients and support the path from current losses of about US$41.3 million toward profitability.
The biggest risk is that this AI and cloud push does not translate into enough contract expansion to offset pricing pressure, partner costs, and any friction as firms move off older models. The latest announcements look directionally helpful to that thesis but do not, on their own, change the near term risk profile.
The Intapp Profitability Network is the clearest operational bridge between the new Firm AI story and existing catalysts around higher cloud adoption and better economics. It ties Intapp Time with Celeste into certified tools that touch pricing, staffing, billing, and collections, which is exactly where legal clients feel margin pressure and look for measurable efficiency.
For you as an investor, the question is whether firms actually run more of their workflows through Intapp once these integrations reach general availability. Strong execution and partner performance could support higher net retention and better use of the firm’s data. Weak adoption, or integration issues, would feed directly into the existing risks around partner reliance and differentiation.
Intapp's current loss of about US$41.3 million sits against analyst expectations for earnings of US$88.7 million by 2029, with those same forecasts pointing to roughly 16.4% yearly revenue growth and projected revenues of US$912.0 million in that year. This implies an earnings swing of roughly US$130.0 million from today to the 2029 consensus target.
Uncover why Intapp's fair value indicates a 5% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For Intapp, the alternate, more optimistic angle hinges on rapid Firm AI adoption. The most bullish analysts were already penciling in revenue of about US$969.7 million and earnings of US$118.2 million by 2029, well above consensus. Those projections came before these Celeste launches, so views may change as new data becomes available.
Explore 4 other Intapp fair value estimates, including one that suggests as much as 60% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Intapp research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Intapp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Intapp's overall financial health at a glance.
Looking for more ideas beyond Intapp?
If the Intapp story has sharpened your thinking about where earnings quality and balance sheet strength really matter, you might want to broaden the view using the Simply Wall St Screener.
- For investors who care most about resilience, filter for businesses with steadier risk profiles using our 11 resilient stocks with low risk scores to find options that may better match your tolerance for volatility.
- If value is your focus, check companies that combine quality fundamentals with potentially attractive pricing by scanning the 34 high quality undervalued stocks which surfaces ideas already passing strict financial filters.
- When you want sturdier finances at the core of your watchlist, narrow the field to companies with stronger balance sheets by running the list of solid balance sheet and fundamentals (22 results) to see which ones meet your standards.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com