
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Macy's (M) Stock Looks Below Fair Value After Outlook Upgrade
Macy's has delivered a powerful rebound over the past few years, and investors now have to ask whether the current share price around US$22 is adequately grounded in the retailer's earnings power. The recent mix of upbeat profit news and cautious commentary has sharpened that question around what you are really paying for when you buy Macy's today.
- Over the past 3 years the stock has gained 128.5%, which puts a lot of weight on the idea that the business can sustain or improve its earnings base from here.
- Management has raised its outlook for full year net sales and adjusted earnings per share, which can support a view that future profit levels and cash generation may justify a higher valuation on an earnings basis if execution holds.
- The analysts covering Macy's have run their own numbers. See what analysts think Macy's's shares could be worth.
The issue now is whether Macy's current valuation is properly supported by the earnings it produces today and what those profits imply over the coming years.
If you are weighing whether Macy's current P/E feels rich or reasonable after its outlook upgrade, it can help to compare that same earnings lens across 34 high quality undervalued stocks
Does Macy's Look Undervalued on Earnings?
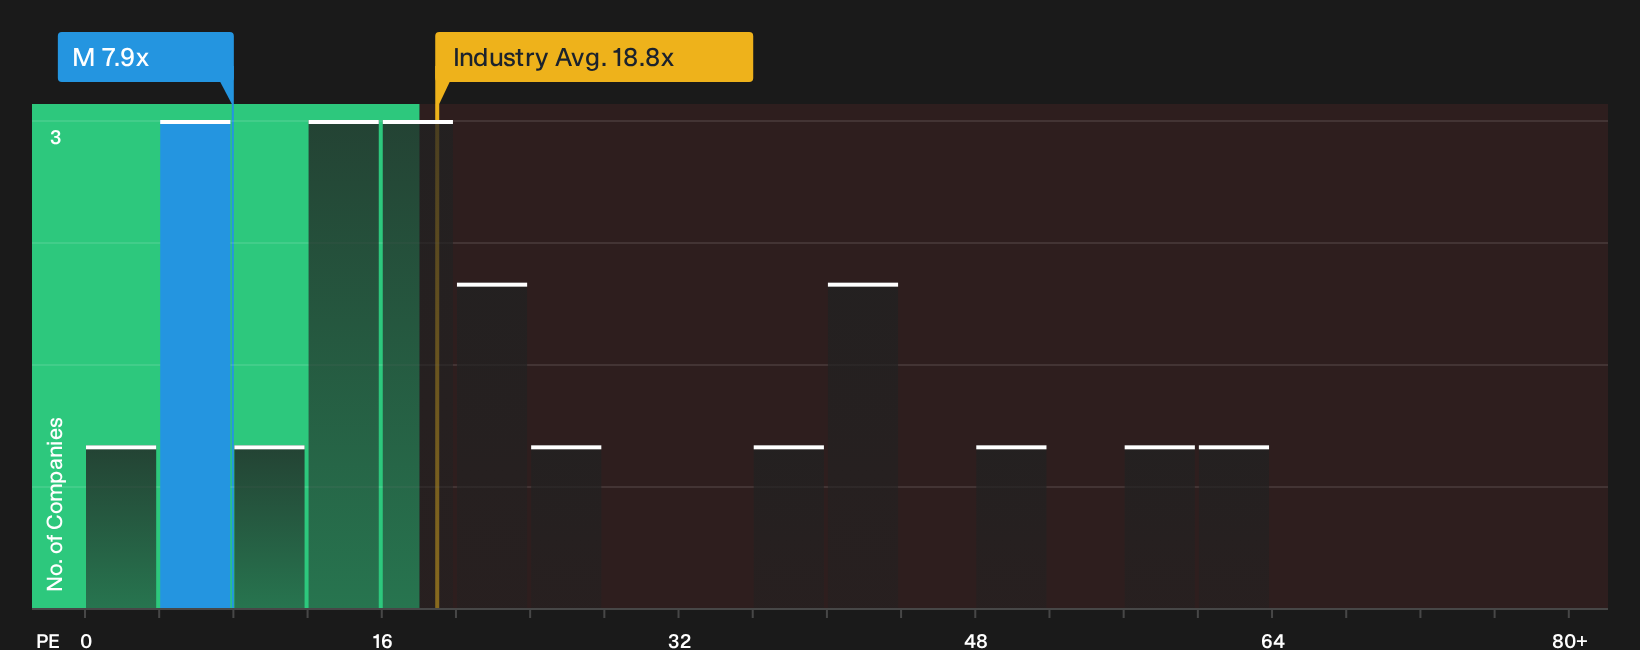
P/E works well for Macy's because earnings are a key focus for this established retailer. On this measure, the stock trades on a P/E of 7.7x, which is below both the Multiline Retail industry average of 18.8x and the peer group on 13.3x. The current level also sits under the multiple implied by a tailored fair value framework that blends the business profile, profitability, size and risk.
Because management has just lifted full year earnings guidance after stronger Q2 results, the gap between Macy's P/E and those benchmarks stands out even more. For anyone weighing the outlook against this pricing, the key question is whether the recent earnings delivery and guidance provide enough comfort that the current discount reflects caution rather than something more permanent. Explore the numbers behind Macy's's P/E valuation.
The Macy's Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E debate leaves off for Macy's by spelling out which combinations of future growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than it is today on the market. Each scenario ties a fair value to a particular view of Macy's potential catalysts and key risks, so you can track over time which version of the story is actually unfolding on the Community page.
One of the top community narratives on Macy's: 26% undervalued
"Macy's increased focus on private label expansion, omni channel investments, and experiential urban retail strongly positions it for above market sales and margin growth..."
Discover why this Narrative puts Macy's at 26% undervalued.
Macy's price is only one piece of the decision
Before making any call on Macy's, it helps to look at who is actually steering the retailer and how their rewards line up with your interests as a shareholder. See who runs Macy's and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com