
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is BeOne Medicines (ONC) Reasonably Priced Or Looking Rich On Earnings?
BeOne Medicines has delivered a strong multi year return, which puts a spotlight on whether the current share price at around US$346.50 is properly supported by what the business earns. With that kind of track record already on the table, the real issue for you is how much of those earnings the market may already be pricing in.
- Over the past 3 years the stock has gained 65.9%, so anyone looking at BeOne Medicines today needs to ask how much of its earnings power is already reflected in that move.
- The company’s ability to convert its research and development work into profitable products, and then into recurring earnings, can play a central role in how reliable those profits look against the current market valuation.
- Your read on BeOne Medicines is one view; the desks covering it have another. See what analysts think BeOne Medicines's shares could be worth.
The stock’s next move may depend on whether its current earnings are strong and durable enough to justify the price investors are being asked to pay today.
To stress test whether BeOne Medicines still feels reasonably priced on its earnings, it can help to compare it with other companies in the same broad theme using 34 high quality undervalued stocks.
Is BeOne Medicines Getting Expensive on Earnings?
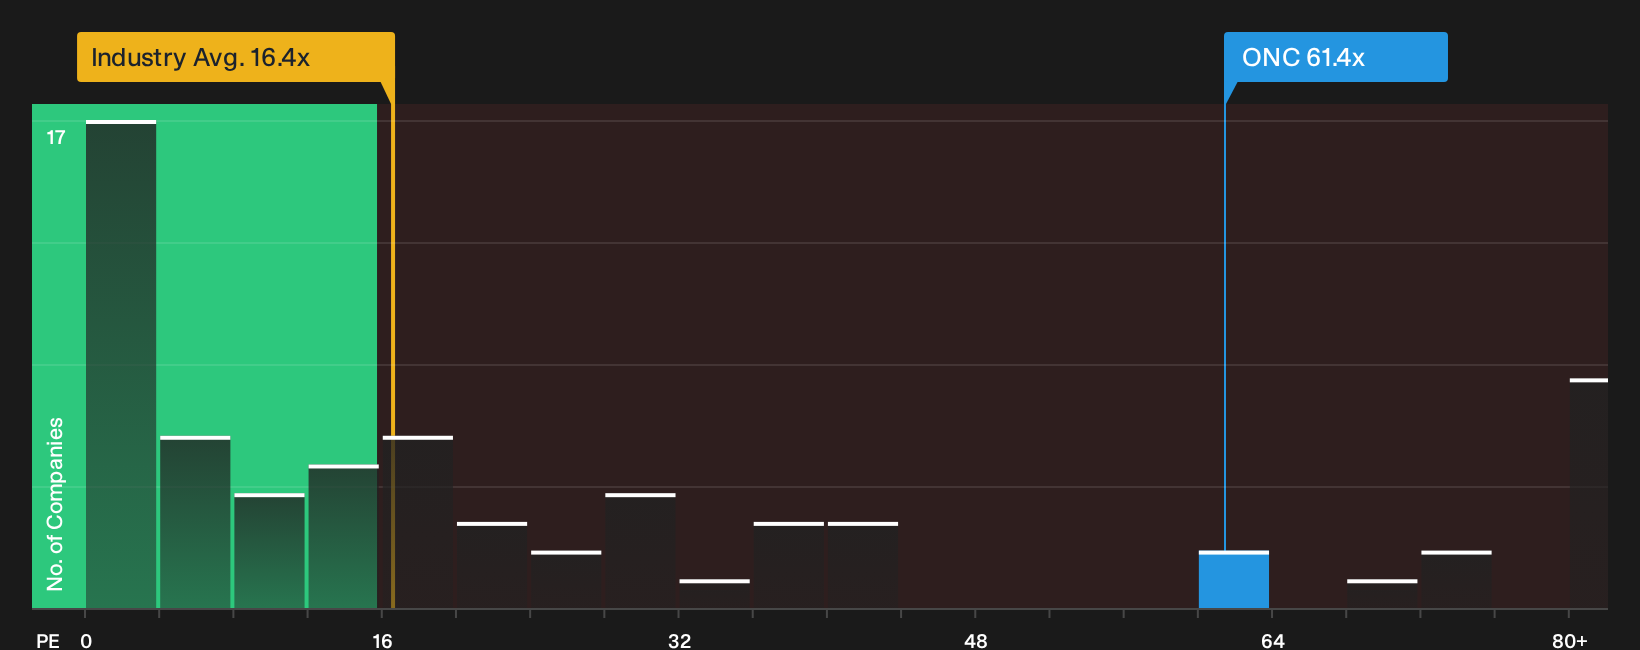
The P/E ratio works well for BeOne Medicines because earnings are a key focus for how investors judge research driven biotechs once they reach profitability. At a P/E of about 60.1x, the stock trades well above the broader Biotechs industry average of roughly 16.4x, which already indicates that the market is putting a rich tag on each dollar of profit.
Relative to a peer group that clusters closer to 27.8x, BeOne Medicines also changes hands at a higher earnings multiple than many directly comparable companies. A tailored fair multiple that factors in the firm’s growth profile, margins, size and risk points to a lower P/E than where the shares trade today. This is why this setup screens as overvalued on this metric. Before treating that gap as decisive, you would want to weigh how durable you think current profits are, how realistic the cash flow projections look and how much risk you are prepared to underwrite at this price. Explore the numbers behind BeOne Medicines's P/E valuation.
The BeOne Medicines Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for BeOne Medicines pick up where this valuation puzzle leaves off by setting out which future paths for growth, margins and earnings would need to play out for the shares to look materially higher or lower than today’s price. They sit on the stock’s Community page as structured viewpoints. Rather than focusing on a single multiple or model result, each narrative lays out its key assumptions so you can compare them with BeOne Medicines' actual numbers as they come through.
Community views on BeOne Medicines are split between those who see more upside left and those who think expectations already look full.
Bull case: 32% undervalued
"BeOne's highly differentiated next-generation targeted oncology portfolio, bolstered by synergistic combinations and strategic late-stage pipeline assets like sonrotoclax and BTK CDAC..."
Discover why this Narrative puts BeOne Medicines at 32% undervalued.
Bear case: roughly fairly valued
"BeOne Medicines is heavily reliant on BRUKINSA as its primary revenue driver, any loss of exclusivity due to patent cliffs or accelerated approval of biosimilars and generics..."
Explore why this Narrative puts BeOne Medicines at roughly fairly valued.
The BeOne Medicines share price is only one piece of the decision
Before you decide what to do with BeOne Medicines, it is worth knowing that Simply Wall St's broader checks have flagged specific areas of concern that deserve a closer look. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com