
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Evertz Technologies (TSX:ET) Stock Price Faces Margin Pressure Despite Sales Growth
Traders spent the last month backing away from Evertz Technologies, with the share price down about 22% over 30 days, yet Q1 results tell a calmer story. The headline is a modest quarter, not a meltdown. Revenue came in at CA$118.3m and earnings per share landed at CA$0.10, while software and services reached roughly half of total sales. Emotion is focused on the softer profit print. The fundamentals point more to a margin and cash flow debate than to a broken business.
Is Evertz Technologies now a genuine bargain after a 22% pullback, or is the lower P/E simply flagging deeper issues with margins and non-cash earnings? See how the current price compares with cash flow assumptions and peer multiples in our valuation analysis for Evertz Technologies
Q1 2027 Earnings Summary
- Revenue (Q1 2027 vs Q1 2026): CA$118.3m vs. CA$112.1m, a modest top line increase of about 5.5%
- Net Income, excl. extra items (Q1 2027 vs Q1 2026): CA$7.8m vs. CA$11.8m, a decline of about 34%
- Basic EPS (Q1 2027 vs Q1 2026): CA$0.10 vs. CA$0.16, a drop of about 36%
- Gross Margin (Q1 2027 vs Q1 2026): 58.6% vs. a prior-year level described as higher, reflecting margin compression within management’s stated target range
Prefer clean, visual charts instead of scrolling through another block of dense earnings text? See Evertz Technologies’ full financial picture, including a clear view of its recent earnings performance, in our company report for Evertz Technologies.
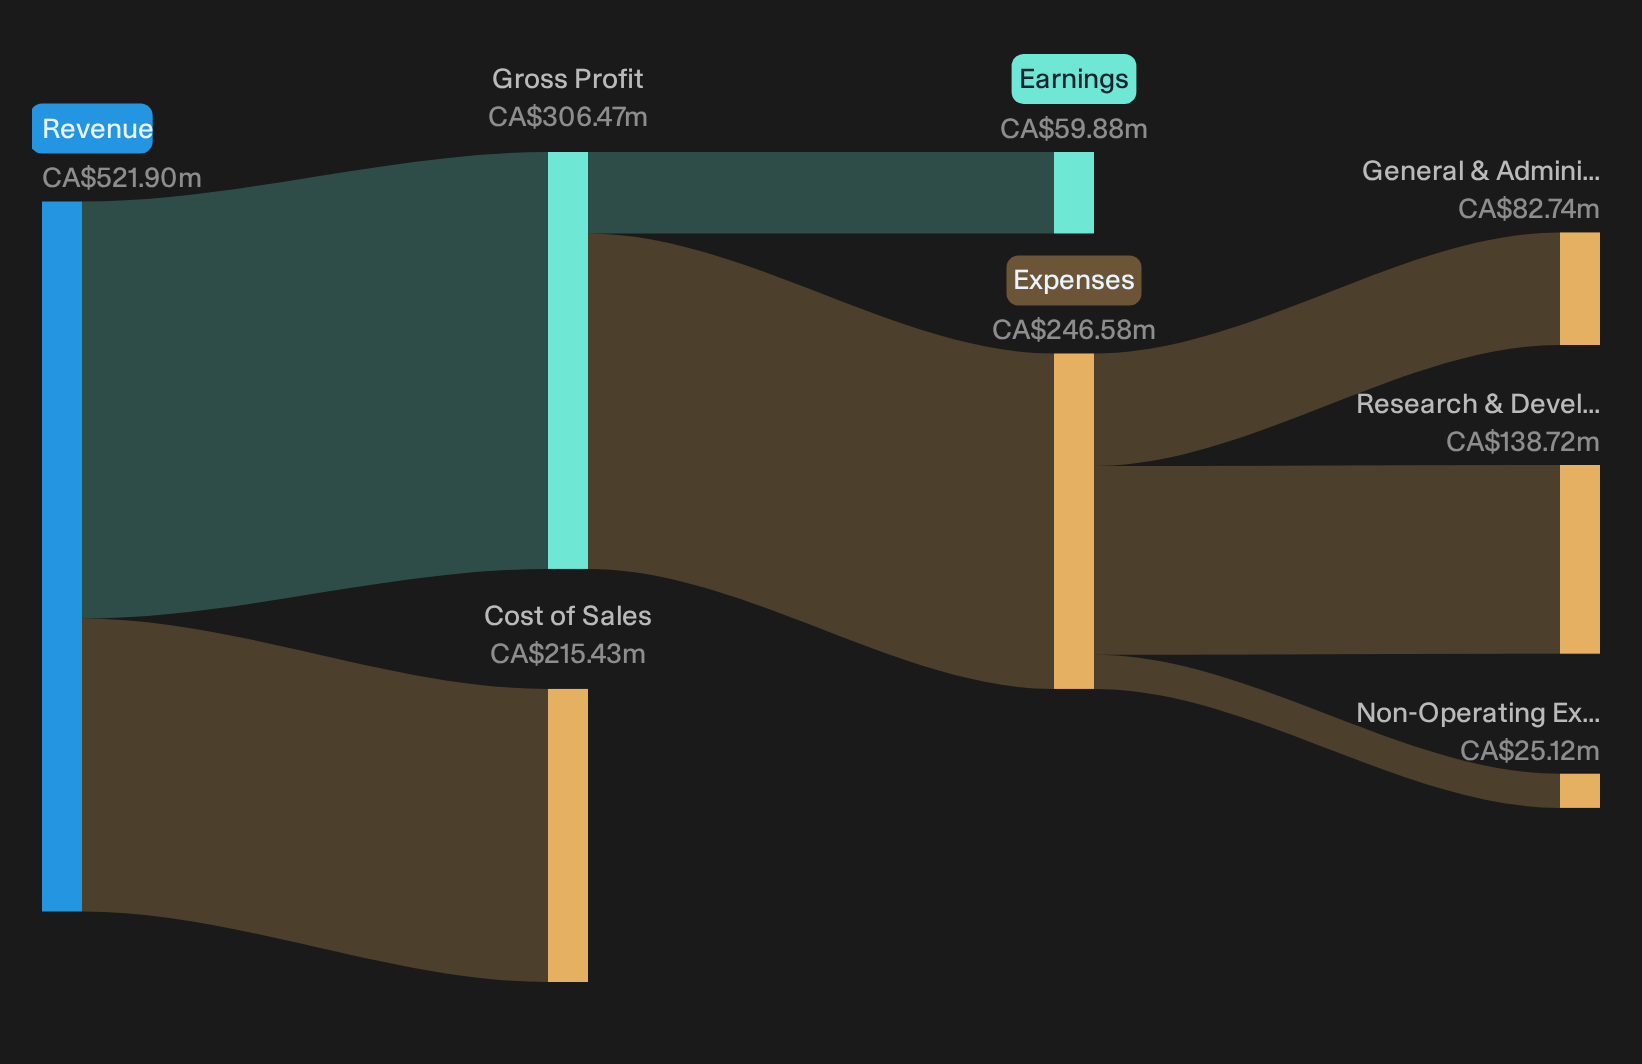
Evertz bullish thesis meets mixed execution
Bulls argue that Evertz Technologies is becoming a software and services powerhouse, with a thicker recurring base and a growing backlog keeping revenue steadier and more profitable. The latest quarter gives that view partial support. Software and services reached CA$58.9m, about 49.8% of sales, which fits the story of a business leaning harder into IP, cloud and subscription style contracts. International turnover climbed 17.5% to CA$38.3m and backlog plus August shipments now exceeds CA$289m, so the pipeline looks active across regions and customer types, including government and defense. Gross margin at 58.6% stayed inside the target band, which suggests pricing and product mix are holding up for now. Where the bullish script wobbles is earnings. Net income excluding extra items moved from CA$11.8m to CA$7.8m and EPS slipped to CA$0.10, so profitability is not yet tracking the stronger mix story.
Bear concerns on margins and cash find traction
The more cautious view is that hardware erosion, high R&D and customer concentration will squeeze Evertz profitability and strain cash even if revenue holds. Recent numbers give that argument real footing. Hardware slipped from CA$60.5m to CA$59.3m while software and services rose, yet net income excluding extra items still moved down about one third and basic EPS fell from CA$0.16 to CA$0.10. That points to pressure from elevated R&D at CA$38.5m, or 32.5% of sales, which is a heavy expense load for modest 5.5% top line growth. Cash net of bank debt dropped to CA$2.5m from CA$19.1m, largely because inventories expanded by roughly CA$20m and dividends reached about CA$15.5m. Management describes the backlog as broad based, which tempers fears of a single outsized client, but the hit to cash and the thinner earnings base both support a more cautious stance.
After a quarter where earnings softened, cash fell and dividends leaned on a thinner profit base, it is fair to ask whether these visible issues are the whole story or just the first cracks. Review the independent risk scoring work already done on Evertz Technologies and scan for other structural warning signs in our risk analysis for Evertz Technologies which shows 2 important warning signs.Stay Ahead Of Your Next Move
If the mix of softer earnings, higher R&D and a 22% pullback has put Evertz Technologies on your radar, register for free with Simply Wall St and add it to a Watchlist to track share price against fair value and watch for a more attractive entry point. Once you decide to build a position, keep a clear view of the bigger picture by using the Portfolio Command Center that filters out background noise and highlights the updates that matter. For longer term decisions, tap into crowd thinking and see how other investors are reacting through the Community to spot shifting sentiment and new angles you may have missed. By surfacing hidden catalysts and risks early, you give yourself a better chance of staying ahead of the market move rather than reacting to it after the fact.
Seeking Alternatives Beyond Evertz Technologies?
Fresh ideas move fast. Some stocks are building quiet momentum, others are dropping into attractive territory. Scan curated lists before the crowd catches on, while it matters, and get in early.
- Spot strong balance sheets before they start flying by sifting through a curated list of solid balance sheet and fundamentals stocks (7 results) that filters for quality, resilience and cleaner fundamentals.
- Ride early AI momentum while valuations still look reasonable by scanning 75 profitable AI stocks that aren't just burning cash built around companies already producing real earnings instead of just burning cash.
- Target income ideas that aim to keep paying you while markets move by reviewing 2 dividend fortresses focused on higher yielding businesses with sturdier profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com