
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Leidos Holdings (LDOS) Below Fair Value After $875m Navy Win?
Leidos Holdings has seen its share price move around in recent months, and that leaves a clear question for investors who care about fundamentals. Is the current US$129.24 price tag adequately explained by the earnings power of the business today?
- Over the past 5 years the stock has gained 51.6%, which puts real weight on whether the underlying earnings profile can justify where the valuation now sits.
- Fresh contract wins with the U.S. Navy, including an US$875m award tied to network management and secure connectivity, may support expectations for future profit streams and cash generation from Leidos' defense and technology work.
- The analysts covering Leidos Holdings have run their own numbers. See what analysts think Leidos Holdings's shares could be worth.
The issue now is whether the earnings that Leidos Holdings produces, and is expected to produce, are enough to make today's share price look sensible when judged against those profits.
Alongside evaluating Leidos Holdings based on its earnings, you can also scan a wider field of defense and technology plays using 11 resilient stocks with low risk scores.
Does Leidos Holdings Look Undervalued on Earnings?
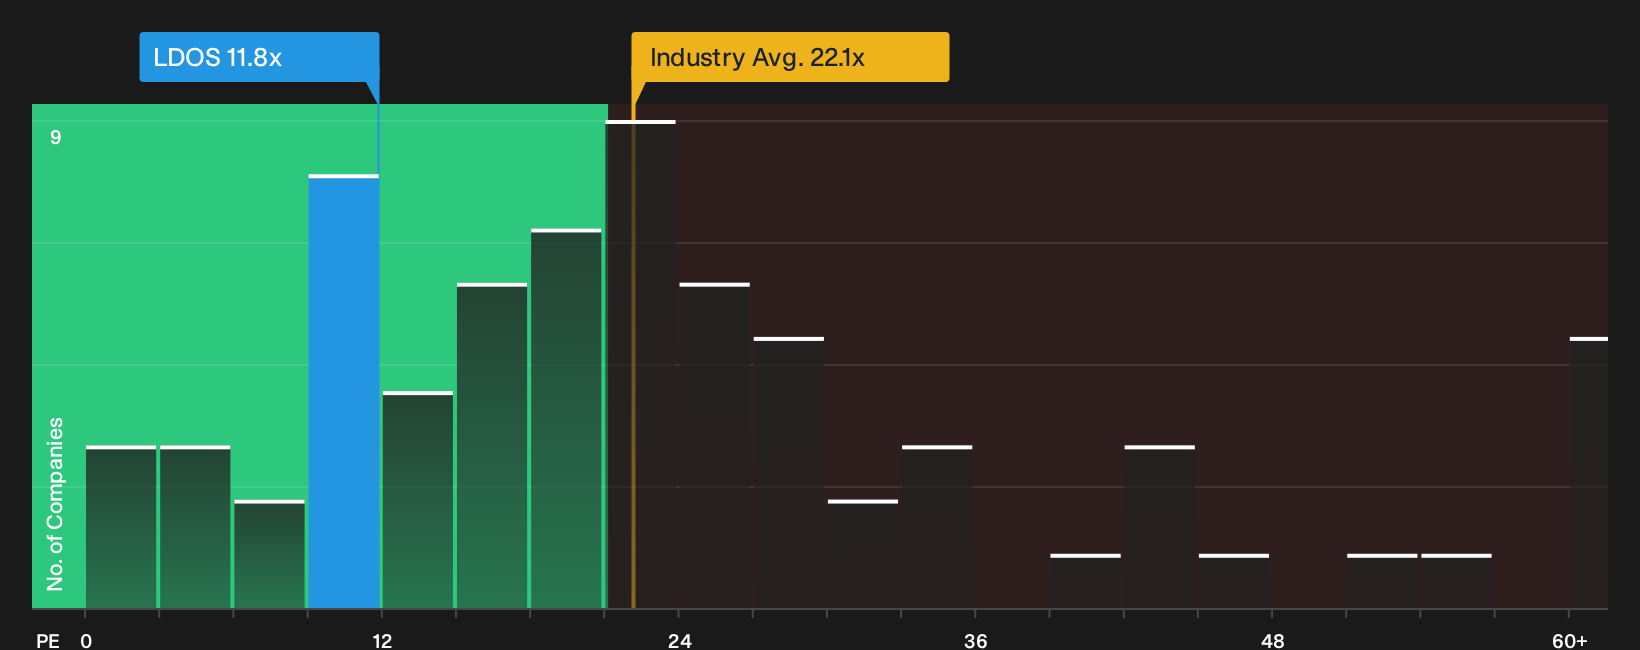
The P/E ratio is a useful reference point for Leidos Holdings because earnings remain central to how investors assess its performance and contract pipeline. At about 11.8x current earnings, the stock trades well below the wider Professional Services sector at around 22.1x, and also below the broader peer group near 30.4x.
That gap appears even wider when compared to the multiple implied by a more tailored fair-value framework, which indicates a higher P/E than where Leidos currently trades. Because the recent US$875m Navy contract underpins expectations that the business will continue converting its defense and technology work into profits, the discount on the P/E ratio suggests the market is pricing Leidos cautiously relative to those earnings. Explore the numbers behind Leidos Holdings's P/E valuation.
The Leidos Holdings Narrative: What Would Justify Today's Price?
Narratives for Leidos Holdings on Simply Wall St's Community page extend this valuation puzzle by spelling out which combinations of future growth, profitability and earnings paths would need to play out for the shares to be worth materially more or less than they are today. Each scenario ties a fair value estimate to a specific view of Leidos Holdings' potential catalysts and key risks, allowing you to track over time which storyline is actually taking shape in the real world.
Community sentiment on Leidos Holdings splits into those who see more upside in the current setup and those who view it as closer to fully priced.
Bull case: 17% undervalued
"The business mix is shifting towards recurring, service-based and software-driven revenue streams, enhancing earnings visibility and stability..."
Discover why this Narrative puts Leidos Holdings at 17% undervalued.
Bear case: roughly fairly valued
"Although the company has a large and growing cyber and digital infrastructure pipeline, government buyers may reprioritize or delay awards, which could constrain conversion..."
Explore why this Narrative puts Leidos Holdings at roughly fairly valued.
Before acting on Leidos Holdings' valuation, check who is steering the ship
Price multiples only tell part of the story, because the people making capital allocation calls and how they are rewarded can pull results in very different directions. See who runs Leidos Holdings and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com