
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
TD SYNNEX (SNX) Gains AI Distribution Exposure, Is The Stock Still Undervalued?
Hammerhead AI’s new collaboration naming TD SYNNEX (SNX) as distributor for its ORCA software puts the stock in focus, linking the IT distributor directly to power-efficient AI data center deployments.
Against that backdrop, TD SYNNEX’s recent collaboration news lands at a time when the stock has pulled back over the past quarter, with the 90-day share price return down 7.5% even as the year-to-date share price return sits at 71.1% and the 3-year total shareholder return reaches 167.8%. This suggests that longer term holders have experienced strong gains while short term momentum has cooled.
Spot under-the-radar AI infrastructure plays that are moving on similar power-efficiency themes as TD SYNNEX by scanning our curated list of 60 AI infrastructure stocks.After a 7.5% pullback leaves TD SYNNEX trading below both analyst targets and some intrinsic value estimates, the gap between price and fair value has widened. How far does that spread really run from here?
Most Popular Narrative: 21% Undervalued
Against TD SYNNEX’s last close at $262.48, the most followed narrative framework points to a higher fair value of $333.55, framing the recent pullback as a widening gap between price and long run AI and data center exposure.
The continued enterprise-wide digital transformation and AI adoption, highlighted by double-digit growth in software (especially in cloud, cybersecurity, virtualization, and infrastructure software), is extending TD SYNNEX's addressable market and generating higher recurring revenue streams that are expected to support consistent revenue and margin expansion.
Ongoing data center build-outs and the proliferation of hybrid/cloud IT infrastructure, as evidenced by high growth in the Advanced Solutions and Hyve businesses, are increasing demand for complex integration and lifecycle services. These trends support improved net margins through higher-value offerings.
See why 23 investors see TD SYNNEX as 21% undervalued.
Result: Fair Value of $333.55 (UNDERVALUED)
Still, the TD SYNNEX story can wobble if Hyve’s largest customer pulls back or if component shortages and pricing pressure squeeze already thin margins.
Find out about the key risks to this TD SYNNEX narrative.
Another View On TD SYNNEX Valuation
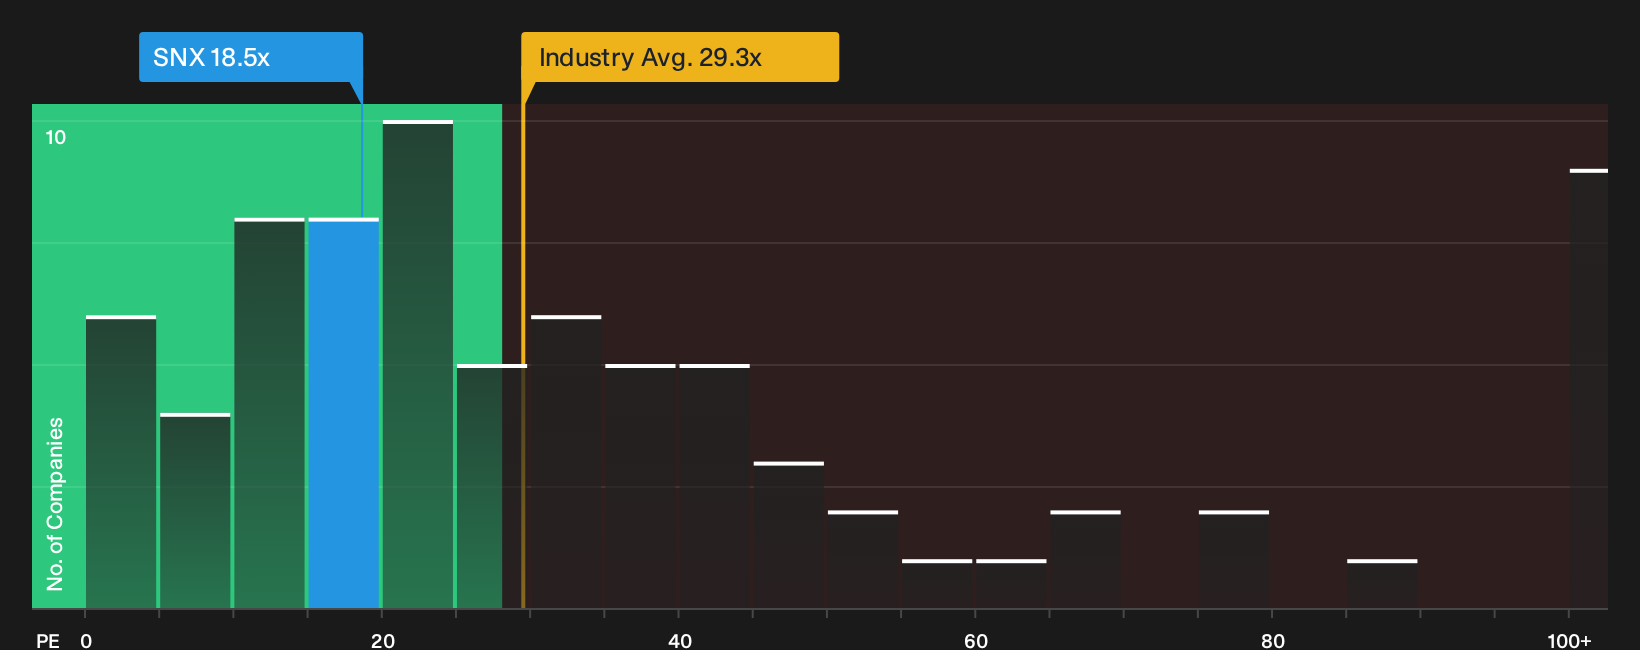
On earnings multiples, TD SYNNEX looks less clear cut. The shares trade on a P/E of 18.5x, slightly above the peer average of 17x, yet below the US Electronic industry at 28.9x and well under an estimated fair ratio of 26.6x. That mix of premium and discount raises a simple question: Is the market underpricing the quality of these earnings or already baking in plenty of good news?
For a closer look at how this earnings multiple could shift if expectations change, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around TD SYNNEX valuations and AI exposure only matter if you test them against your own risk tolerance and time horizon. Move quickly, review the full picture, and weigh both sides through 4 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond TD SYNNEX?
If TD SYNNEX has sharpened your focus on quality and valuation, do not stop here. Broaden your watchlist with ideas that target different risk and income profiles.
- Target resilient cash generators by screening for companies with robust finances through our list of solid balance sheet and fundamentals (23 results).
- Hunt for pricing gaps where quality and valuation align using the 35 high quality undervalued stocks.
- Build a stream of potential income ideas by scanning the 6 dividend fortresses and see which payouts might fit your long term plan.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com