
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Rambus (RMBS) Undervalued After Its CryptoManager Root Of Trust Launch?
Rambus (RMBS) has put security back in focus after launching its CryptoManager Root of Trust with support for the open-source Caliptra specification, targeting mission-critical data center and AI semiconductor deployments.
Rambus shares trade at US$83.11 after a 3.38% 1 day share price gain, yet the stock is still down 17.59% over 30 days and 36.12% over 90 days. Over a 1 year period, total shareholder return has declined 14.36%, while the 5 year total shareholder return has risen 264.68%, so recent momentum has cooled even as the longer track record remains strong.
Scan beyond Rambus and compare this security push with other chip and infrastructure players by reviewing the 60 AI infrastructure stocks in the same AI and data center theme.
Rambus now sits in an awkward middle ground after the security launch and sharp pullback. Has the recent slide reset the risk reward, or is the stock still priced for a richer future than the numbers support?
Most Popular Narrative: 44% Undervalued
Against Rambus' last close at $83.11, the most widely followed narrative anchors fair value at $149. This frames the recent pullback as a potential valuation gap rather than just a sentiment swing.
The analysts have a consensus price target of $149.0 for Rambus based on their expectations of its future earnings growth, profit margins and other risk factors. However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $180.0, and the most bearish reporting a price target of just $100.0.
See why 32 investors see Rambus as 44% undervalued.
The prevailing narrative leans on a discount rate of 11.02% and a fair value of $149, which is materially above the current market capitalization of about $8.7b at $83.11 per share. That gap, roughly 44% above the trading price, reflects models that factor in forecast earnings growth of 24.2% a year and revenue growth of 15.3% a year, alongside an assumed profit margin profile of just over 36%.
Analysts in that narrative framework also build in a future P/E of about 53x on projected 2029 earnings. This is framed as slightly below the current semiconductor sector multiple cited in the narrative, yet above Rambus' present valuation ratios. For investors, the key question is whether the underlying assumptions on AI and data center demand, DDR5 and MRDIMM adoption, and licensing momentum feel realistic enough to support that higher multiple over time.
Result: Fair Value of $149 (UNDERVALUED)
Still, if DDR5 adoption or newer companion chips underwhelm, or if competition squeezes Rambus licensing economics, that 44% upside narrative could unravel quickly.
Find out about the key risks to this Rambus narrative.
Another View on Rambus Valuation
There is a very different story when you look at Rambus through the SWS DCF model. On that measure, the shares at $83.11 trade well above an estimated future cash flow value of $32.70, which screens as overvalued and raises the question of which yardstick investors should trust.
For readers who want to see how that cash flow based figure is built step by step, Look into how the SWS DCF model arrives at its fair value.
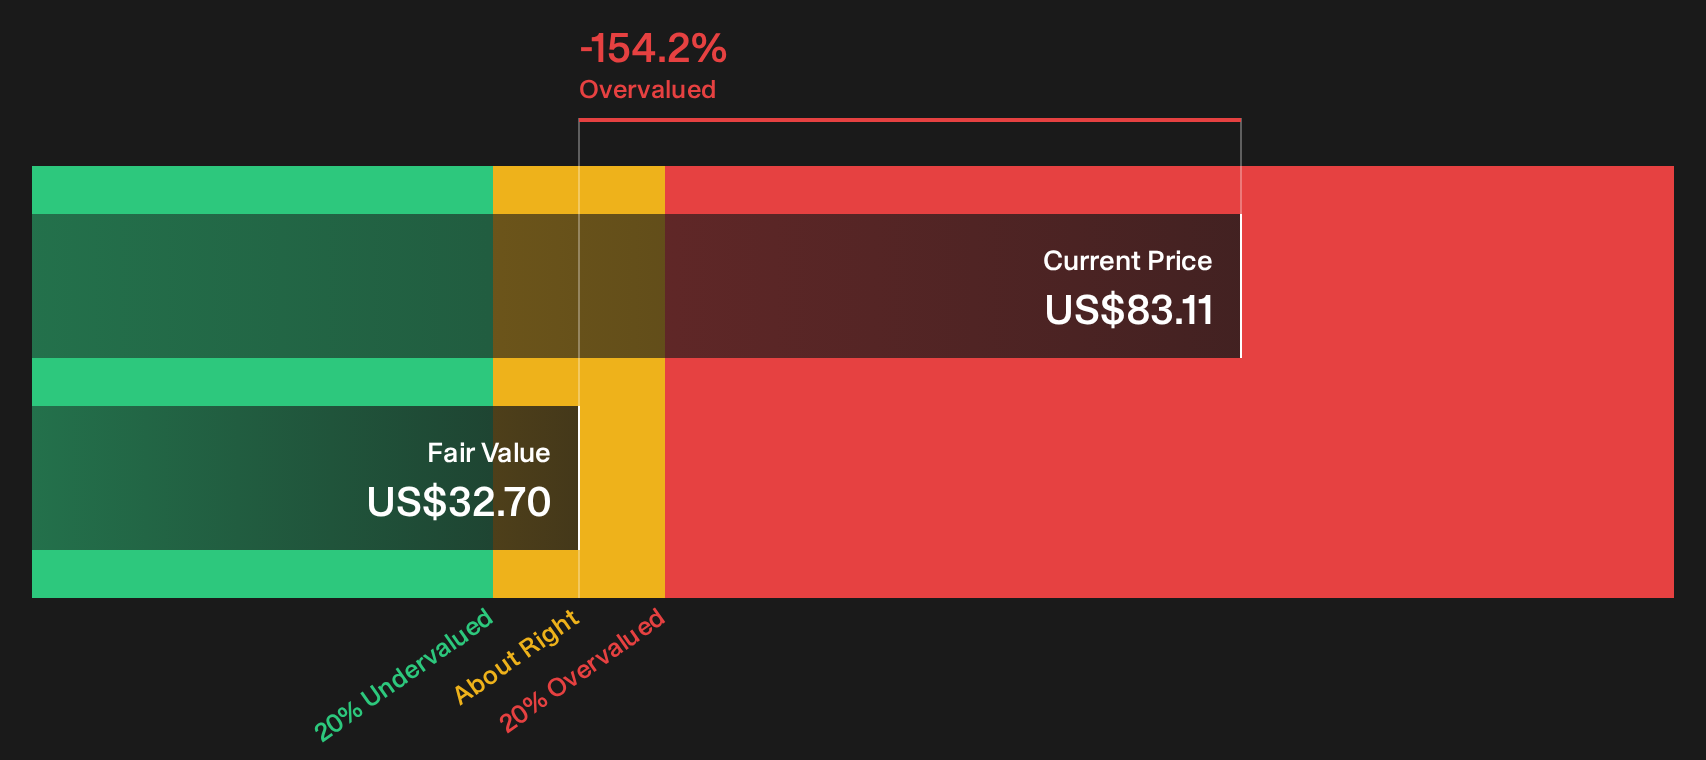
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Rambus for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Rambus is split, and the clock is ticking for you to weigh both sides of the argument using the same data. To stress test your own view against the current risk reward mix, start by reviewing the 3 key rewards and 1 important warning sign
Looking for more Rambus sized investment ideas?
If Rambus has sharpened your thinking on AI infrastructure, do not stop here. Broader opportunity sits across other themes, sectors and balance sheet profiles.
- Target resilient potential by reviewing companies in the 11 resilient stocks with low risk scores that align with your comfort for volatility and capital preservation.
- Hunt for pricing dislocations using the 35 high quality undervalued stocks to find stocks where fundamentals and market expectations currently appear out of sync.
- Anchor your portfolio with income ideas by scanning the 6 dividend fortresses that combine higher yields with a focus on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com