
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Taiwan Semi Revenue Keeps Surging. How to Play TSM Stock in September 2026.
The world’s largest semiconductor foundry, Taiwan Semiconductor (TSM), is experiencing swelling demand for its chips used in artificial intelligence (AI) operations. In August, Taiwan Semiconductor’s net revenue rose 53% year-over-year (YOY) and climbed 10% month-over-month to NT$514.81 billion. This marked the fourth-straight month the company reported a monthly revenue increase. From January to August, net revenue rose more than 39% YOY to NT$3.39 trillion.
Taiwan Semiconductor, also known as TSMC, is largely maintaining its industry-leading position in the chip foundry market. Its 5-nanometer, 4nm, and 3nm technology nodes remained fully booked in the most recent quarter, demonstrating robust demand. However, TSMC may also face headwinds next year in the form of price increases; Taiwan Semiconductor is reportedly looking to increase its chipmaking prices by up to 10% in 2027 to offset rising costs.
Still, TSMC’s demand is too big to ignore, making TSM stock a potentially solid buy right now. Let's take a closer look.
About Taiwan Semiconductor Stock
Taiwan Semiconductor is the world’s largest dedicated semiconductor foundry, fabricating advanced chips for a broad range of tech customers. It specializes in cutting-edge process nodes that supply processors for smartphones, high-performance computing (HPC), data centers, and other electronic devices, while continuing to invest in next-generation manufacturing technology and expand global production capacity. Headquartered in Hsinchu, Taiwan, TSMC commands a market capitalization of approximately $2.2 trillion, underscoring its dominant position in the global semiconductor supply chain.
TSMC has been a prime beneficiary of the AI infrastructure boom, with surging demand for its most advanced chips driving record revenue, expanding margins, and aggressive capacity expansion. Over the past 52 weeks, TSM stock has gained 58%, and shares are up 36% year-to-date (YTD). TSM stock reached a 52-week high of $479 on June 30 but is currently down roughly 14% from that level.
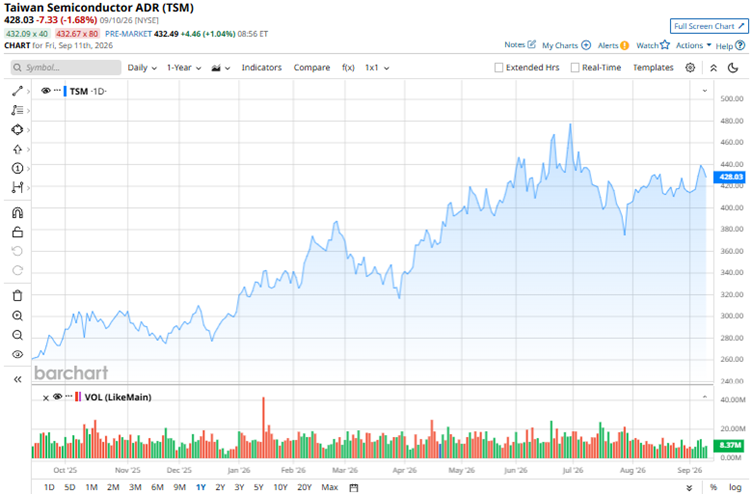
Despite the rise this year, TSM stock trades at a relatively cheap valuation. On a forward-adjusted basis, its price-to-earnings (P/E) ratio of 26.1 times is lower than the industry average of about 28 times.
TSMC Reports Q2 Results
Supported by strong demand for its leading-edge process technologies, TSMC reported strong results in the second quarter of 2026. Revenue rose by a robust 36% YOY to NT$1.27 trillion, while operating margin grew from 49.6% to 60.3%. Earnings per ADR unit grew from $2.47 in Q2 2025 to $4.31 in Q2 2026.
Meanwhile, 3nm, 5nm, and 7nm nodes accounted for 30%, 33%, and 11% of total wafer revenue, respectively. Advanced technologies (7nm and below) reportedly accounted for 77%. Moreover, HPC accounted for 66% of net revenue.
Wall Street analysts are optimistic about TSMC’s future earnings. Analysts expect EPS to climb 52% YOY to $4.45 in Q3 2026. For fiscal 2026, EPS is projected to surge 55% to $16.55, followed by 28% growth to $21.20 in fiscal 2027.
What Do Analysts Think About Taiwan Semiconductor Stock?
Back in July, DA Davidson maintained a “Buy” rating on TSM stock and raised its price target to $500, reflecting confidence in the company’s position and performance as the leading chip manufacturer. Likewise, Needham raised its price target for TSMC from $480 to $530 while maintaining a “Buy” rating.
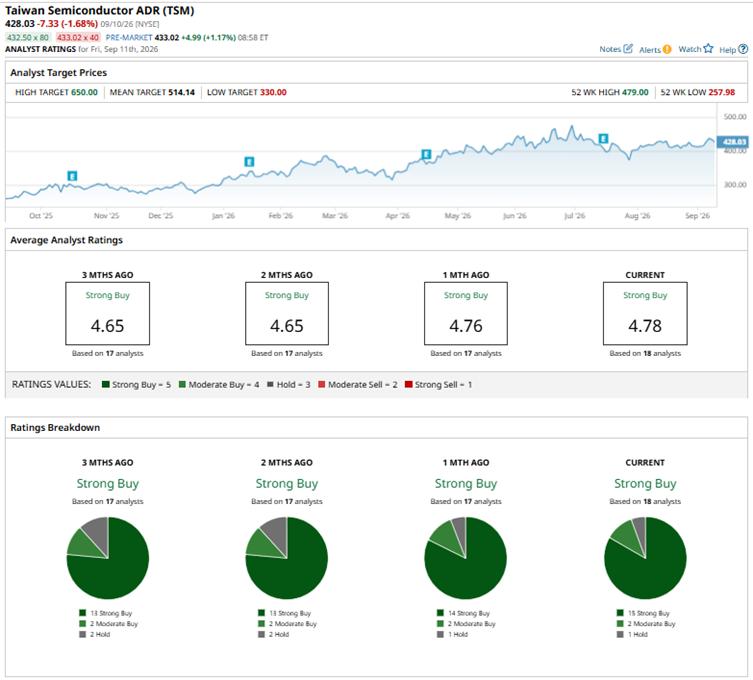
Overall, Taiwan Semiconductor has been in the spotlight on Wall Street, with analysts awarding it a consensus “Strong Buy” rating. Of the 18 analysts rating the stock, 15 analysts have a “Strong Buy,” two analysts suggest a “Moderate Buy,” and one analyst has a “Hold” rating. The average price target of $514.14 represents potential upside of 24% from current levels, while the Street-high price target of $650 indicates 57% potential upside from here.
On the date of publication, Anushka Dutta did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.