
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Quarterly Loss Change PVH (PVH) Narrative
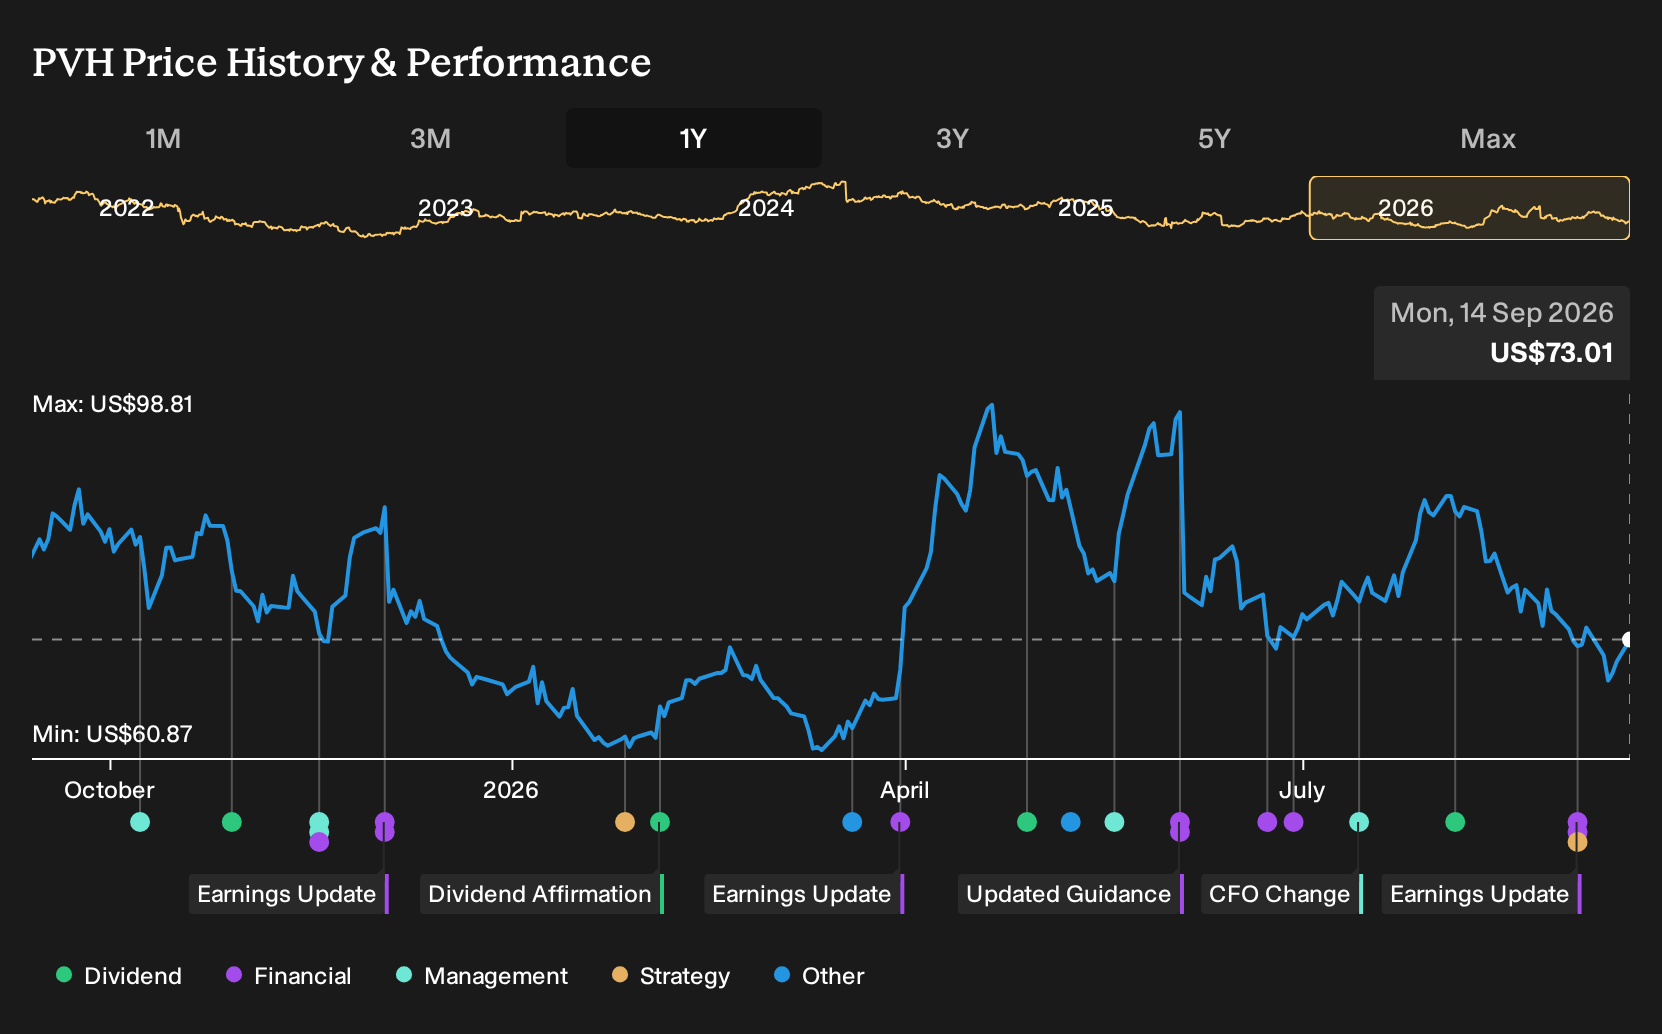
- PVH reported second quarter 2026 sales of US$2,097 million and a net loss of US$102.9 million, driven in part by US$439 million of goodwill and intangible asset impairments. The company reaffirmed full year guidance that calls for roughly flat revenue and an 8.8% operating margin.
- The absence of share repurchases in the recent tranche period, after buying back more than 41 million shares since 2015, highlights how current cash use now leans toward supporting operations through weaker demand and compressed profitability.
- We will now look at how PVH's investment narrative could shift in light of the fresh quarterly loss and large impairments.
PVH Investment Narrative Recap
To own PVH, you need to believe that management can turn solid brands into healthier cash generation while working through softer demand and operational complexity. The reaffirmed guide for roughly flat 2026 revenue and an 8.8% operating margin keeps that margin improvement story intact in the near term. The key short term catalyst remains execution on the PVH+ efficiency plan and cost discipline rather than top line acceleration.
The biggest current risk is that weak consumer appetite, especially in more challenged regions and channels, keeps volumes under pressure while tariffs and supply chain costs weigh on profitability. The US$439 million in impairments and the swing to a quarterly loss do not directly change that risk, but they underline how sensitive the business is to slower growth and brand concentration.
The most relevant recent announcement is PVH reaffirming full year 2026 guidance despite reporting a second quarter net loss of US$102.9 million and goodwill and intangible asset impairments of US$439 million. Management is still targeting an 8.8% operating margin on roughly flat revenue, which puts execution squarely in focus for anyone following the PVH story.
This guidance, paired with the absence of buybacks in the latest tranche, channels attention toward operational delivery, cash conversion, and consistency in Calvin Klein and Tommy Hilfiger performance. With analysts already cautious on constant currency revenue trends and return on equity, upcoming earnings updates and the September Goldman Sachs conference presentation are likely to be important checkpoints on whether those margin and EPS ambitions look achievable.
PVH's current analyst narrative points to revenues of US$9.6b and earnings of US$734.4 million by 2029. This outlook is built on an assumed 2.1% yearly revenue growth rate and an earnings increase of about US$576 million from current earnings of US$158.1 million.
Uncover why PVH's fair value indicates a 27% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on tariffs as the key risk for PVH. The most cautious analysts already assumed fairly flat revenue around US$9.0b and earnings of about US$683.2 million by 2029 before this latest loss and impairment. That cohort builds a more pessimistic story. Use the new earnings and the upcoming Goldman Sachs conference to test both narratives.
Explore 2 other PVH fair value estimates, including one that suggests it could be worth just $93.08!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your PVH research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for PVH. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PVH's overall financial health at a glance.
Looking For More Ideas Beyond PVH?
If PVH has sharpened your focus on balance sheets, cash generation, and risk, use that same lens to scan a broader universe of companies with the Simply Wall St Screener.
- For investors hunting for resilient businesses with lower risk profiles, start by reviewing 11 resilient stocks with low risk scores that may better match your comfort level.
- If income is your priority, consider screening for steady cash distributors through our curated 6 dividend fortresses that might offer more predictable payouts.
- Those searching for underappreciated opportunities can narrow the field quickly by filtering for 15 high quality undiscovered gems that combine solid fundamentals with limited market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com