
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
A $1 Billion Reason Why AXON Stock Is Down Today
Axon Enterprise (AXON) shares are slipping on Tuesday morning after the public safety tech firm announced plans for a $1 billion debt offering. In its press release, management said it wants to raise fresh capital by offering 0% convertible senior notes due in late 2031.
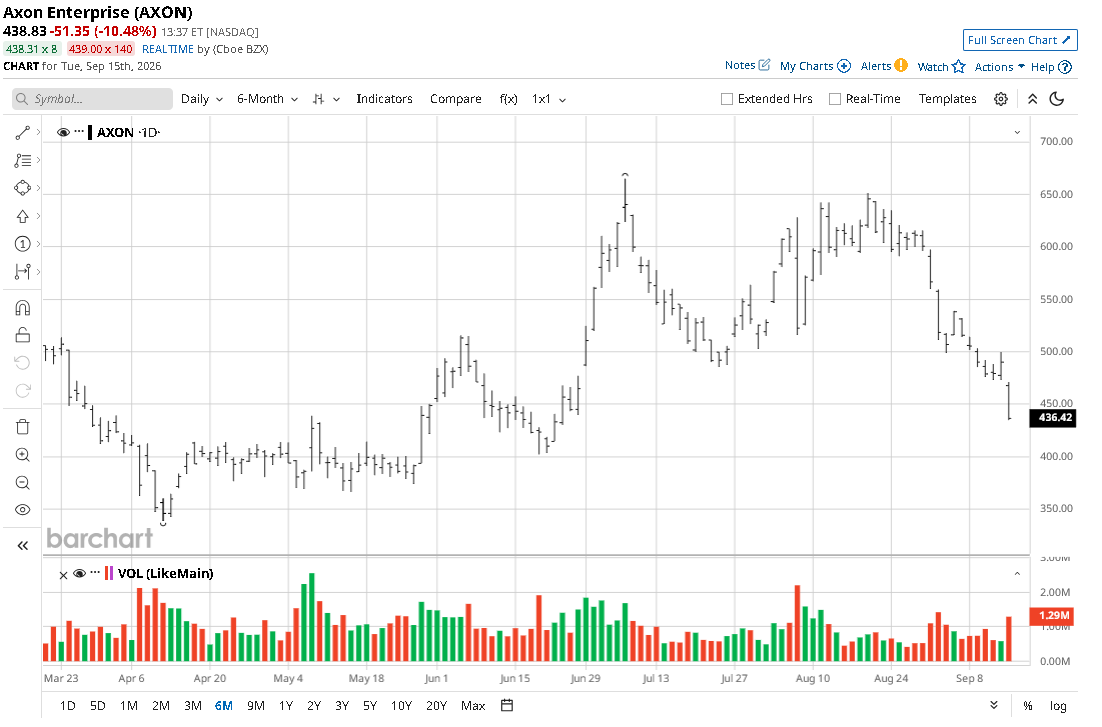
The announcement arrives as Axon stock has already fallen out of favor with investors, currently down about 30% versus its August high.
Why Does the Debt Offering Matter for Axon Stock?
Investors are bailing on AXON shares today primarily because of dilution concerns. While the 0% coupon prevents additional cash interest expenses, convertible notes still allow bondholders to exchange their debt for equity down the line, expanding the share count, which reduces the ownership of existing investors.
The debt offering is bearish for Axon Enterprise also because it highlights dwindling cash reserves. After peaking at about $1.7 billion in late 2025, the firm’s cash position declined below $700 million by mid-2026, prompting it to raise fresh capital to fund growth initiatives and maintain financial flexibility.
Should You Buy the Dip in AXON Shares?
Long-term investors may consider buying the dip in Axon shares today as the company maintains a strong competitive moat in body cameras, cloud software, and law enforcement hardware.
Last month, it reported market-beating financials for its fiscal Q2, featuring a 41% growth in future contracted bookings to $15.1 billion.
That said, caution is warranted in playing AXON given its premium valuation multiple. Even after the recent selloff, it’s trading at about 226x forward earnings, which makes it an expensive stock to own by any stretch of the imagination.
And it’s not like Axon Enterprise pays a healthy dividend to incentivize ownership despite the valuation concerns.
Wall Street’s View on Axon Enterprise
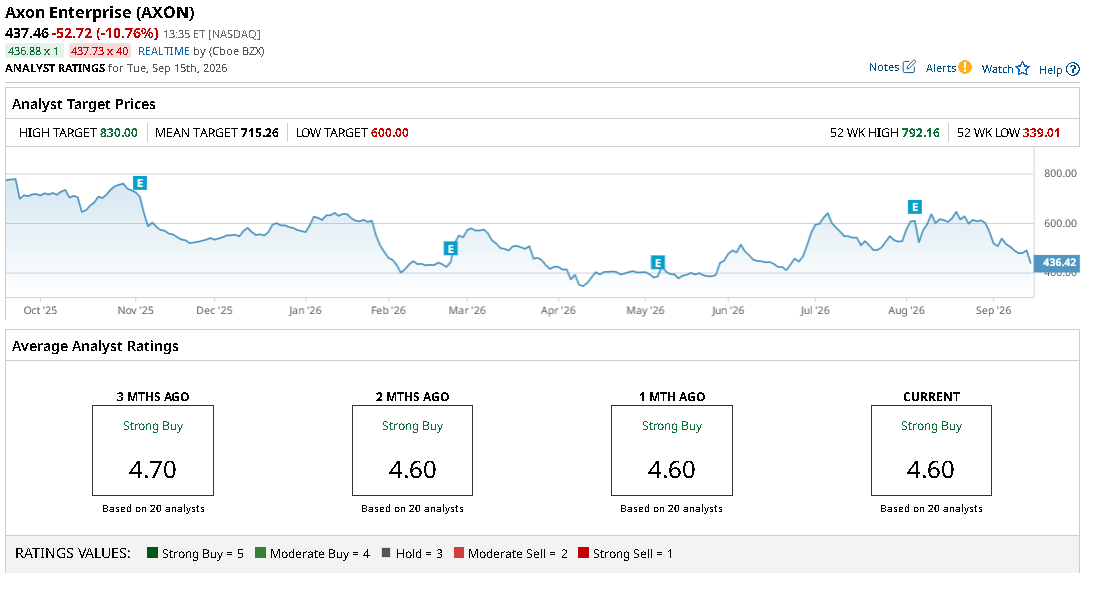
Crucially, Wall Street analysts recommend looking beyond the valuation risks and owning AXON stock for the longer term.
According to Barchart, the consensus rating on the Nasdaq-listed firm sits at “Strong Buy” currently, with the mean price objective of a whopping $715 indicating potential for another 40% rally from here.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.