
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
SM Energy Stock What Full Debt Payoff Means
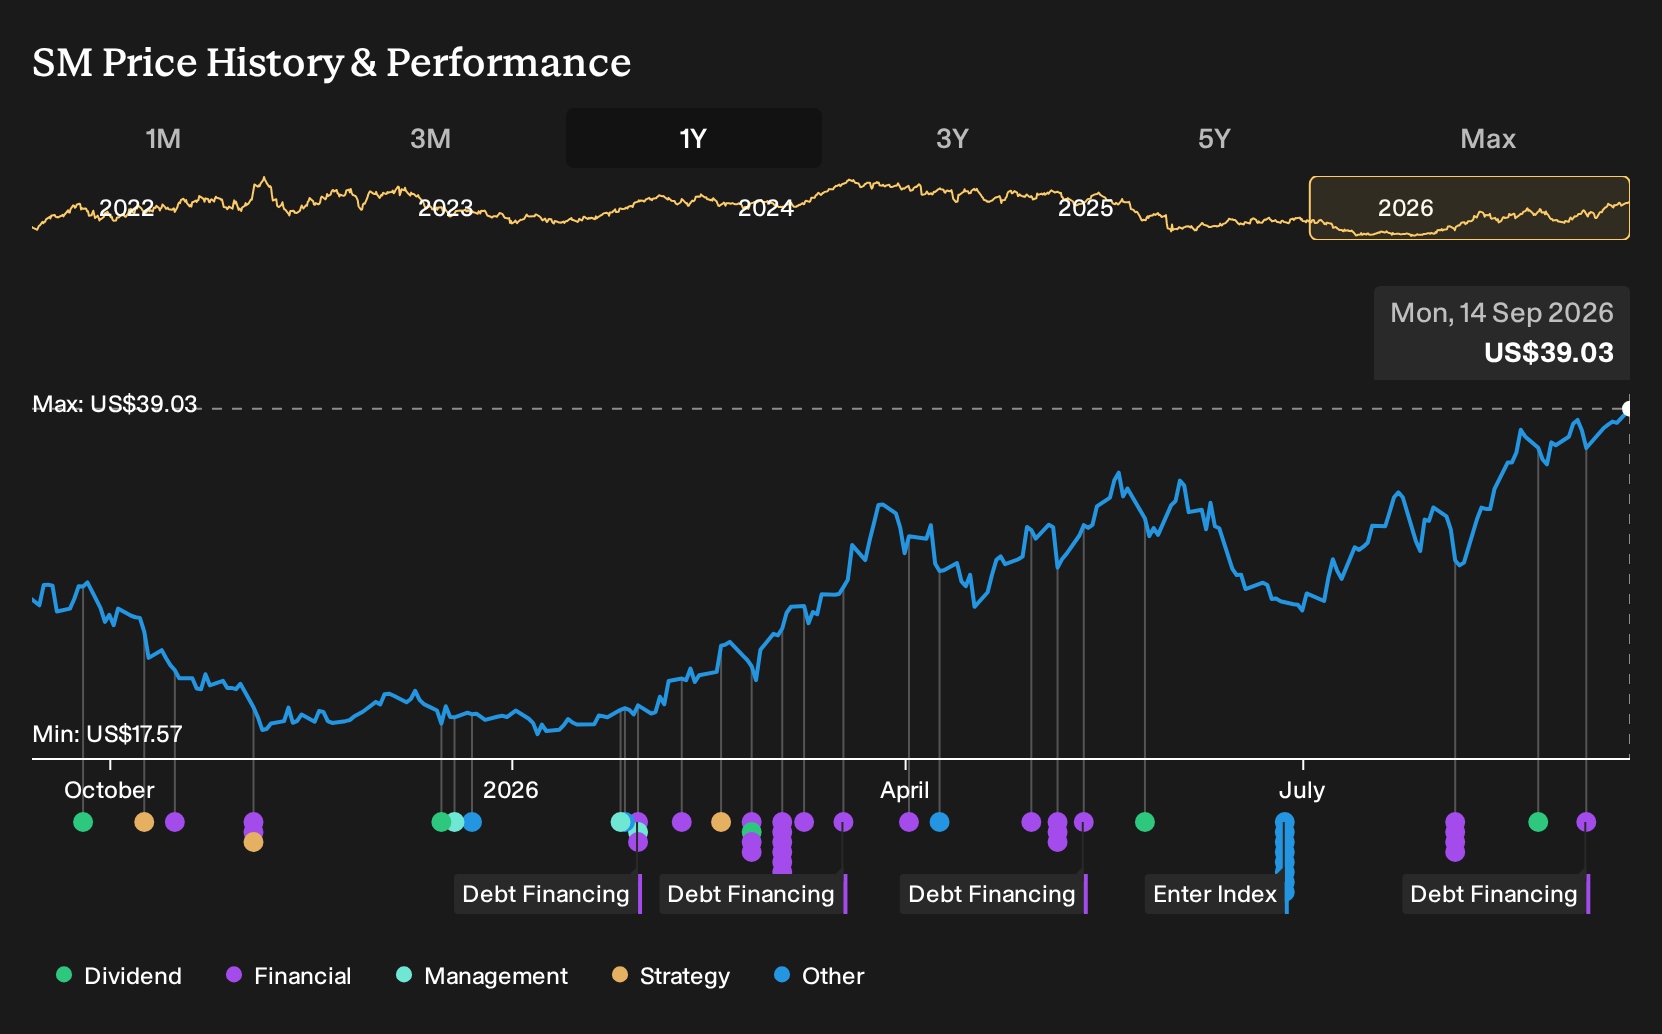
- SM Energy redeemed all of its 6.625% Senior Notes due 2027 on September 4, 2026, paying US$416,791,000 plus accrued interest and cancelling the notes and related guarantees.
- This full payoff removes a defined layer of interest-bearing debt and directly affects SM Energy's ongoing financing costs and balance sheet flexibility.
- We will look at how SM Energy's full redemption of its 2027 notes fits into the broader investment narrative around capital discipline.
Review our hand-picked list of solid balance sheet and fundamentals (23 results) to see how SM Energy’s clean-up of its 6.625% notes compares with peers that are focused on balance-sheet strength.
SM Energy Investment Narrative Recap
To own SM Energy, you really need to believe the business can keep turning its Uinta and Midland drilling inventory into consistent production and cash while managing shale decline rates and capital intensity. The full redemption of the 6.625% notes looks more like housekeeping than a change to near term operating momentum, so it does not materially shift the core thesis.
The short term swing factor still sits in execution on Uinta development, basis differentials, and well performance once inherited programs roll off. The biggest risk remains that sustaining volumes may require heavier spending just as regional pricing or regulations move against the company. That would pressure margins even with a cleaner balance sheet.
Among recent updates, the debt redemption itself is the key event to watch in the context of catalysts. Clearing the 2027 notes reduces one high coupon obligation and may free future room for drills, completions, or shareholder returns if commodity prices cooperate. However, the operational bar around reserves, costs, and uptime does not change.
Where this ties back to your thesis on SM Energy is through resilience. A business that already carries a high level of debt and relies fully on external funding benefits from simplifying its capital structure. Yet the share price will still likely respond more to drilling results, basis spreads, and capital spend discipline than to this one financing move.
What SM Energy’s Debt Move Means Against Analyst Expectations
SM Energy's narrative references forecast revenue of US$8.5b and projected earnings of US$2.1b by 2029, built on analysts' assumption of 19.5% yearly revenue growth and an earnings increase of about US$1.1b from current earnings of US$1.0b.
Discover why SM Energy's fair value indicates a 5% potential upside to its current price before the window for that discount becomes more limited.
Exploring Other Perspectives
For SM Energy, the alternate bullish view leans hard on a catalyst that sits right next to this debt clean up. Higher conviction analysts were already pencilling in about US$8.5b of revenue and US$2.3b of earnings by 2029, versus US$2.1b in the consensus case. Those projections were made before this redemption, so you may see views shift as analysts reassess balance sheet flexibility and how aggressively SM Energy might fund future projects. Use this as a prompt to compare different narratives, not a script to follow blindly.
Explore 6 other SM Energy fair value estimates, including one that suggests potential upside of up to 499% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your SM Energy research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for SM Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SM Energy's overall financial health at a glance.
Looking For More SM Energy Investment Ideas?
If SM Energy has prompted you to think harder about balance sheets, cash generation, and debt profiles, it can be useful to compare it with a wider set of companies and assess where the risk reward trade off feels more comfortable for you.
The Simply Wall St Screener lets you scan the market using the same kind of filters used here, then narrow in on the handful of stocks that actually deserve your attention.
- For investors who want potential upside but still care about financial strength, start with a curated 35 high quality undervalued stocks that combine quality fundamentals with attractive pricing.
- If capital preservation ranks high on your checklist, consider a 11 resilient stocks with low risk scores that score well on balance sheet resilience and business stability.
- When you are hunting for lesser known opportunities with cleaner fundamentals, filter through a 15 high quality undiscovered gems that might complement or even rival what you see in SM Energy.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com