
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Toyota Boshoku (TSE:3116) Draws Valuation Attention, Is The Stock A Bargain?
Toyota Boshoku (TSE:3116) drew fresh attention after its recent share price closed at ¥2,224, with the stock down over the past month and year, yet higher over the past 5 years.
Recent trading paints a mixed picture for Toyota Boshoku. The 1-year total shareholder return is down 8.39%, while the 5-year total shareholder return of 31.64% points to longer term investors still being in positive territory even as recent share price momentum has faded.
Scan beyond Toyota Boshoku and compare it with a curated 18 high quality undervalued stocks that combines solid cash flows with balance sheets many investors overlook.
Recent weakness in Toyota Boshoku shares contrasts with a solid multi year record, which leaves investors weighing a fresh entry against holding out for deeper weakness. So what does the current valuation actually suggest?
Price-to-Earnings of 18.7x for Toyota Boshoku: Is it justified?
Toyota Boshoku last closed at ¥2,224, and the stock trades on a P/E of 18.7x, which screens as expensive relative to both peers and its own fair ratio checks.
The P/E multiple compares the current share price with earnings per share and is a quick way to see how much investors are paying for each unit of profit. For an auto components group like Toyota Boshoku, this ratio often reflects what the market is willing to pay for current profitability and its future earnings profile.
On these metrics, the stock looks heavily priced. The current P/E of 18.7x is far higher than the JP Auto Components industry average of 9.6x and also above the estimated fair P/E of 16.1x. That combination suggests investors are paying a premium that the market could eventually re-rate toward the fair ratio level if sentiment or profit expectations shift.
Explore the SWS fair ratio for Toyota Boshoku.
Result: Price-to-Earnings of 18.7x (OVERVALUED)
Still, Toyota Boshoku faces clear risks, including a 1 year total return that declined 8.39% and a 3 year total return that fell 14.67%.
Find out about the key risks to this Toyota Boshoku narrative.
Another View on Toyota Boshoku’s Valuation
The P/E screen paints Toyota Boshoku as expensive, yet the SWS DCF model points the other way. At ¥2,224, the shares are indicated as trading about 57% below an estimated future cash flow value of ¥5,166.76. Which yardstick should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
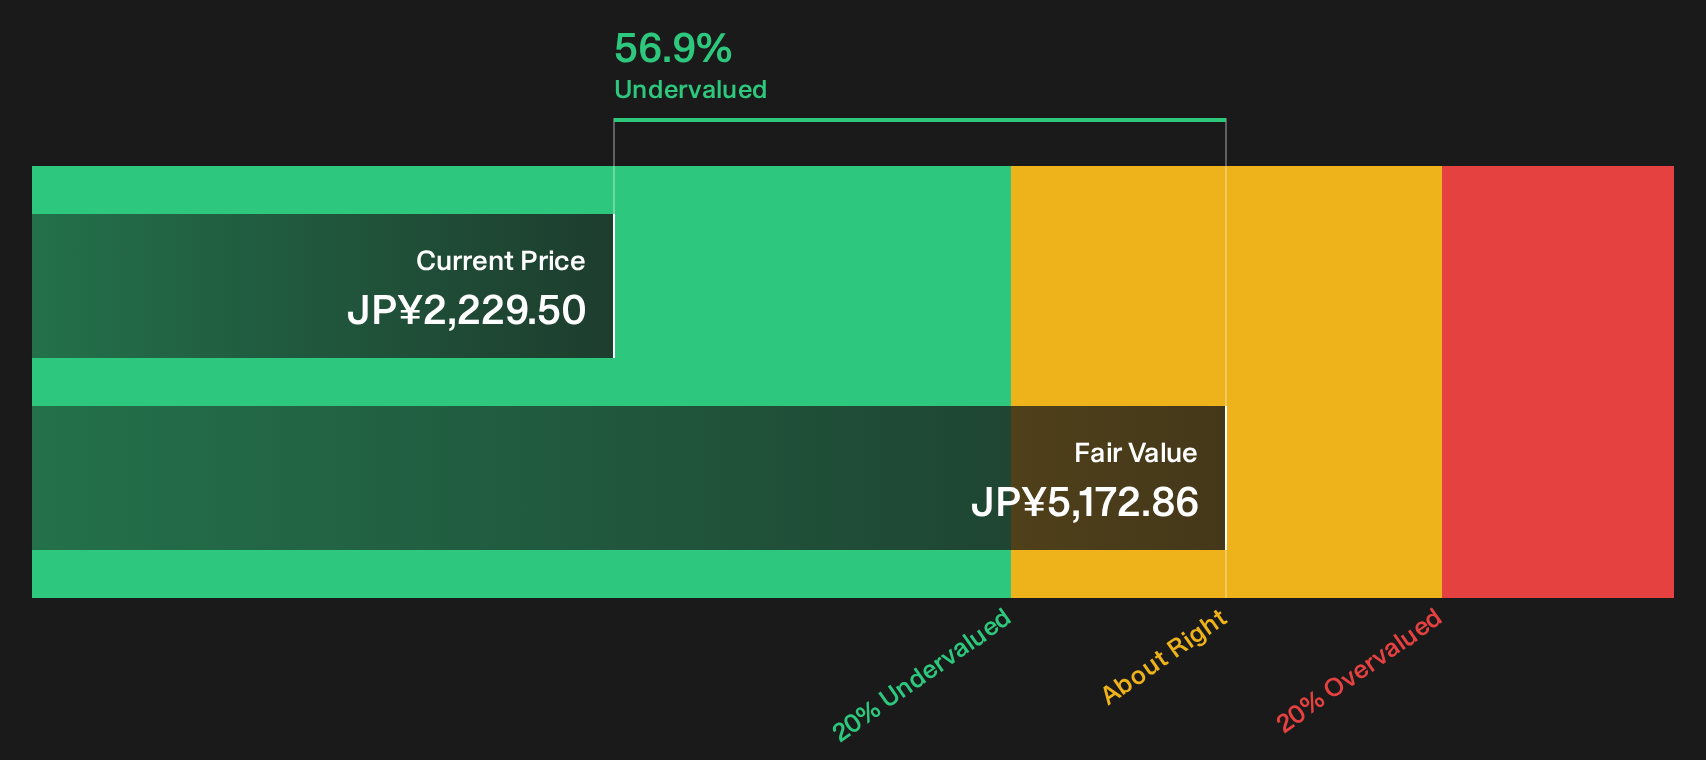
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Toyota Boshoku for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Toyota Boshoku can pull you in opposite directions, so move quickly, review the full picture and weigh both sides carefully using the 2 key rewards and 1 important warning sign.
Looking for more Toyota Boshoku style investment ideas?
If Toyota Boshoku has you thinking harder about valuation and risk, do not stop here. Use targeted screeners to surface fresh ideas before other investors move.
- Target potential upside in smaller companies by reviewing 1 elite penny stocks with strong financials that clear a high bar on financial strength.
- Prioritize quality at a discount by scanning the 74 high quality undiscovered gems with stronger fundamentals that many investors may not be watching yet.
- Focus on resilience first by checking the 12 resilient stocks with low risk scores that combine sturdier business profiles with lower assessed risk.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com