
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To State Street (STT) Leadership Reshuffle
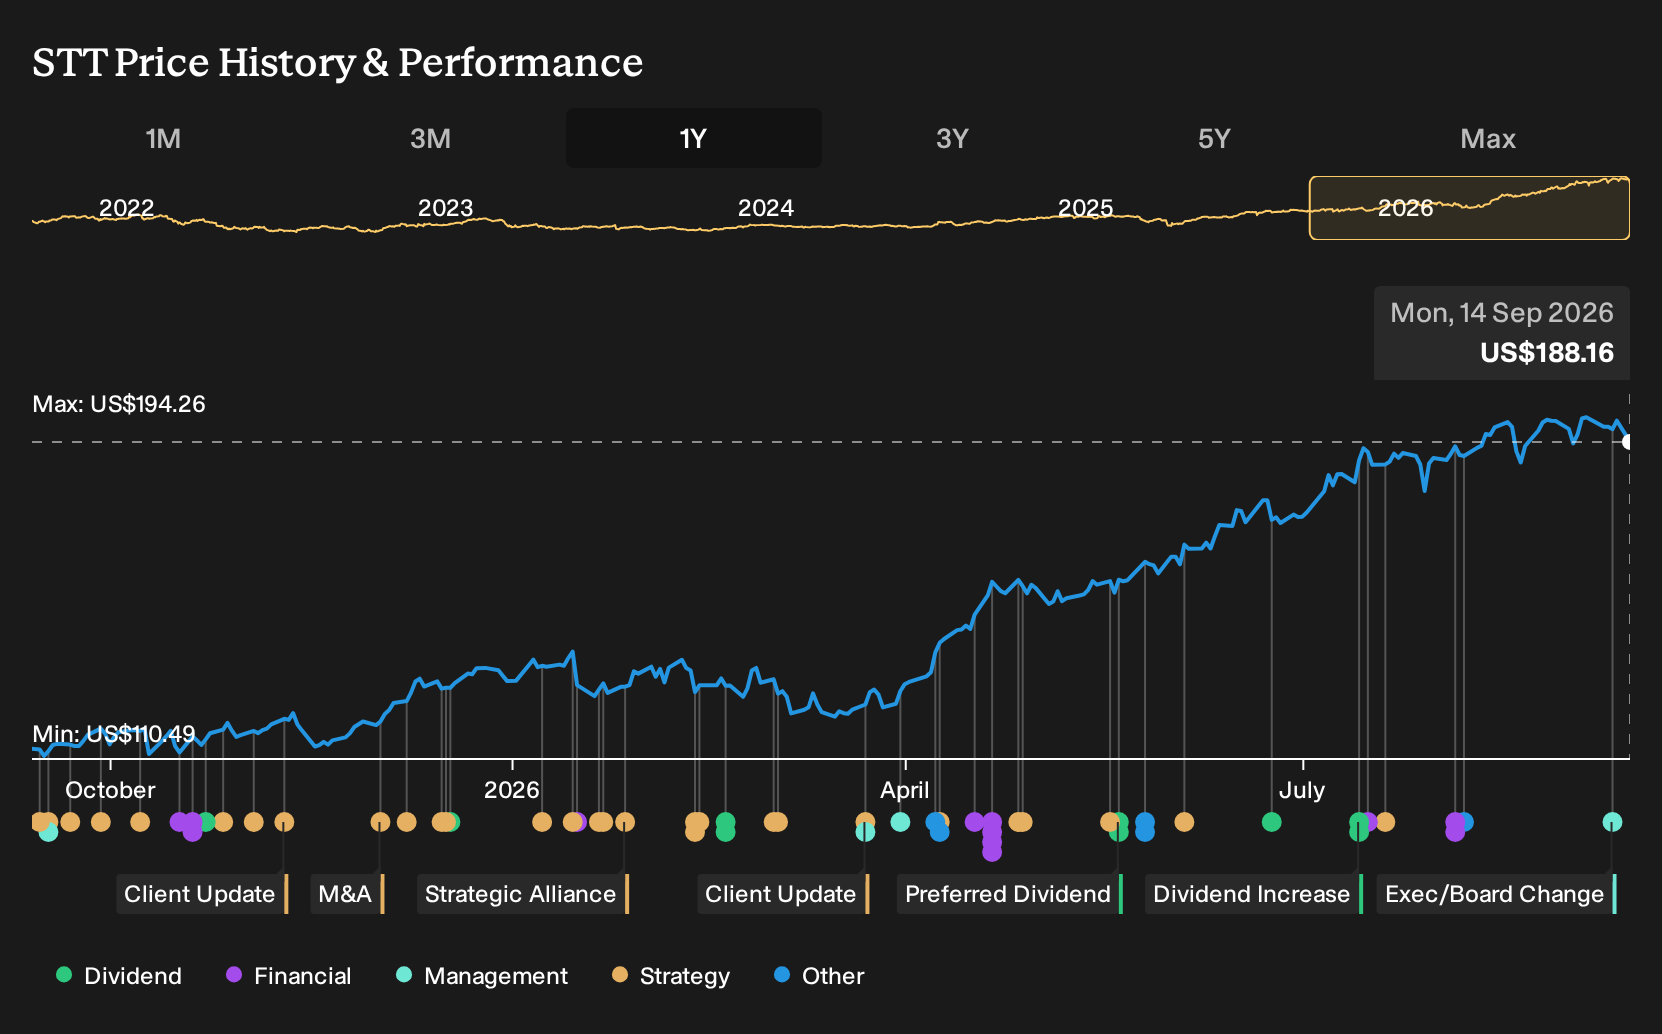
- State Street Corporation recently reshuffled senior leadership, naming Mostapha Tahiri president of State Street Alpha and Ann Fogarty enterprise chief operating officer, with both roles geared toward technology, AI, and end to end platform execution.
- This management shift concentrates accountability for the Alpha and Charles River Development platforms and enterprise operations. It sits directly on the fault line of rising client complexity, cost pressure, and demand for integrated data and servicing.
- We will look at how State Street's investment narrative evolves as leadership concentrates on Alpha platform execution and AI driven operations.
Scan how State Street is repositioning around platforms and AI, then broaden your watchlist with a curated set of 60 AI infrastructure stocks that could also benefit from this shift in client demand.
State Street Investment Narrative Recap
To own State Street, you need to believe the firm can keep turning its scale in custody, ETFs, and Alpha into steady fee growth while holding the line on costs. The biggest short term swing factor remains execution on technology and operations efficiency, especially as fee pressure and slower forecast revenue growth of 4.5% a year limit room for error.
The main risk is that competition from fintech and big tech platforms outpaces State Street’s own tech and AI push, which could squeeze margins and weaken its relevance in core servicing. The latest leadership reshuffle looks material because it directly targets that execution gap across Alpha, Charles River Development, and enterprise operations.
The appointment of Mostapha Tahiri as president of State Street Alpha is the announcement that most directly ties to today’s narrative. He now owns end to end responsibility for Alpha and Charles River Development across product, go to market, technology, and client delivery, and that concentration of authority could matter for how quickly the platform responds to complex client demands.
For catalysts, investors are watching whether Alpha and broader technology spending translate into more scalable servicing, lower cycle times, and better data driven solutions that support fee resilience. Execution risk stays high because missed delivery on AI and modernization would leave State Street more exposed to fee compression, regulatory costs, and new settlement technologies such as blockchain and tokenization.
State Street's narrative projects US$17.5b revenue and US$4.7b earnings by 2029. This implies 5.3% yearly revenue growth and an earnings increase of about US$1.5b from US$3.2b today.
Uncover why State Street's fair value indicates a 6% potential upside to its current price that may not remain available for long.
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into Alpha as a growth engine. They were already penciling in US$18.4b of revenue and US$4.9b of earnings by 2029, compared with the baseline US$17.5b and US$4.7b. You can treat today’s leadership changes at State Street as a fresh test of which narrative proves closer to reality.
Explore 2 other State Street fair value estimates, including one that indicates there could be up to 14% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your State Street research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for State Street. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate State Street's overall financial health at a glance.
Looking for more investment ideas beyond State Street?
Once you have a view on State Street, it can help to stress test your thesis by comparing it with other businesses that offer different mixes of quality, risk, and income potential using the Simply Wall St Screener.
- If you care most about valuation and fundamentals, scan a curated set of 35 high quality undervalued stocks that combine stronger balance sheets and cash flows with prices that screens suggest may be below intrinsic value.
- If capital preservation ranks higher for you than chasing maximum upside, filter the market for 11 resilient stocks with low risk scores that score well on financial health and earnings stability.
- If you want a mix of quality and income, focus on resilient payers in the 6 dividend fortresses that aim to pair higher yields with more robust fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com