
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Regeneron Pharmaceuticals (REGN) Still Undervalued After The Class Action Lawsuits?
Why the Regeneron Pharmaceuticals lawsuits matter for investors
Regeneron Pharmaceuticals (REGN) is under pressure after multiple law firms launched class action lawsuits tied to its Phase III Fianlimab Libtayo trial and alleged misleading disclosures about the study’s assumptions and prospects.
The complaints focus on claims that preliminary statistical assumptions for the cancer study were flawed, that the active treatment arm showed limited differentiation from standard therapies, and that investors suffered losses when these issues surfaced publicly.
The legal headlines arrive after a sharp run in Regeneron Pharmaceuticals’ share price, with a 90 day share price return of 29.12% and a 1 year total shareholder return of 39.33%. This leaves recent 7 day and 30 day share price weakness looking more like fading near term momentum than a broken longer term story.
Scan how Regeneron Pharmaceuticals stacks up against other resilient healthcare names by reviewing our hand picked 11 resilient stocks with low risk scores with historically lower risk profiles and sturdier fundamentals.
Bulls view Regeneron Pharmaceuticals’ trial setbacks as a temporary legal overhang, while bears see a richer price colliding with fresh headline risk. Which story does the current valuation actually support next?
Most Popular Narrative: 5% Undervalued
Regeneron Pharmaceuticals last closed at $793.74, compared with a widely followed narrative fair value estimate of $833.31. This frames the lawsuits against a stock already modeled with modest growth and a higher required return of 7.24%.
Regeneron's broad and advancing pipeline, including recent or upcoming pivotal data in immunology, oncology (notably Lynozyfic and odronextamab), genetic medicines, and obesity, positions the company to benefit from demographic-driven increases in demand for advanced therapies and from the rise in personalized and precision medicine, supporting future revenue growth and pipeline-driven earnings upside.
See why 83 investors see Regeneron Pharmaceuticals as 5% undervalued.
Result: Fair Value of $833.31 (UNDERVALUED)
Still, the narrative can be knocked off course if EYLEA faces steeper pressure from biosimilars or if high R&D spend fails to convert into new blockbusters.
Find out about the key risks to this Regeneron Pharmaceuticals narrative.
Another view on Regeneron Pharmaceuticals valuation
On earnings multiples, Regeneron Pharmaceuticals looks less clear cut. The stock trades on a P/E of 18.3x, compared with 16.4x for the wider US biotech group, yet the peer set sits nearer 26.8x and the fair ratio points to 28.3x. Is that a valuation buffer or a warning that expectations are already rich?
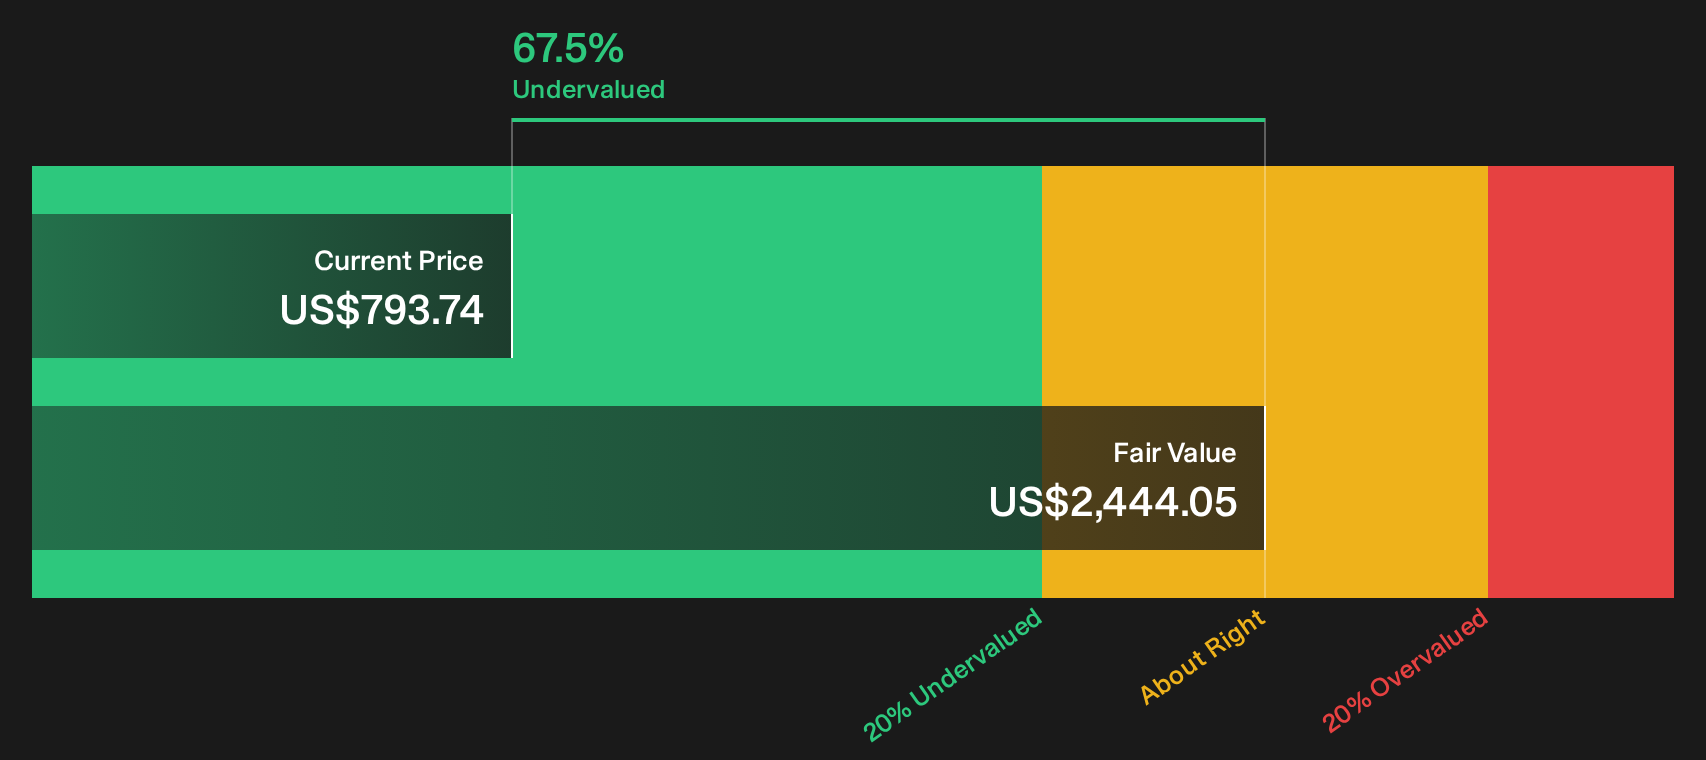
Our DCF model reaches a very different conclusion, with Regeneron Pharmaceuticals at $793.74 versus an estimated future cash flow value of $2,444.05. For readers who lean more on cash flows than earnings multiples, that spread may warrant a closer look at the underlying assumptions. Look into how the SWS DCF model arrives at its fair value..
Next Steps
Mixed opinions around Regeneron Pharmaceuticals are loud, and the lawsuits only sharpen that debate, so review the numbers quickly and stress test your own thesis using its 2 key rewards
Looking for more investment ideas beyond Regeneron Pharmaceuticals?
If you stop with Regeneron Pharmaceuticals, you only see one angle. Broaden your watchlist using focused screeners that surface different kinds of opportunities in seconds.
- Target potential mispricings by scanning 35 high quality undervalued stocks that combine quality fundamentals with what may be more conservative market expectations.
- Strengthen your income shortlist by zeroing in on 6 dividend fortresses built around higher yields and financial resilience.
- Protect your downside by reviewing a list of solid balance sheet and fundamentals (23 results) that many investors overlook until volatility hits.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com