
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
C3.ai (AI) Stock Looks Fully Priced Despite Its 76% Five Year Slide
C3.ai has seen its share price decline 76.3% over the past 5 years, even after a recent bounce, which puts a sharp spotlight on what investors are paying today for its current level of sales. With the stock at US$11.17 at the last close and the story dominated by restructuring and big contract wins, the key issue is how that tag lines up with the revenue base the business is generating right now.
- The 76.3% slide over 5 years puts long term holders deep in the red and raises a very direct question about whether the present valuation can still be anchored to the company’s sales profile.
- Recent cost cuts, a 73% quarter on quarter jump in bookings and positive free cash flow suggest management actions may support different expectations for future margins and the timing of cash generation, which all feed into what investors might be willing to pay for each dollar of current revenue.
- The analysts covering C3.ai have run their own numbers. See what analysts think C3.ai's shares could be worth.
The issue now is whether C3.ai's current share price is justified by its sales when measured against the Fair Ratio benchmark.
If you want to stress test this same sales based valuation question beyond C3.ai, compare it against a wider set of 32 AI small caps.
Has C3.ai Run Too Far on Sales?
P/S fits C3.ai because the business is still loss making, so earnings based metrics like P/E do not give much insight into what the market is paying for its revenue stream.
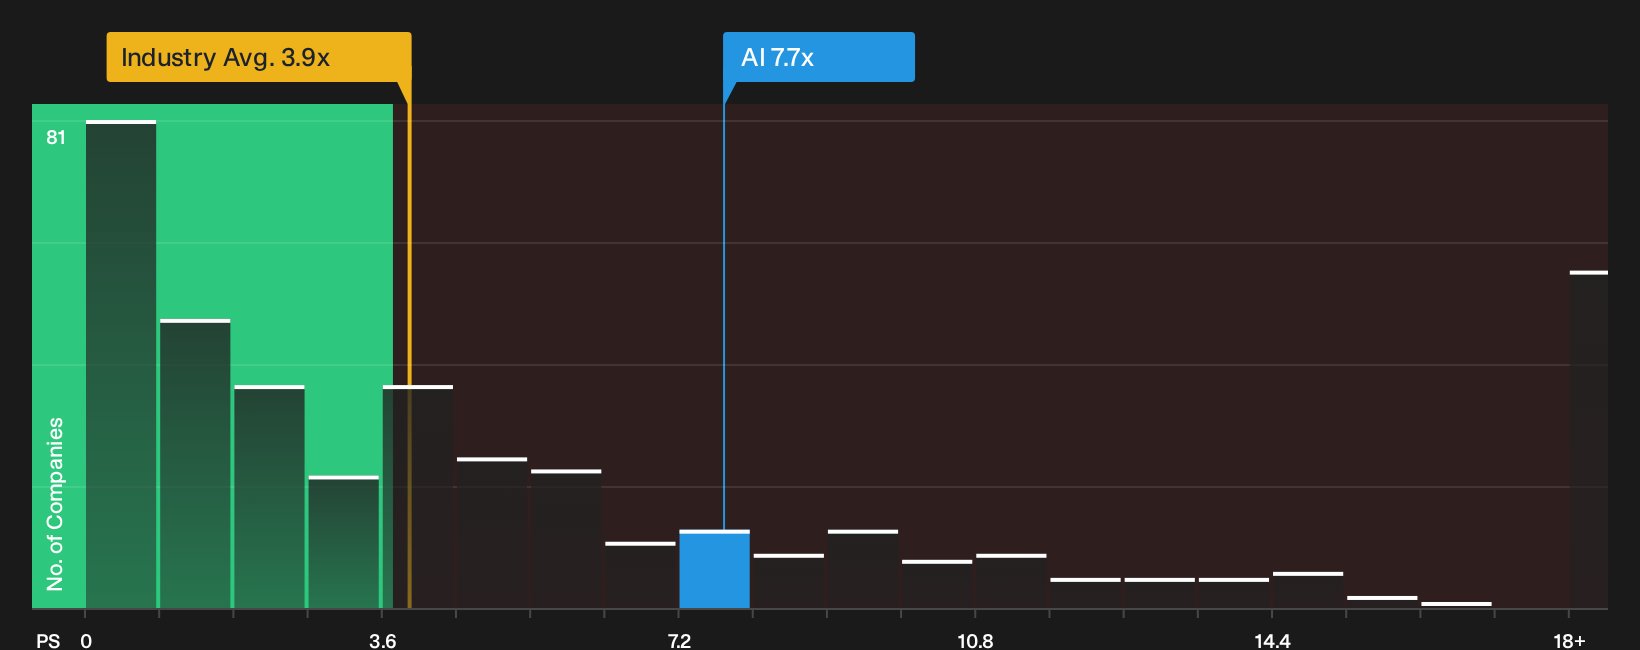
Right now, C3.ai trades on a P/S of about 7.7x, which is roughly double the wider software industry level of about 3.9x and also well above the peer group at roughly 2.7x. The Fair Ratio model, which blends the firm’s growth profile, margins, size and risk into a tailored benchmark, points to a much lower P/S than today’s market tag. That very wide gap suggests the framework is heavily penalising ongoing losses and the quality of revenue. Its output is therefore better read as a caution that the stock prices in a rich sales multiple rather than a precise fair value line. Because the latest quarter showed a 73% jump in bookings and sharply lower costs, the current valuation leaves you weighing whether that operating progress is enough to justify paying this kind of premium to sales. Explore the numbers behind C3.ai's P/S valuation.
The C3.ai Narrative: What Would Justify Today's Price?
C3.ai's valuation puzzle becomes clearer when you spell out which potential paths for growth, margins and earnings would need to occur for the stock to be worth significantly more or less than it is today. This is exactly what Simply Wall St Narratives aim to do on the Community page. Each narrative presents a fair value as a thesis about how C3.ai's business might develop, which you can follow over time rather than viewing as a one-off snapshot.
Community views on C3.ai are split between a potential turnaround driven by partnerships and agentic AI, and concerns that ongoing losses still matter more.
Bull case: 21% undervalued
"The new Strategic Integrator Program, which enables OEMs and major system integrators to build and deploy their own domain-specific applications on the C3 Agentic AI platform, opens a powerful, high-margin, multiplier business model that most analysts haven't factored in…"
Discover why this Narrative puts C3.ai at 21% undervalued.
Bear case: 27% overvalued
"C3.ai reported a 19% year-over-year revenue decrease for the most recent quarter and withdrew previously issued financial guidance, signaling ongoing uncertainty in top-line performance and raising doubts about the consistency of future revenue growth and the company's ability to achieve non-GAAP profitability…"
Explore why this Narrative puts C3.ai at 27% overvalued.
One more C3.ai piece investors often check before deciding what comes next
Everything so far has focused on what C3.ai looks like today, while professional forecasts sketch out where the business could be a few years from now and give you another reference point to weigh against the current share price. Explore where analysts expect C3.ai to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com