
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Lennar (LEN) Nears A Tough Earnings Report, Is The Stock Cheap Enough?
Lennar earnings preview and why short term pressure matters
Lennar (LEN) heads into its fiscal third quarter report with expectations of weaker earnings and revenue as affordability issues, softer pricing and slimmer homebuilding margins stay in focus for investors.
Lennar’s share price has retreated over recent months, with a 30 day share price return of down 7.9% and a year to date share price return of down 23.3%. Total shareholder return over the past year declined 39%, pointing to fading momentum even as the builder continues to roll out new communities and amenity openings in places like Florida, California, Alabama and Georgia.
Spot opportunities beyond Lennar by scanning our hand picked list of 35 high quality undervalued stocks, which combine resilient cash flows with balance sheets built for tougher housing cycles. Bulls point to Lennar’s scale and recent community openings. Bears focus on shrinking margins and a stock that has already fallen hard. Which story fits the current valuation setup better as earnings hit?Most Popular Narrative: 7% Undervalued
Lennar last closed at $79.99, compared with a widely followed fair value estimate of $86.23 that incorporates assumptions of slower growth and firmer margins.
Lennar's transition to an asset-light, land-light model with just-in-time delivery is expected to generate more predictable volume and growth, reduce the asset base and risk profile, improve cash flow, and enhance future revenue and net margin potential.
See why 42 investors see Lennar as 7% undervalued.
Result: Fair Value of $86.23 (UNDERVALUED)
Still, if mortgage costs stay elevated or sales incentives keep stretching, Lennar’s entry level tilt and land banking expenses could pressure margins and strain the bullish case.
Find out about the key risks to this Lennar narrative.
Another View on Lennar’s Valuation
There is a second lens on Lennar that uses the SWS DCF model rather than analyst targets. On that measure, the shares at $79.99 sit above an estimated future cash flow value of $43.62, which points to an overvalued outcome instead of the 7% undervalued story.
That gap reflects very different assumptions about how much cash Lennar can generate and how those dollars should be discounted back to today. It leaves a simple question for investors weighing the stock ahead of earnings: Which set of assumptions feels closer to how you think this business will actually perform over time?
Look into how the SWS DCF model arrives at its fair value.
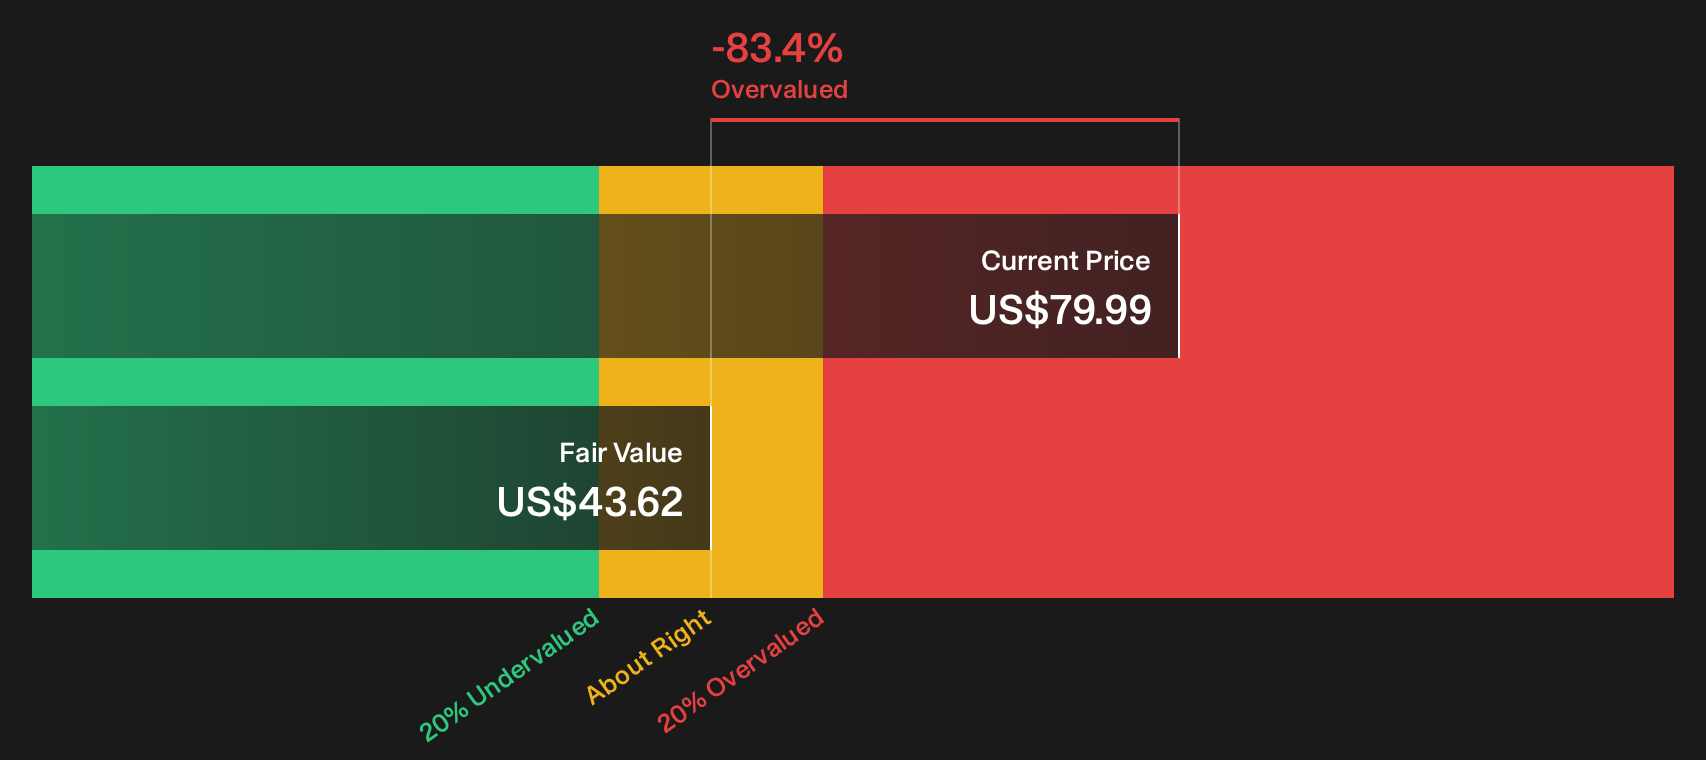
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Lennar for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Lennar can feel unsettling, so move quickly from headline takes to your own conclusion by weighing the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Lennar?
Do not stop your research with Lennar. Use the Simply Wall Street Screener to quickly surface fresh ideas that match how you like to invest.
- Target steady compounders by reviewing a 11 resilient stocks with low risk scores that aim to keep downside contained while still leaving room for sensible upside.
- Hunt for mispriced opportunities by scanning our 35 high quality undervalued stocks that combine resilient balance sheets with cash flows the market might be overlooking.
- Spot potential future leaders early by checking the 15 high quality undiscovered gems before other investors start paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com