
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What DXP Enterprises (DXPE)'s Cash Flow Gains Mean For Shareholders
- DXP Enterprises has reported 16.8% annual revenue growth over the past five years, alongside a 4 percentage point expansion in free cash flow margin, reflecting stronger operating efficiency.
- Share repurchases have supported 22.5% annual earnings per share growth over the last two years, meaning profit per share has risen faster than sales.
- We will now see how DXP Enterprises' rising free cash flow margin could reshape the investment narrative that analysts outlined earlier.
Scan beyond DXP Enterprises and see how other industrials are strengthening cash generation and shareholder returns with a curated list of list of solid balance sheet and fundamentals (23 results).
DXP Enterprises Investment Narrative Recap
For an investor to stay comfortable owning DXP Enterprises, there needs to be confidence that its MRO distribution model keeps converting revenue into higher quality cash generation, even with exposure to cyclical energy projects. The recent record of 16.8% annual sales growth and a 4 percentage point lift in free cash flow margin supports that belief, but does not erase execution risk in slower moving segments.
The key short term swing factor is how efficiently DXP Enterprises turns this stronger cash profile into balance sheet resilience, especially with debt not well covered by operating cash flow. The biggest current risk remains cost pressure and contract profitability in Service Centers and Supply Chain Services, where any stumble could quickly dilute the recent free cash flow gains.
With no new company announcements tied directly to this cash flow story, the most relevant context is still management's push into digital sales and e commerce. Those initiatives sit in the background of the recent free cash flow uplift, since a more online mix can support leaner working capital and better pricing discipline when executed well.
For catalysts, the interesting angle is whether DXP Enterprises can keep using digital tools and customer programs like SmartStore and SmartVend to deepen recurring relationships without letting service intensity drag on margins. Execution here matters because rising labor costs, integration of acquired operations and any slow repricing on large contracts all pull in the opposite direction and could test how durable that higher free cash flow margin really is.
DXP Enterprises' narrative projects US$2.7b revenue and US$174.7m earnings by 2029. That profile assumes 8.7% yearly revenue growth and an earnings increase of about US$81.6m from current earnings of US$93.1m.
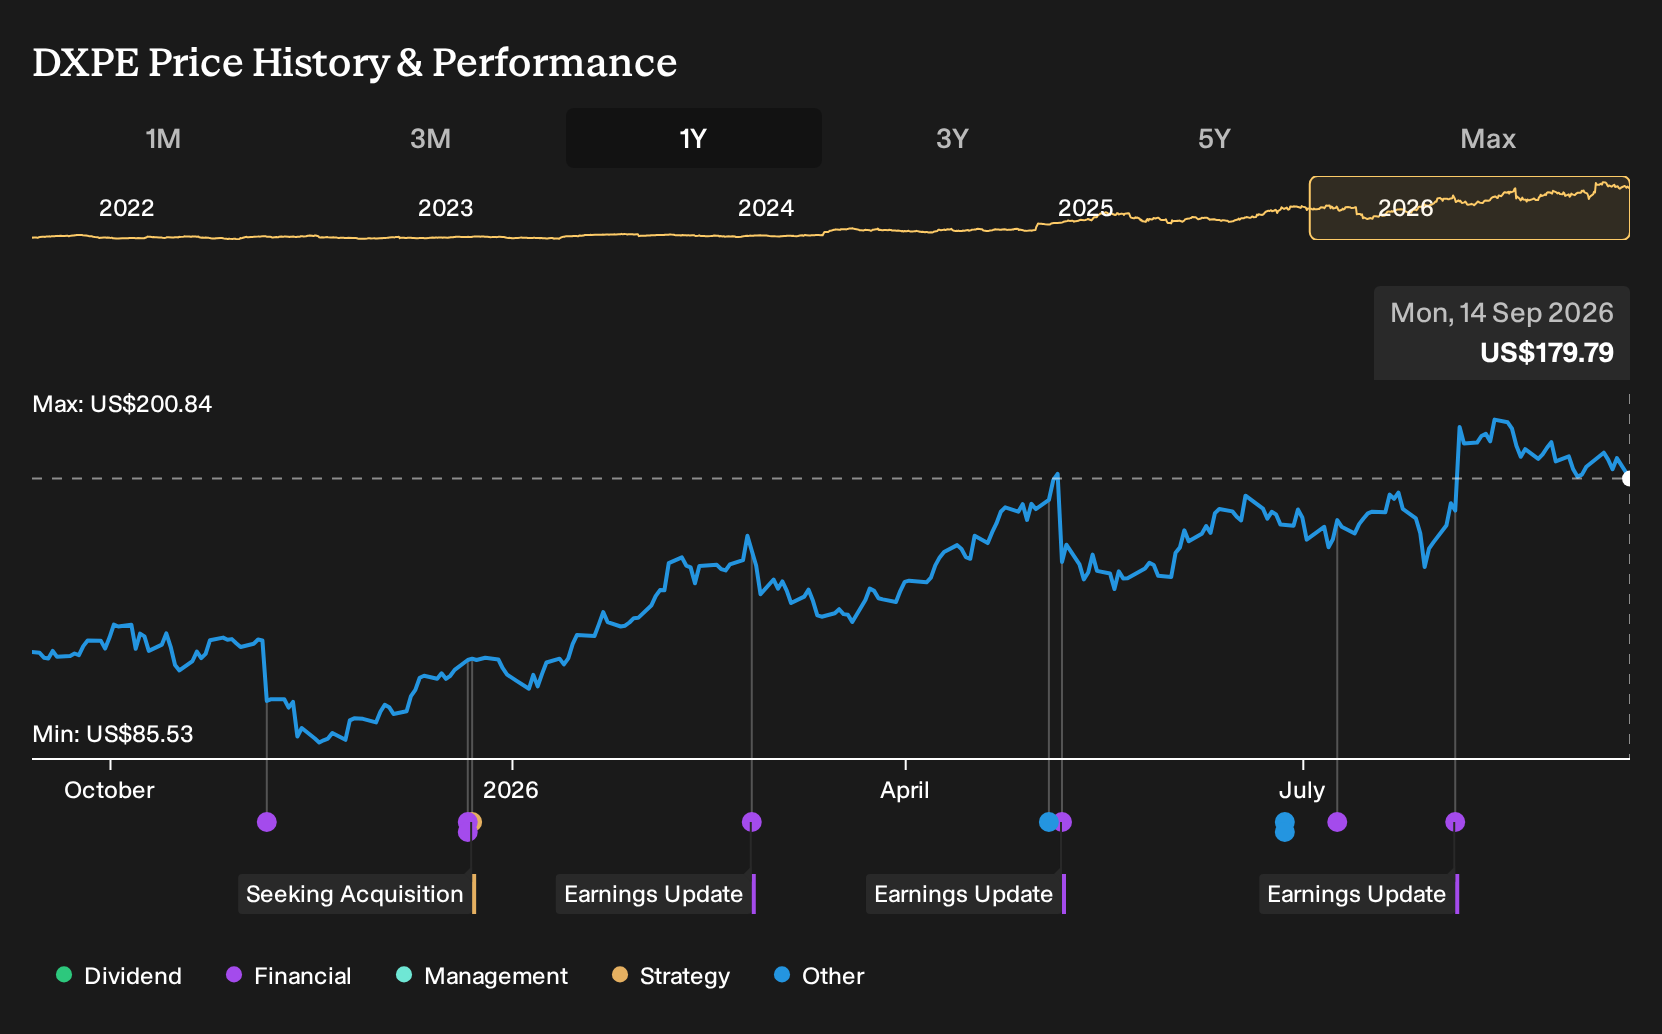
Uncover why DXP Enterprises' fair value indicates an 11% potential upside to its current price, which could narrow quickly as expectations catch up.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community cluster tightly between US$200 and about US$202.80, so even retail investors using their own models are not far apart on DXP Enterprises. These opinions still ignore recent news, and factors such as energy exposure, labor costs and acquisition execution could all shift how you judge future cash generation.
Explore another DXP Enterprises fair value estimate, including one that suggests up to 13% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your DXP Enterprises research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for DXP Enterprises. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DXP Enterprises' overall financial health at a glance.
Looking for more DXP Enterprises style investment ideas?
If DXP Enterprises has sharpened your focus on cash flow quality and balance sheet strength, broaden the watchlist by scanning other stocks through the Simply Wall St Screener. Use it to spot businesses that match your own risk comfort, income needs and growth appetite rather than relying on a single ticker.
- For investors hunting for quality at a sensible entry point, start with a curated group of 35 high quality undervalued stocks that pair fundamentals with appealing pricing.
- If capital preservation and steadier risk profiles sit higher on your priority list, filter for companies in the 11 resilient stocks with low risk scores and see which ones match your comfort zone.
- Those looking for underfollowed ideas can widen the opportunity set by scanning through a 15 high quality undiscovered gems that rarely feature on front-page stock lists.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com