
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Profit Drop Is Altering The Investment Case For New Hope (ASX:NHC)?
- New Hope Corporation Limited reported full year 2026 results showing sales of A$1,766.53 million, revenue of A$1,803.97 million, and net income of A$160.96 million, with basic earnings per share from continuing operations at A$0.191.
- The sharp drop in net income and earnings per share against relatively stable revenue suggests pressure on New Hope's cost structure and overall profitability.
- We will now assess how New Hope's weaker earnings and compressed profitability may influence its investment narrative and long term risk profile.
New Hope Investment Narrative Recap
For a shareholder in New Hope, the big idea is simple. You need to believe the business can keep running coal assets efficiently enough for cash generation to outweigh the structural headwinds facing thermal coal. The latest results, with revenue broadly steady but net income at A$160.96 million and EPS at A$0.191, put the spotlight firmly on costs and margins.
In the short term, the key swing factor is whether management can stabilise profitability without leaning on one off items that affected earlier periods. The biggest risk is that weaker margins and a less covered dividend limit flexibility on capital spending or payouts if coal markets or regulatory costs tighten further.
The full year 2026 earnings announcement is the clearest recent update to test that thesis. Sales of A$1,766.53 million and revenue of A$1,803.97 million were close to the prior year, while profit dropped sharply, which lines up with existing flags about lower net margins and previous non recurring gains that had supported earlier numbers.
For catalysts, this result matters because it gives you a cleaner read on New Hope’s underlying earnings power and how resilient cash flows might be against rising remediation, regulatory and financing pressures. It also feeds back into questions around dividend sustainability and whether future volume projects can be funded comfortably from internal resources.
New Hope's narrative projects A$2.0 billion revenue and A$375.0 million earnings by 2029. This assumes 8.7% yearly revenue growth and an earnings increase of about A$221.6 million from A$153.4 million today.
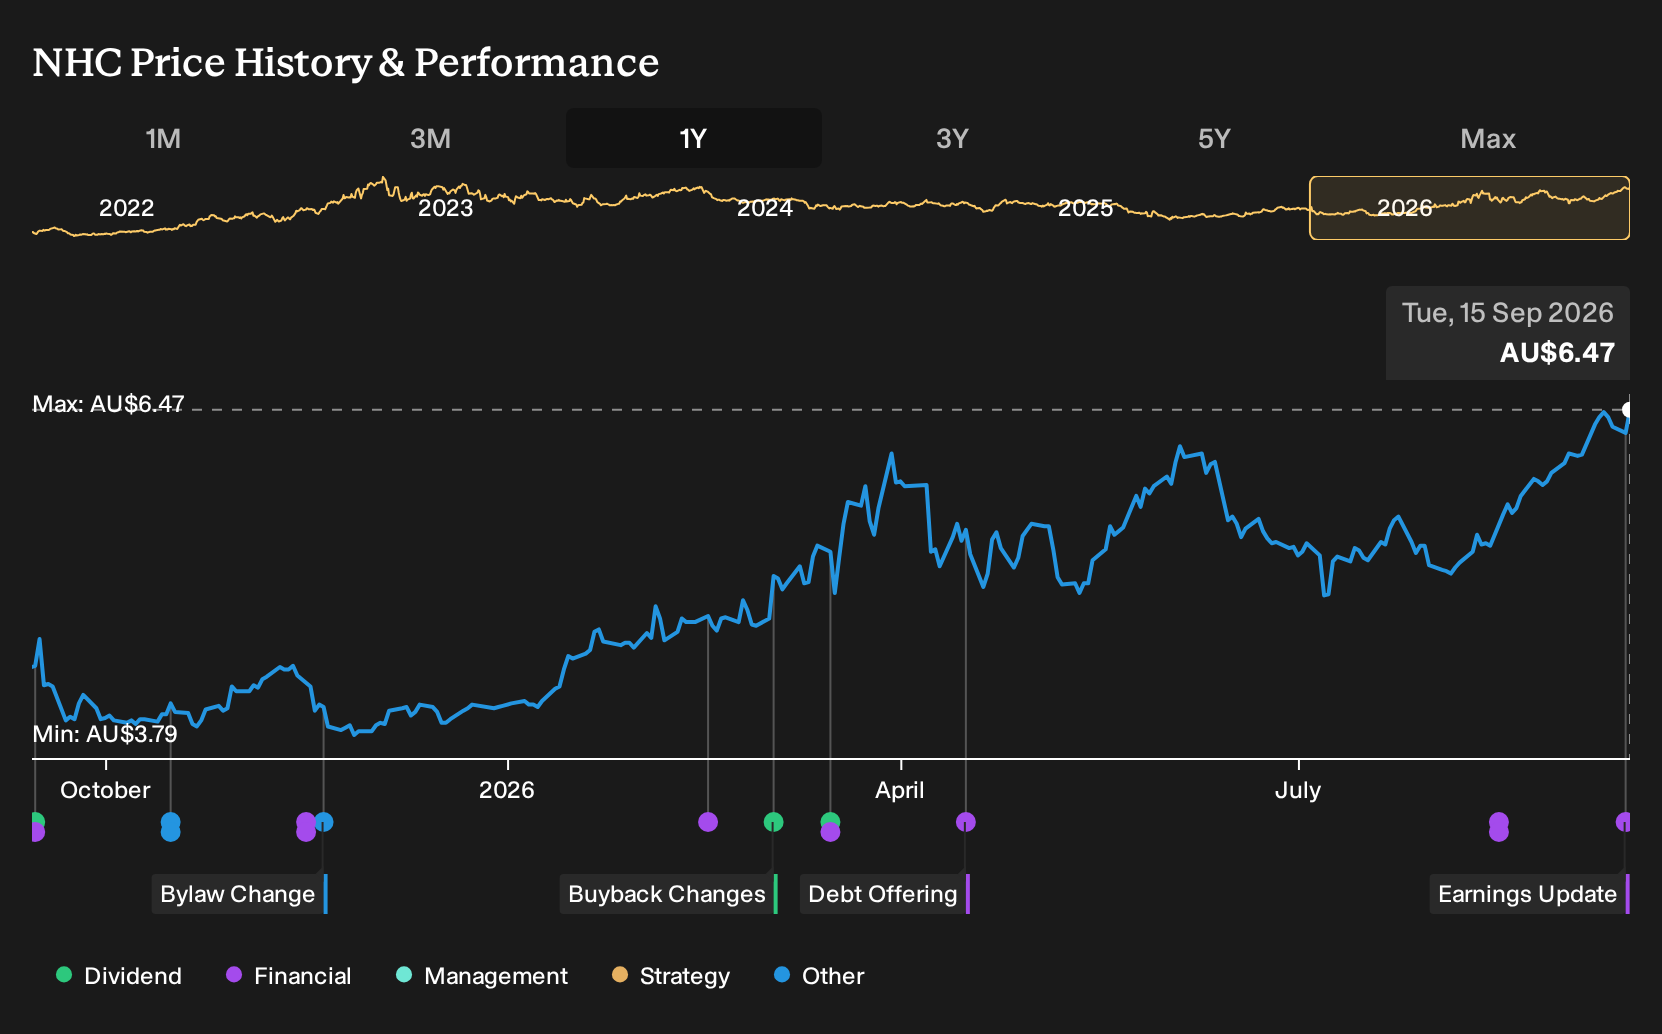
Uncover how New Hope's fair value indicates a 16% potential downside to its current price, a premium that may not hold.
Exploring Other Perspectives
One alternate narrative for New Hope leans hard into decarbonisation risk. The most pessimistic analysts were only pencilling in A$2.0b of revenue and around A$348.8 million of earnings by 2029, and even that looked rich to them. They saw a fair value closer to A$4.5, so they treated coal policy risk as far more urgent. Those views were formed before this earnings release. Some of those forecasts and price targets may now be revisited as you weigh up which storyline you find more convincing.
Explore 4 other New Hope fair value estimates, including one that suggests as much as 30% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your New Hope research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for New Hope. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate New Hope's overall financial health at a glance.
Looking for more investment ideas beyond New Hope?
If New Hope has sharpened your focus on risk, cash generation and balance sheet strength, it can be useful to widen the lens and compare it with other businesses that share similar qualities or offer a different profile altogether.
- For investors who want income that feels more predictable than coal prices, consider screening for higher yielding opportunities through 4 dividend fortresses.
- If value and financial resilience are your priority, you can cast a wider net across companies with strong balance sheets using the list of solid balance sheet and fundamentals (12 results).
- For those searching for potential future leaders that are not yet widely followed, expand your watchlist by checking stocks in the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com