
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did AI Slowdown Calls Just Shift Intel's (INTC) Investment Narrative?
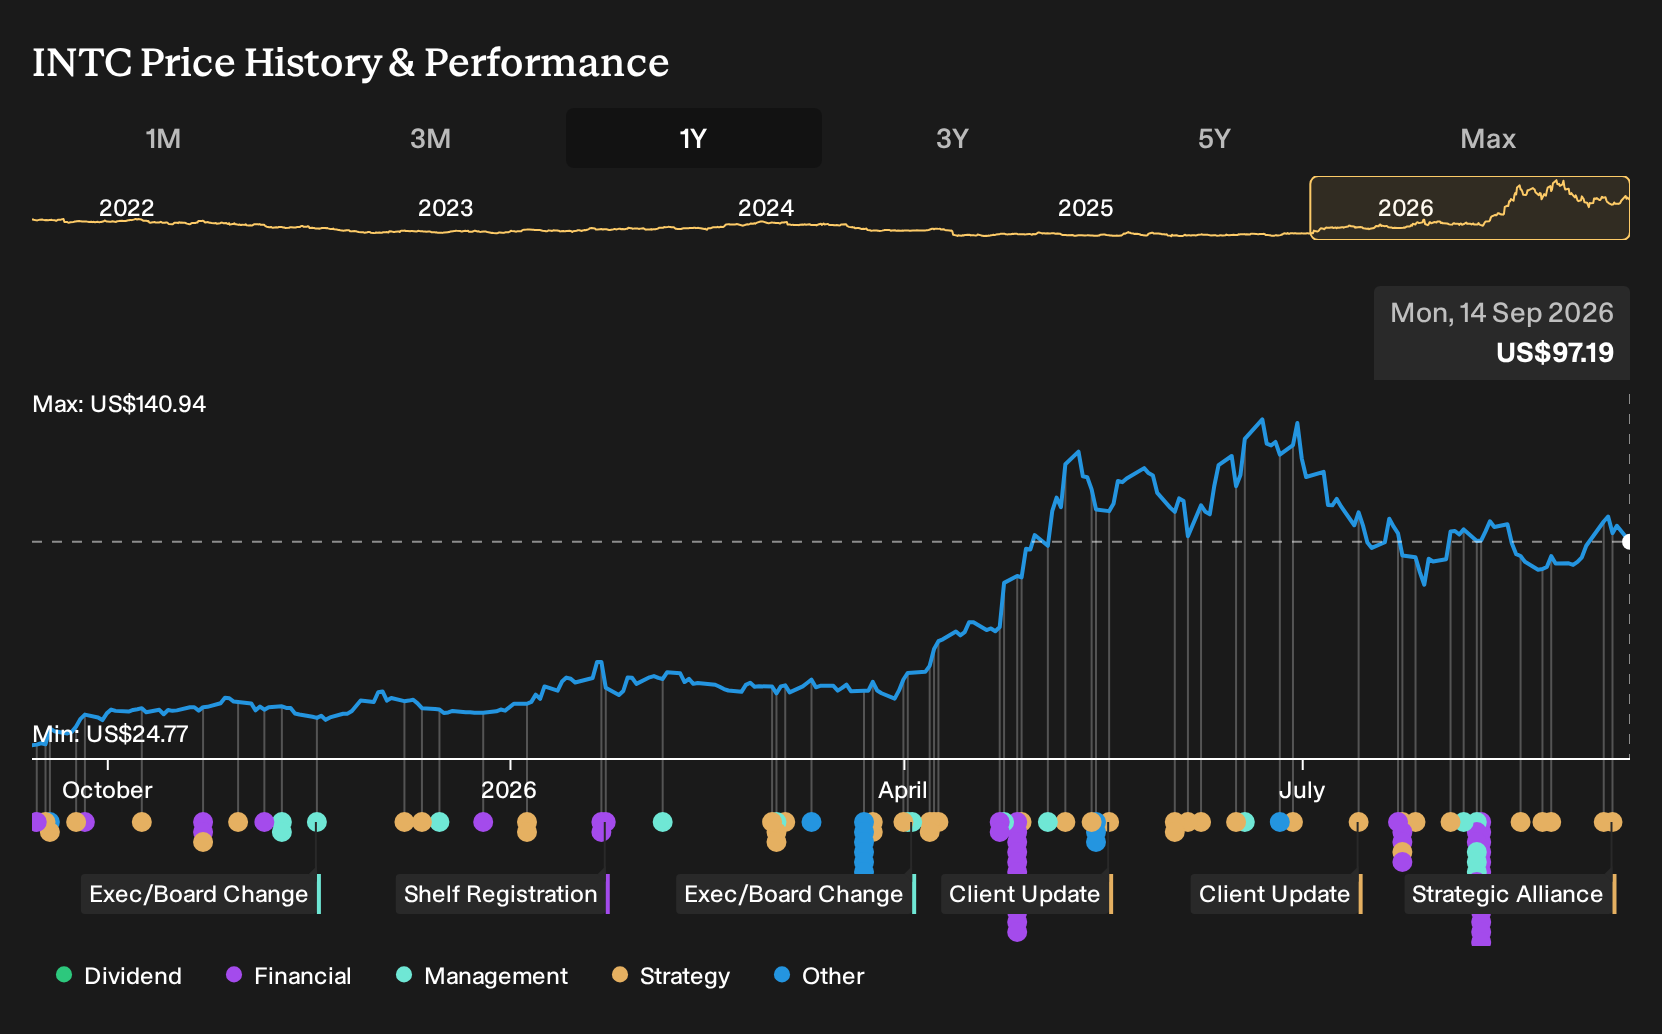
- In early September 2026, leading AI executives, including Anthropic’s Dario Amodei and OpenAI’s Sam Altman, urged a coordinated slowdown in advanced AI development. This pressured semiconductor suppliers such as Intel as investors reassessed potential chip demand tied to large frontier model training.
- The same debate has thrown a spotlight on Intel’s role in secure, CPU-centered AI infrastructure. In this area, agentic AI orchestration and edge workloads, supported by efforts like its Atsign collaboration, rely heavily on general-purpose compute and hardware-rooted security rather than solely on frontier training accelerators.
- We will now explore how Intel's investment narrative could be influenced by these AI slowdown calls and the focus on secure orchestration.
Scan how Intel’s secure agentic AI push compares with other potential hardware beneficiaries by reviewing our hand-picked shortlist of 60 AI infrastructure stocks in this same AI infrastructure wave.
Intel Investment Narrative Recap
To own Intel, you need to believe the business can turn heavy AI and foundry investment into sustainable earnings while fixing past execution issues. The near term story is about whether rising agentic AI workloads, CPU price increases and foundry traction can offset an unprofitable base and high OpEx and CapEx. The biggest short term catalyst is operational follow through on AI centric products and customer wins. The key risk is that organizational complexity and manufacturing constraints slow this shift just as AI hardware spending comes under scrutiny.
The recent AI slowdown calls hit sentiment but do not yet change Intel’s core operating thesis. If hyperscalers and enterprises keep prioritizing secure orchestration and edge workloads, Intel’s CPU and security features remain central to deployments, even if frontier training growth cools. The business still has to prove it can streamline costs, sustain revenue growth around 14% and move from loss making today to the profitability analysts expect, without overextending the balance sheet on capacity that takes time to fill.
The Atsign collaboration is the clearest operational tie in to the current AI debate. Intel is not just selling raw compute. It is leaning into hardware rooted security, zero trust architectures and encrypted agent to agent traffic for real world systems like smart transportation. That matters if regulators, cities and industrial customers start treating secure AI orchestration as non negotiable infrastructure rather than an optional upgrade.
For catalysts, the ~88x encryption uplift on Xeon and ~60x on Core Ultra 9 directly supports the idea that Intel’s CPUs can host dense agentic AI traffic without choking on cryptography overhead. That sharpens Intel’s pitch against accelerator only stacks and speaks to where future demand could cluster if frontier training budgets cool and inference plus edge security spending holds up. The risk is simple. If Intel cannot keep execution tight across hardware, software partners and foundry delivery, these technical wins may not translate into the scale of deployments needed to justify current investment levels.
Intel's narrative projects US$92.4b revenue and US$21.7b earnings by 2029. This assumes 17.4% yearly revenue growth and an earnings swing of about US$33b from a loss of US$11.3b today to the forecast consensus level.
Uncover why Intel's fair value indicates a 19% potential upside to its current price before the gap between price and value tightens.
Exploring Other Perspectives
Some of the most optimistic Intel analysts were already leaning on foundry progress as a key catalyst, penciling in about US$90.5b in 2029 revenue and US$16.5b in earnings before this AI slowdown debate flared. You can now weigh that High NA and 18A optimism against fresh questions on AI chip spending and decide which narrative feels more realistic.
Explore 16 other Intel fair value estimates, including one that suggests potential upside of up to 415% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Intel research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Intel. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Intel's overall financial health at a glance.
Looking For More Investment Ideas Beyond Intel?
If the Intel story has sharpened your thinking about AI infrastructure and earnings power, it can be useful to line it up against other opportunities using the Simply Wall St Screener.
- For investors focused on quality at a reasonable entry point, scan a curated group of 35 high quality undervalued stocks that pair solid fundamentals with compressed expectations.
- If capital preservation matters just as much as upside, consider filtering for 11 resilient stocks with low risk scores that score well on balance sheet strength and business stability.
- For those hunting for less crowded opportunities, review a hand picked pool of 15 high quality undiscovered gems that may not yet be widely followed but show strong underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com