
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
John Marshall Bancorp Among 3 Growth Companies Insiders Favor
Over the last 7 days, the United States market has experienced a slight decline of 1.5%, yet it remains up by 13% over the past year with earnings forecasted to grow by 17% annually. In such an environment, growth companies with high insider ownership can be particularly appealing as they often indicate strong confidence from those closest to the business's operations and future prospects.
Top 10 Growth Companies With High Insider Ownership In The United States
| Name | Insider Ownership | Earnings Growth |
| Uxin (UXIN) | 34.3% | 69.4% |
| Upstart Holdings (UPST) | 14.2% | 68.4% |
| Standard Nuclear (STDN) | 18.8% | 61.3% |
| Precigen (PGEN) | 11.7% | 55.4% |
| Nu Holdings (NU) | 22.8% | 21.8% |
| Karman Holdings (KRMN) | 14.4% | 54% |
| Himax Technologies (HIMX) | 29.2% | 70.2% |
| Dave (DAVE) | 16.9% | 23.2% |
| Carlyle Group (CG) | 27.4% | 20.5% |
| Almonty Industries (ALM) | 10.8% | 38% |
Let's take a closer look at a couple of our picks from the screened companies.
John Marshall Bancorp (JMSB)
Simply Wall St Growth Rating: ★★★★★☆
Overview: John Marshall Bancorp, Inc. is the bank holding company for John Marshall Bank, offering banking products and financial services in Arlington, Fairfax, Loudoun, Prince William, Montgomery, and the District of Columbia with a market cap of $323.72 million.
Operations: The company generates revenue primarily through its banking segment, which accounts for $66.91 million.
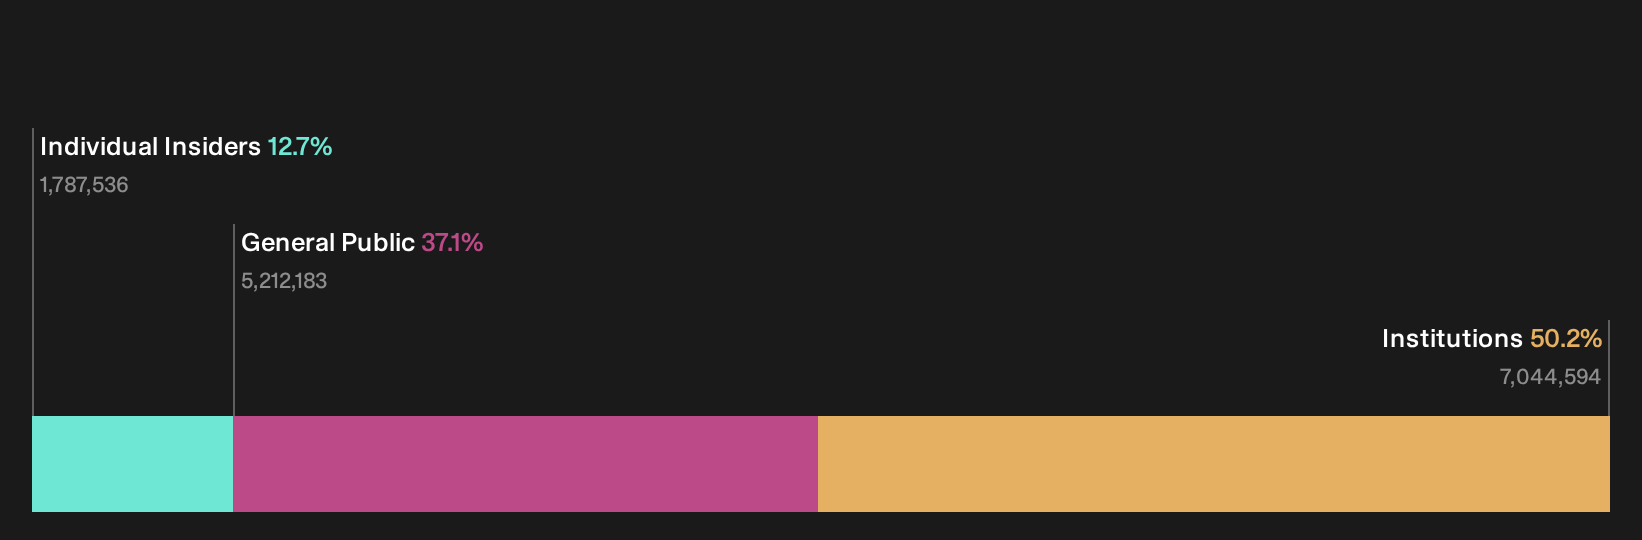
Insider Ownership: 12.7%
Earnings Growth Forecast: 56.9% p.a.
John Marshall Bancorp shows strong growth potential with earnings forecasted to grow 56.9% annually, significantly outpacing the US market. Its revenue is expected to increase by 72.2% per year, and the price-to-earnings ratio of 13.5x indicates good value compared to the broader market. Recent substantial insider buying underscores confidence in its trajectory, despite executive changes and a planned dividend increase following a merger with Eagle Financial Services that could impact future strategic direction.
- Unlock comprehensive insights into our analysis of John Marshall Bancorp stock in this growth report.
- Upon reviewing our latest valuation report, John Marshall Bancorp's share price might be too optimistic.
CarGurus (CARG)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: CarGurus, Inc. operates an online automotive platform facilitating the buying and selling of vehicles both in the United States and internationally, with a market cap of approximately $3.07 billion.
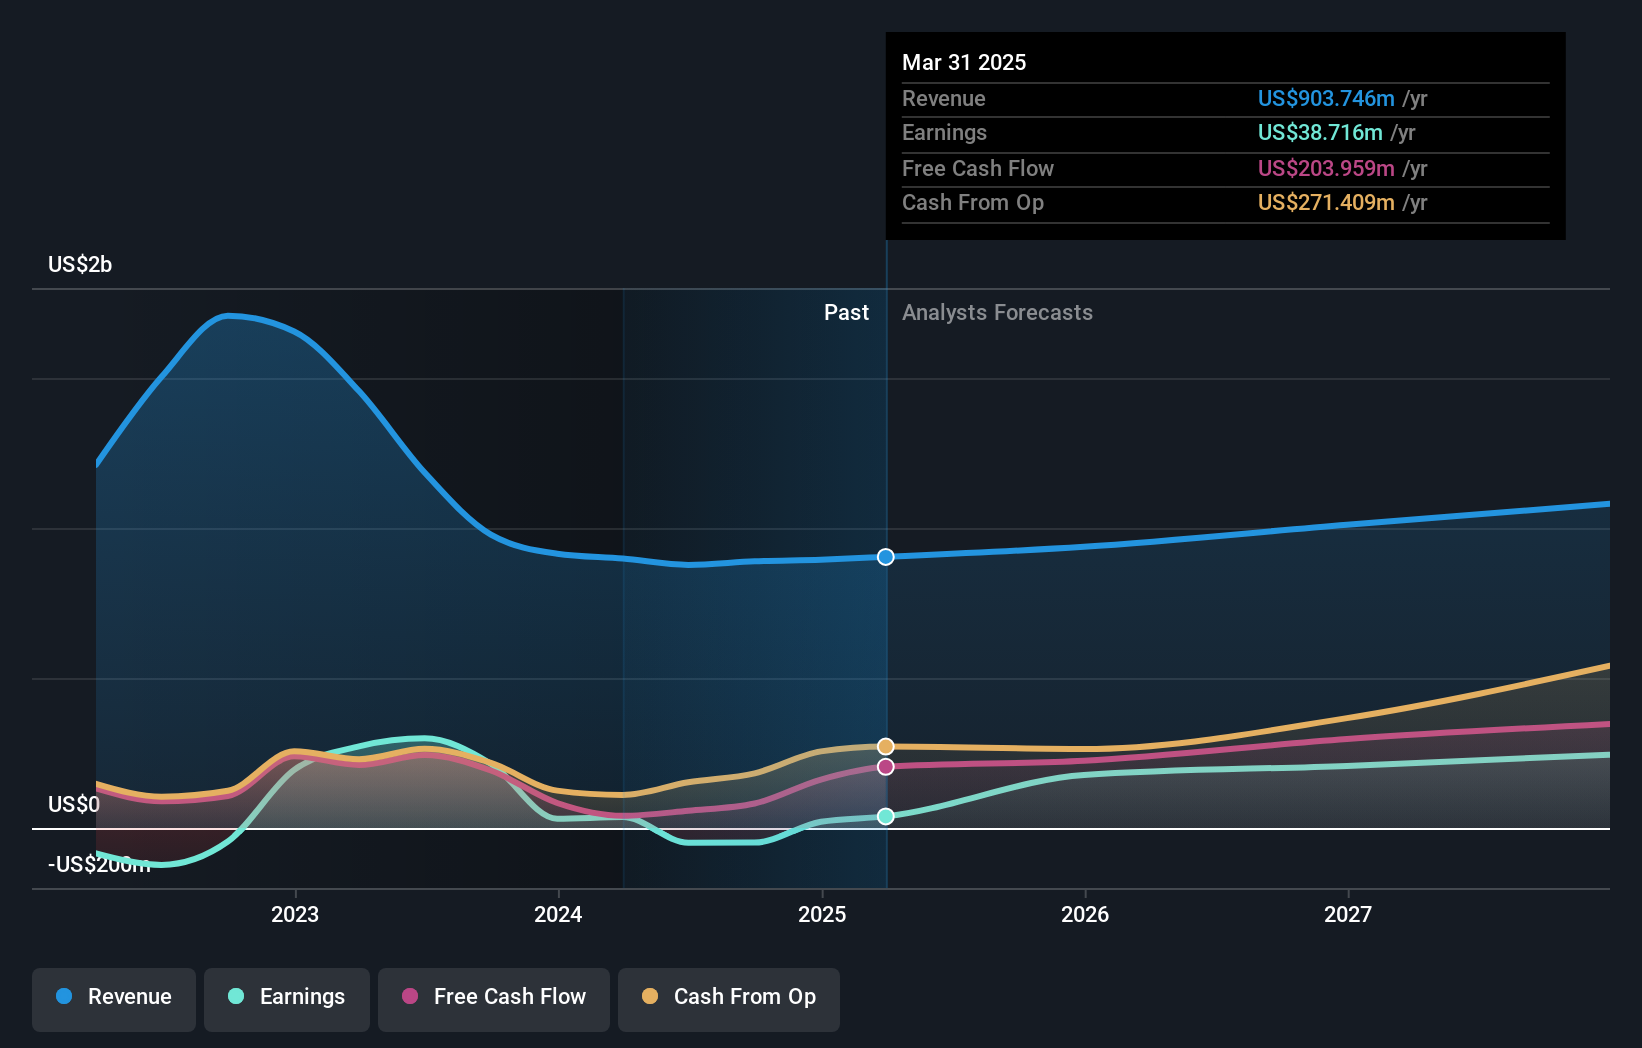
Operations: The company's revenue primarily comes from its Online Marketplaces segment, which generated $967.27 million.
Insider Ownership: 15.1%
Earnings Growth Forecast: 20.9% p.a.
CarGurus demonstrates growth potential with its earnings projected to increase 20.9% annually, surpassing the US market's average. Despite a dip in profit margins from 33.5% to 19.3%, it trades at a significant discount to estimated fair value and analysts expect a price rise of 20.2%. Recent executive changes include appointing Matthew Mandel as CFO, enhancing financial strategy amid ongoing share buybacks totaling US$204.24 million and reduced credit commitments for improved leverage management.
- Take a closer look at CarGurus' potential here in our earnings growth report.
- Our expertly prepared valuation report CarGurus implies its share price may be lower than expected.
Waterdrop (WDH)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Waterdrop Inc. operates as an online insurance brokerage in the People’s Republic of China, connecting users with insurance products from various insurers, and has a market cap of $366.49 million.
Operations: Waterdrop Inc. generates revenue primarily from its online platform that facilitates the connection between users and insurance products offered by various insurers in China.
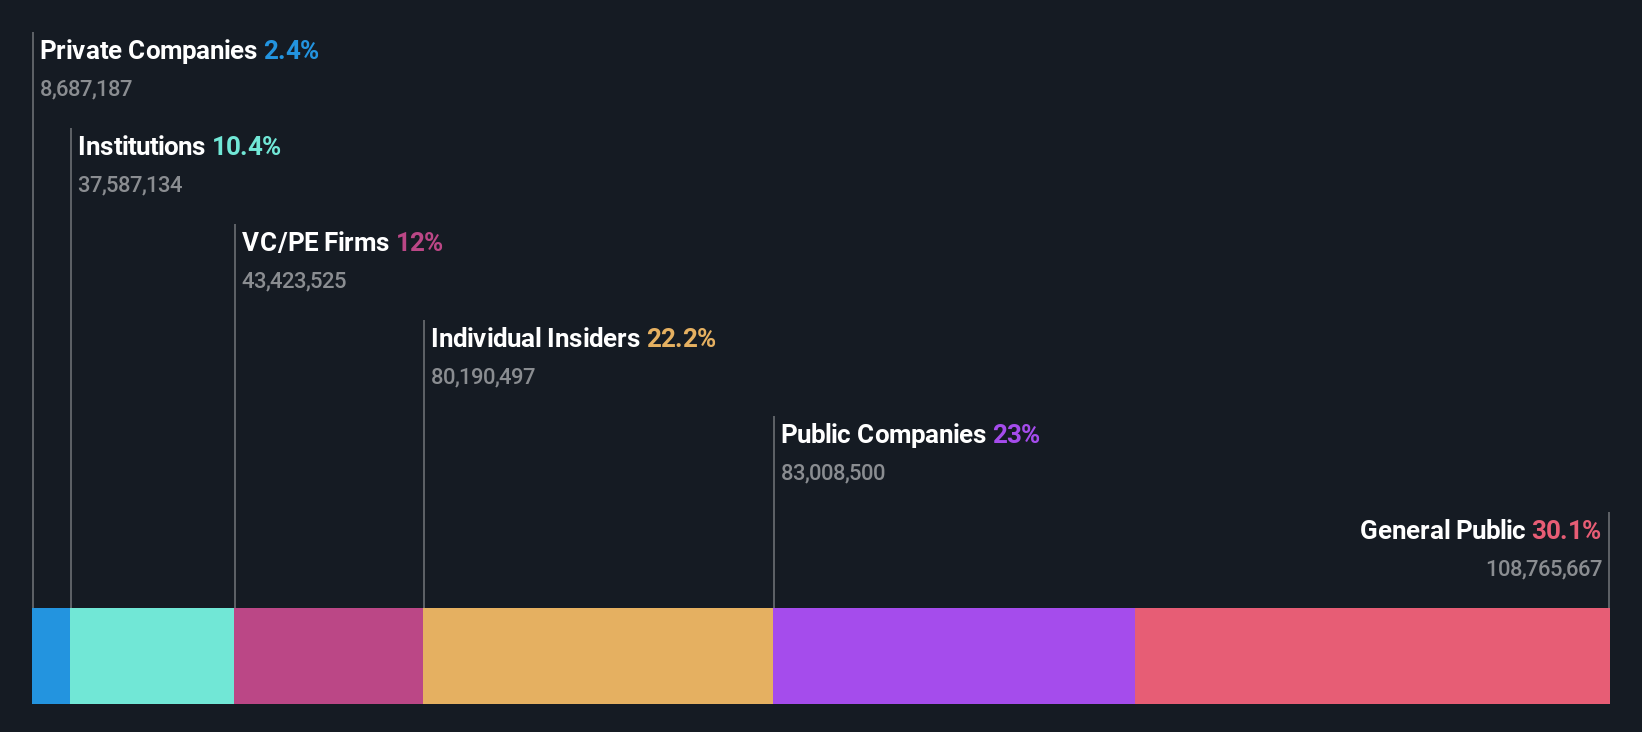
Insider Ownership: 23.1%
Earnings Growth Forecast: 18.7% p.a.
Waterdrop's revenue is forecast to grow 20.4% annually, outpacing the US market average. It trades at a substantial discount to its estimated fair value, indicating potential for investors seeking growth opportunities. Recent earnings showed increased sales but slightly lower net income compared to last year. The company recently announced a dividend of US$0.024 per share and has completed a share buyback program worth US$9.54 million, reflecting strategic capital management efforts.
- Click here and access our complete growth analysis report to understand the dynamics of Waterdrop.
- Our comprehensive valuation report raises the possibility that Waterdrop is priced lower than what may be justified by its financials.
Where To Now?
- Dive into all 182 of the Fast Growing US Companies With High Insider Ownership we have identified here.
- Ready For A Different Approach? The end of cancer? These 34 emerging AI stocks are developing tech that will allow early idenification of life changing disesaes like cancer and Alzheimer's.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com