
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Equity Bancshares (EQBK) Could Be 10% Undervalued After Dividend And M And A Focus
Equity Bancshares (EQBK) has drawn fresh attention after its board approved a quarterly cash dividend of $0.22 per share, alongside recent M&A discussions with Lincoln Bancorp that put the regional bank’s capital priorities in focus.
The recent dividend decision and M&A discussions come after a period where Equity Bancshares has built solid momentum, with the share price delivering an 11.97% year to date return and a 24.57% 1 year total shareholder return, alongside a very large 3 year total shareholder return of 118.34% that suggests investors may be reassessing both growth prospects and risk around the regional lender.
Spot similar regional banking stories setting up for their next move with a curated mix of dividend payers and acquisitive lenders in the list of solid balance sheet and fundamentals (23 results).Bulls point to Equity Bancshares’ strong multi year shareholder returns and recent dividend decision, while bears question how much of that is already in the price. Which side does the current valuation support?
Most Popular Narrative: 10% Undervalued
On the narrative view, Equity Bancshares screens as undervalued, with a fair value of $56 against a last close of $50.23, which puts the focus squarely on whether its M&A and digital push can support that gap.
The strong pipeline of commercial and C&I loan originations, alongside continued small business growth in regional economies, supports future commercial lending volume and fee income, which should stabilize and grow both revenue and earnings. Strategic consolidation through disciplined M&A (with a pipeline of acquisition targets in the $250 million to $1.5 billion range) provides opportunities for scale, cost synergies, and improved operating leverage, supporting sustained net margin and EPS growth.
See why 9 investors see Equity Bancshares as 10% undervalued.
Result: Fair Value of $56 (UNDERVALUED)
Still, the Equity Bancshares story can change quickly if digital heavyweights pull customers away or if commercial real estate and sector specific loans come under pressure.
Find out about the key risks to this Equity Bancshares narrative.
Another View: Equity Bancshares Through The P/E Lens
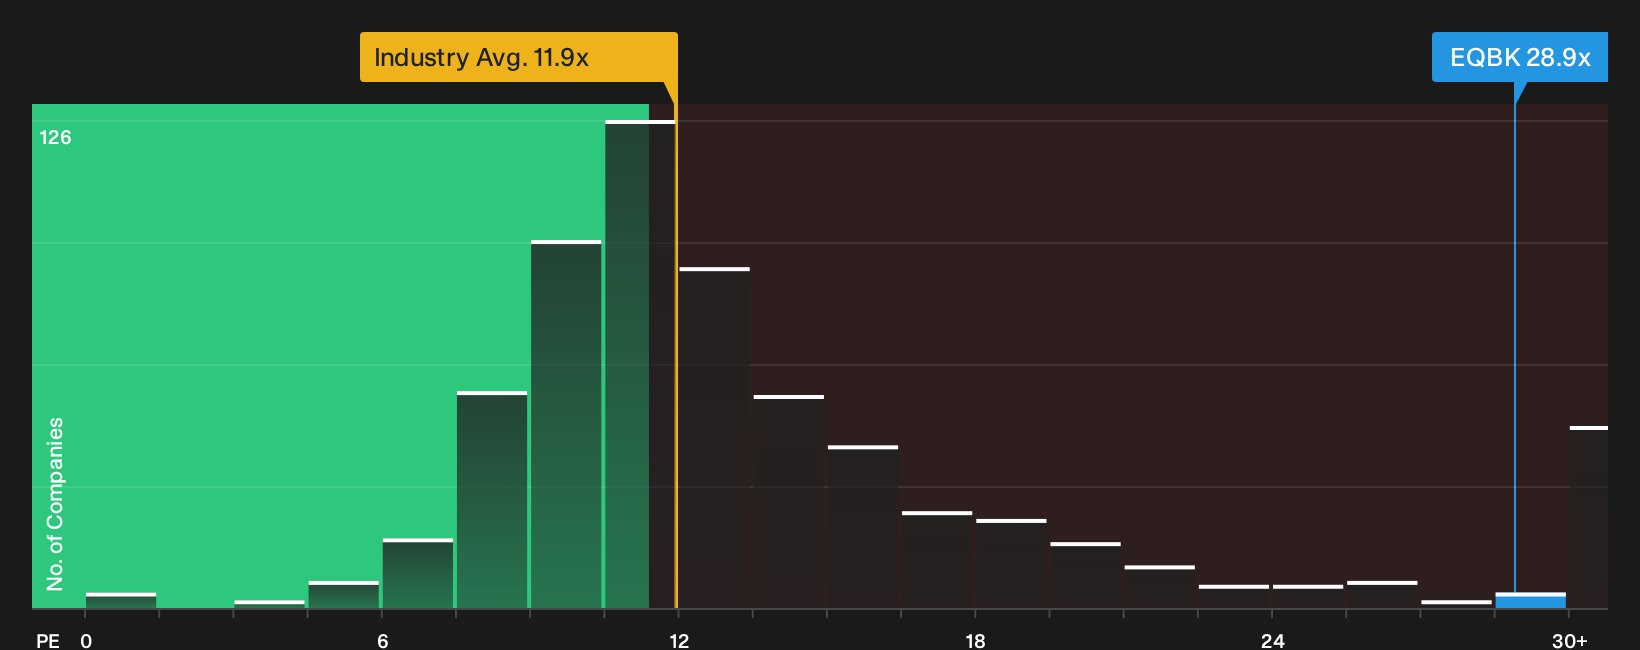
There is a catch. While our model-based fair value suggests Equity Bancshares is attractive, the current P/E of 28.9x is far above the US Banks industry average of 11.9x and the fair ratio of 19.4x, which signals real valuation risk if sentiment cools.
For anyone weighing that trade off against the earlier fair value estimate, the detailed break out of earnings multiples and assumptions in our valuation breakdown is worth a closer look, starting with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages in the Equity Bancshares story so far. Given the blend of concerns and bright spots around the bank, it may be useful to move quickly, review the data, and weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Equity Bancshares?
If you only focus on Equity Bancshares, you may miss other opportunities. Use the Simply Wall Street Screener to scan targeted sets of stocks with clear, data driven filters.
- Target reliable income opportunities by reviewing companies in the 6 dividend fortresses that may appeal if you want yields backed by solid underlying fundamentals.
- Hunt for potential mispriced opportunities by checking the 35 high quality undervalued stocks that line up strong financials with share prices that may not fully reflect them yet.
- Prioritize capital preservation by focusing on the 11 resilient stocks with low risk scores that pair resilient balance sheets with lower risk profiles so you are not caught off guard when conditions change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com