
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
AI Security Expansion Might Change The Case For Investing In SentinelOne (S)
- SentinelOne recently expanded its Wayfinder Frontier AI Services by adding GPT-5.6-Cyber powered code risk analysis and compromise assessment capabilities for enterprise security teams.
- This expansion deepens SentinelOne's use of frontier AI models in both offensive and defensive workflows, which could influence demand for its broader security platform.
- This article examines how SentinelOne's investment narrative interacts with the frontier AI expansion within Wayfinder Frontier AI Services.
Scan beyond SentinelOne and this AI security story by reviewing a curated group of 60 AI infrastructure stocks that could also be positioned for growing demand in advanced cyber defense.
SentinelOne Investment Narrative Recap
To own SentinelOne, you need to believe its AI driven security platform can keep winning share across endpoint, cloud, identity, and data protection, while gradually tightening losses. The big near term swing factor is execution on multi product adoption and the Flex licensing model. The new Wayfinder Frontier AI expansion looks incremental to that story rather than a standalone catalyst.
The main risk still sits in profitability and deal timing. Management is spending heavily on R&D and M&A, and those costs hit margins before revenue fully reflects them. The Wayfinder update adds more AI driven services, which could support perceived product depth, but it does not change the near term pressure from competition, partner dependence, or macro driven deal slippage.
The recent Prompt Security acquisition ties directly into this Wayfinder news. Prompt focuses on GenAI risk, while Wayfinder Frontier AI Services plug frontier models like GPT 5.6 Cyber into real cyber workflows. Together, they broaden SentinelOne's story from endpoint protection to a fuller AI security and governance platform that covers both GenAI usage and advanced threat detection.
For catalysts, that breadth matters because it can reinforce the pitch behind Flex licensing and larger platform deals rather than single point products. The trade off is that these moves add complexity, integration work, and near term margin drag at a time when SentinelOne is still loss making and relies on partners like AWS and hyperscalers to keep the top line moving.
What The Frontier AI Push Means Against Analyst Expectations For SentinelOne
SentinelOne's narrative projects US$1.7b revenue and US$196.5m earnings by 2029. This rests on analysts penciling in 18.0% yearly revenue growth and an earnings swing of roughly US$515m from a loss of US$318.7m today to US$196.5m in the forecast period.
Those numbers give you a rough yardstick for the Wayfinder Frontier AI expansion. The new GPT 5.6 Cyber features slot into a story where analysts already assume steady top line growth and a path from sizeable losses to material profits. Any traction from AI powered code risk analysis or compromise assessment would sit inside that 18.0% annual revenue assumption rather than on top of it.
The earnings bridge matters just as much. Moving from a loss of US$318.7m to forecast earnings of US$196.5m asks the business to close a gap of more than half a billion dollars through higher gross margin, tighter operating spend, or both. Extra AI products like Wayfinder can help support pricing power or wallet share, but they also pull in extra R&D and integration costs, which can slow that earnings shift if spending runs ahead of customer uptake.
Analysts are effectively anchoring their 2029 view of SentinelOne on the idea that profitability could resemble the broader US software peer group. The valuation framework assumes profit margins move from deeply negative territory toward an 11.4% level, with the stock trading on a 48.1x P/E against those future earnings. That multiple is higher than the current software sector average P/E of 32.8x, so the market would need to keep rewarding this story with a premium for the thesis to hold.
There is another layer to watch. Analyst models factor in share count rising by about 2.76% each year over the next three years. For existing holders, that means any benefit from Wayfinder driven demand has to offset not just operating costs but also the effect of gradual dilution on per share metrics.
Price targets reflect this tension clearly. Consensus sits at US$19.87, with a spread from US$15.00 to US$27.00, while the recent price of US$23.11 implies the market is paying above that central analyst mark. Analysts are effectively saying the business profile they model, including revenue of US$1.7b and earnings of US$196.5m by 2029, does not fully line up with where the stock trades today.
If you map Wayfinder onto those figures, the key question becomes simple. Does SentinelOne's push into frontier AI security, including Prompt Security and GPT 5.6 Cyber, give you enough confidence in that earnings swing and revenue path to justify a premium valuation and a higher P/E than the wider software peer set?
Uncover why SentinelOne's fair value indicates a 12% potential downside to its current price, leaving little room for error.
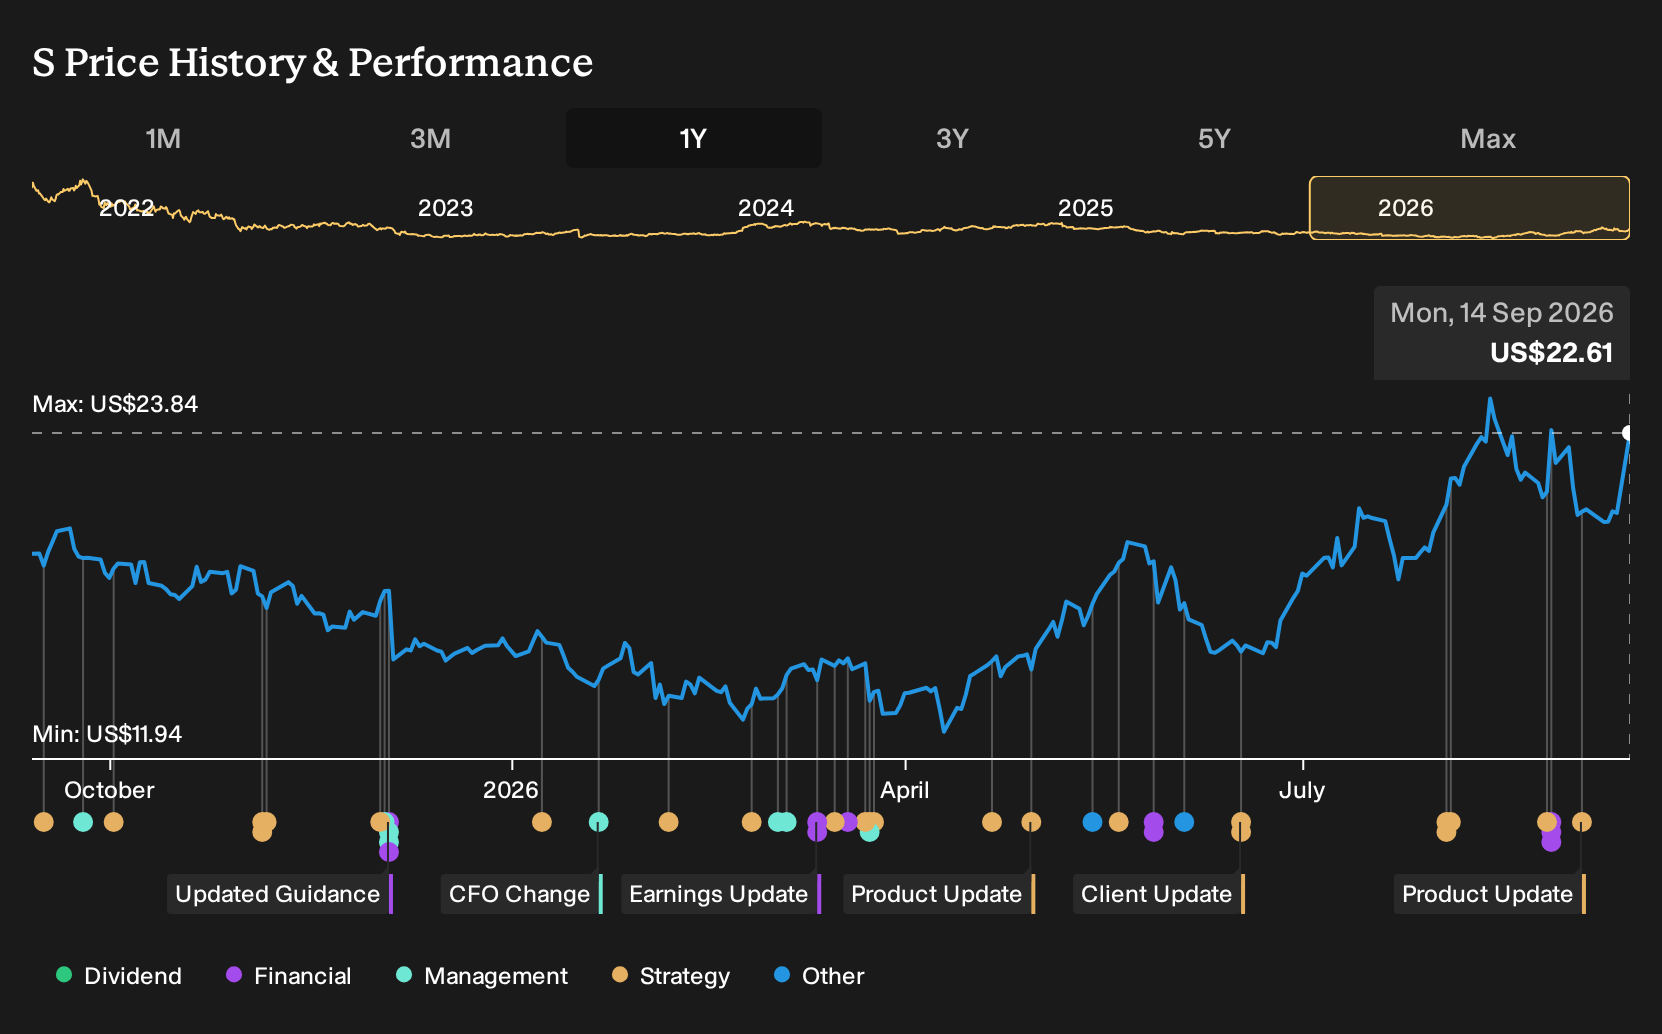
Exploring Other Perspectives
The sharpest contrast comes from how much weight you give to competition risk. While the baseline view focuses on SentinelOne using AI to deepen its platform, the most bearish analysts worry that open source tools and rival suites cap pricing power. They were already assuming 16.7% annual revenue growth to about US$1.7b and earnings of US$200.4m by 2029, before this Wayfinder news. That is a more skeptical story than consensus, and it shows how far opinions can spread. Use this new frontier AI launch as a prompt to compare these different narratives rather than accept any single forecast at face value.
Explore 4 other SentinelOne fair value estimates, including one that suggests there may be as much as 12% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your SentinelOne research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for SentinelOne. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SentinelOne's overall financial health at a glance.
Looking For More Investment Ideas Beyond SentinelOne?
If SentinelOne's frontier AI push has sharpened your appetite for research, it can help to line it up against other opportunities that match your risk profile and income needs. The Simply Wall St Screener lets you quickly filter for different types of stocks so you can build a watchlist that fits how you like to invest.
- For investors who want potential upside without stretching their risk tolerance too far, consider a curated 11 resilient stocks with low risk scores that pair resilience with measured growth potential.
- If your priority is financial strength and balance sheet quality, use the list of solid balance sheet and fundamentals (23 results) to focus on businesses with sturdier fundamentals than the average stock.
- Those hunting for under followed opportunities can scan a 15 high quality undiscovered gems that combine solid financial profiles with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com