
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
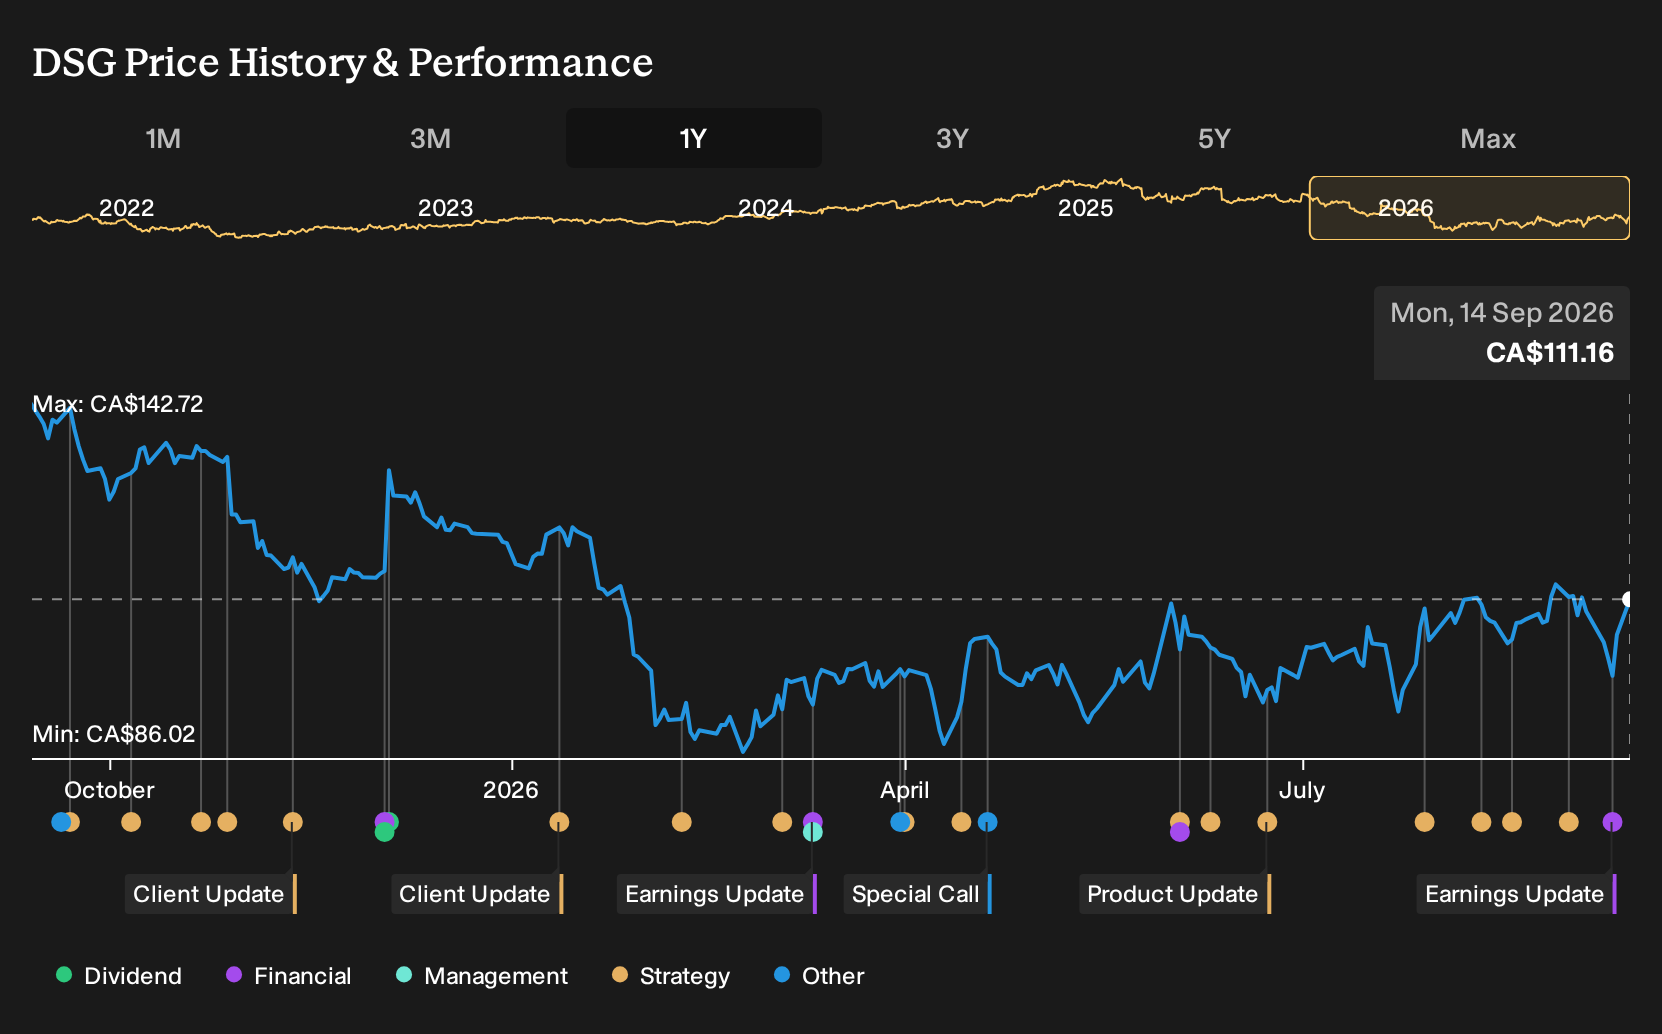
Descartes Systems Group (TSX:DSG) Is Up 5.5% What's Changed After Strong Earnings
- Descartes Systems Group reported second quarter 2026 results with sales of US$201.11 million and net income of US$50.03 million, with both revenue and earnings for the first half of the year above the prior period.
- The earnings release highlighted higher basic and diluted earnings per share from continuing operations for both the quarter and the six month period, pointing to stronger profitability on a per share basis.
- We will now look at how Descartes Systems Group's investment narrative is influenced by this stronger earnings per share performance.
Scan how Descartes Systems Group's latest earnings compare with peers by reviewing curated list of solid balance sheet and fundamentals (7 results) that have also reported recent profit strength.
Descartes Systems Group Investment Narrative Recap
To own Descartes Systems Group, you need to believe its logistics software can keep attracting customers as global trade and e commerce stay complex and highly regulated. The latest quarter backs up that thesis. Higher sales and net income, along with stronger earnings per share, suggest the platform is scaling efficiently across its logistics, customs, and trade compliance tools.
The key near term catalyst is continued adoption of Descartes Systems Group services as shippers and retailers push for more automation and visibility. The main risk is that global trade policy or transportation volumes turn choppy again, which could pressure transactional revenue. The fresh earnings beat strengthens the story, but it does not remove those external risks.
Among recent updates, the second quarter and six month earnings report ending July 31, 2026 is the most relevant for assessing catalysts. Revenue for the quarter reached US$201.11 million with net income of US$50.03 million, while basic earnings per share from continuing operations rose to US$0.58 and diluted earnings per share reached US$0.57.
For the six month period, Descartes Systems Group reported sales of US$394.73 million and net income of US$98.51 million, with basic earnings per share from continuing operations of US$1.15 and diluted earnings per share of US$1.13. These figures matter for your thesis because they test whether the firm can grow earnings while facing risks such as trade policy shifts, competition in logistics software, and reliance on acquisition driven expansion.
Descartes Systems Group is currently framed around analysts’ expectations that revenue will reach US$1.0b and earnings will be US$275.4 million by 2029, based on a projected 11.3% yearly increase in sales and a move from US$163.8 million in earnings today to that higher figure, which means an earnings uplift of about US$111.6 million over the period.
Uncover why Descartes Systems Group's fair value indicates a 15% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between US$128.28 and US$146.85 per share, so opinions already span a wide band before factoring in Descartes Systems Group’s latest profit update. When you layer on risks around trade policy, acquisition execution, and freight volumes, you can see why viewpoints differ. Consider exploring several perspectives before deciding.
Explore 2 other Descartes Systems Group fair value estimates, including one that suggests up to 32% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Descartes Systems Group research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Descartes Systems Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Descartes Systems Group's overall financial health at a glance.
Looking for more investment ideas beyond Descartes Systems Group?
Once you have formed a view on Descartes Systems Group, it can help to broaden your watchlist with other stocks that match different risk and income profiles using the Simply Wall St Screener.
- For investors who want income potential backed by hefty payouts, scan a curated pool of 2 dividend fortresses that offer higher yields than many broad market benchmarks.
- If capital preservation and steadier profiles matter more to you, look across 1 resilient stocks with low risk scores that carry lower risk scores based on their financial and business characteristics.
- For those hunting for quality companies that may still be flying under the radar, review 9 high quality undiscovered gems that pair strong fundamentals with relatively limited market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com