
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Gastech 2026 Role Just Shift Inpex's (TSE:1605) Investment Narrative?
- Gastech 2026 recently opened in Bangkok, bringing together over 50,000 delegates including ministers and executives from major energy groups such as Shell, Chevron, ExxonMobil and Inpex to discuss energy supply, investment and long term demand.
- Inpex, appearing alongside global peers at Gastech, focuses investor attention on how its LNG and low carbon project pipeline aligns with sector wide efforts to balance energy security with decarbonisation and capital discipline.
- We will now see how Inpex's role at Gastech and its focus on LNG and low carbon solutions interact with the existing investment narrative.
Scan how Inpex fits into the broader energy security theme by comparing it with 38 power grid technology and infrastructure stocks that could benefit as grids adapt to long term LNG and low carbon supply shifts.
Inpex Investment Narrative Recap
To own Inpex, you need to believe its LNG and upstream portfolio, plus new energy projects, can earn solid cash flows even if earnings forecasts point to a 3% annual decline over the next three years. The near term story is still about executing Ichthys and Abadi efficiently while keeping net profit margins, currently 22.1%, from slipping.
The key short term catalyst is progress and cost control on large LNG projects in a market that is again talking about energy security at forums like Gastech. The biggest risk remains execution and pricing pressure if LNG demand or pricing weakens. The Bangkok event itself does not materially alter that balance between risk and reward.
Recent disclosures highlight a mixed setup for Inpex. Earnings over the past year declined 1.1%, even though the business grew profits by 11.7% per year over five years and improved net margins from 20.6% to 22.1%. This is a mature producer where incremental gains rely less on volume growth and more on efficiency, tax optimisation and disciplined capital spending.
On the reward side, there is a 2.84% dividend and a P/E of 10.6x, which sits below the JP market on 13.8x and the estimated fair P/E of 10.9x. Those supports meet a more cautious outlook where earnings are expected to decline and forecast return on equity of 7.9% screens as low, so any LNG project news connected to Gastech conversation matters most for confidence in those cash flows rather than changing the fundamental thesis.
Inpex Consensus Forecasts Around Gastech 2026
Inpex's narrative projects ¥2,226.5b revenue and ¥432.7b earnings by 2029. This is based on an assumed 4.1% yearly revenue growth and an earnings increase of about ¥55.7b from ¥377.0b today.
Uncover why Inpex's fair value indicates a 9% potential upside to its current price, a discount that could close sooner than many expect.
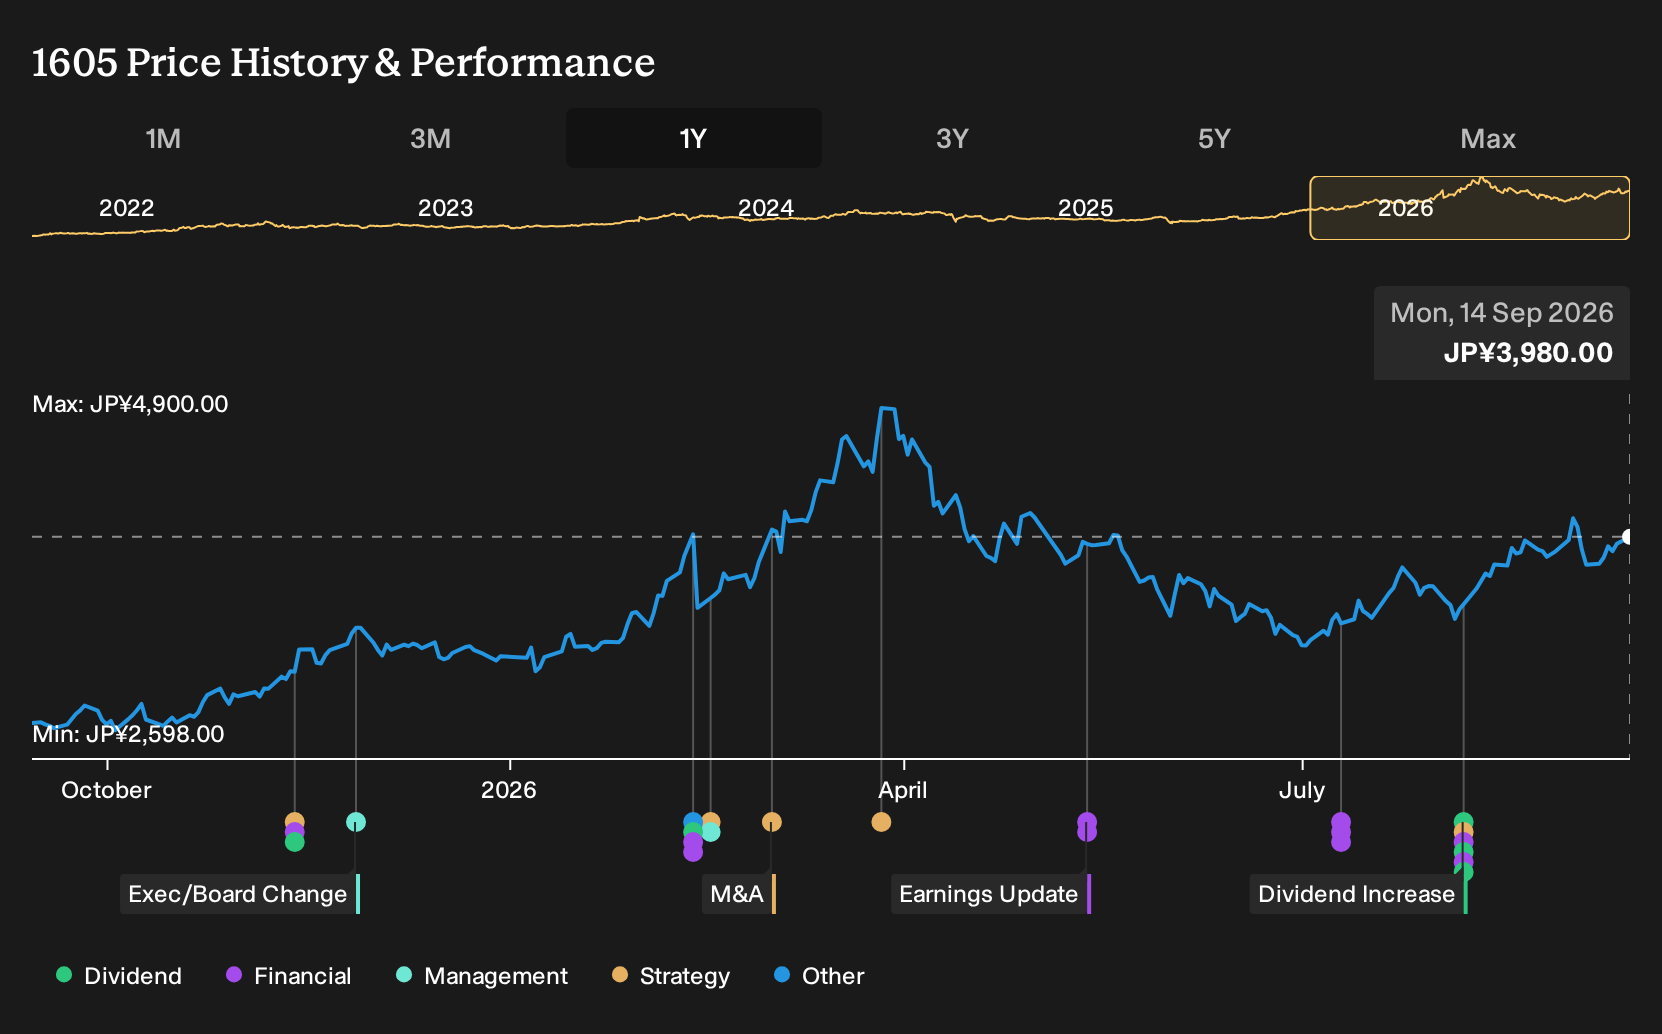
Exploring Other Perspectives
For a different angle, focus on the bullish catalyst around Inpex’s Profit Booster 500 reforms. The most optimistic analysts were already pencilling in revenue of ¥2,433.8b and earnings of ¥509.7b by 2029, well above consensus. Those views were set before Gastech 2026, so opinions may shift as fresh information lands.
Explore 2 other Inpex fair value estimates, including one that suggests as much as 21% potential upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that is truly your own.
- A great starting point for your Inpex research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Inpex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Inpex's overall financial health at a glance.
Looking For More Ideas Beyond Inpex?
If you want to cross-check Inpex against other opportunities, the Simply Wall St Screener can help you quickly scan for different types of stocks that fit your risk and income preferences.
- For investors hunting for strong balance sheets and resilient fundamentals, start with this list of solid balance sheet and fundamentals (19 results) and see which businesses have the financial backing to ride out tougher conditions.
- If capital preservation is front of mind, narrow your search to 12 resilient stocks with low risk scores that score well on stability and downside protection.
- Those looking for under-the-radar opportunities can broaden their watchlist with 74 high quality undiscovered gems where quality metrics already look compelling even if attention is still limited.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com