
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is DraftKings (DKNG) Cheap Following Its Integrity Compliance Expansion?
DraftKings expands integrity tools across sportsbook and prediction markets
DraftKings (DKNG) is rolling out Integrity Compliance 360’s full integrity and compliance suite across its sportsbook and predictions platform, creating a unified framework that covers both traditional wagering and event based prediction markets.
DraftKings’ agreement with Integrity Compliance 360 lands at a tricky moment for investors, with the share price at US$24.85 after a 7 day share price return of 3.5%, while the year to date share price return is down 30.31% and the 1 year total shareholder return is down 41.98%. Together, these figures suggest that recent interest has picked up but longer term momentum has faded.
Scan how DraftKings compares to other regulated betting and gaming players by reviewing the hand picked 15 high quality undiscovered gems that are also building out compliance heavy digital platforms.
DraftKings now trades at US$24.85 after a sharp reset and a modest recent bounce. Does that make today a cleaner entry point, or does waiting for a deeper pullback offer a better trade off on valuation risk?
Most Popular Narrative: 18.5% Overvalued
DraftKings closed at $24.85, while the most followed narrative on the stock pegs fair value at $20.97. This implies the current quote sits above that reference point and leaves less room for missteps if the business plan stalls.
Current Valuation Still Requires Strong Execution
DraftKings'' stock has declined significantly recently (-45% 1YR), reducing concerns that the company is priced for hypergrowth. However, investors are still valuing DraftKings based on the expectation that management can successfully transition the company into a highly profitable, scaled wagering platform.
See why 6 investors see DraftKings as 19% overvalued.
Result: Fair Value of $20.97 (OVERVALUED)
Still, DraftKings could surprise if prediction markets scale faster than expected, or if regulators pull back from harsher tax and advertising proposals.
Find out about the key risks to this DraftKings narrative.
Another View on DraftKings' Valuation
There is a sharp contrast between the community fair value of $20.97 and our DCF work. The SWS DCF model values DraftKings at $96.40 per share, which flags the current $24.85 quote as trading well below that future cash flow estimate. Is that a genuine margin of safety or a sign the cash flow assumptions are too generous?
Look into how the SWS DCF model arrives at its fair value.
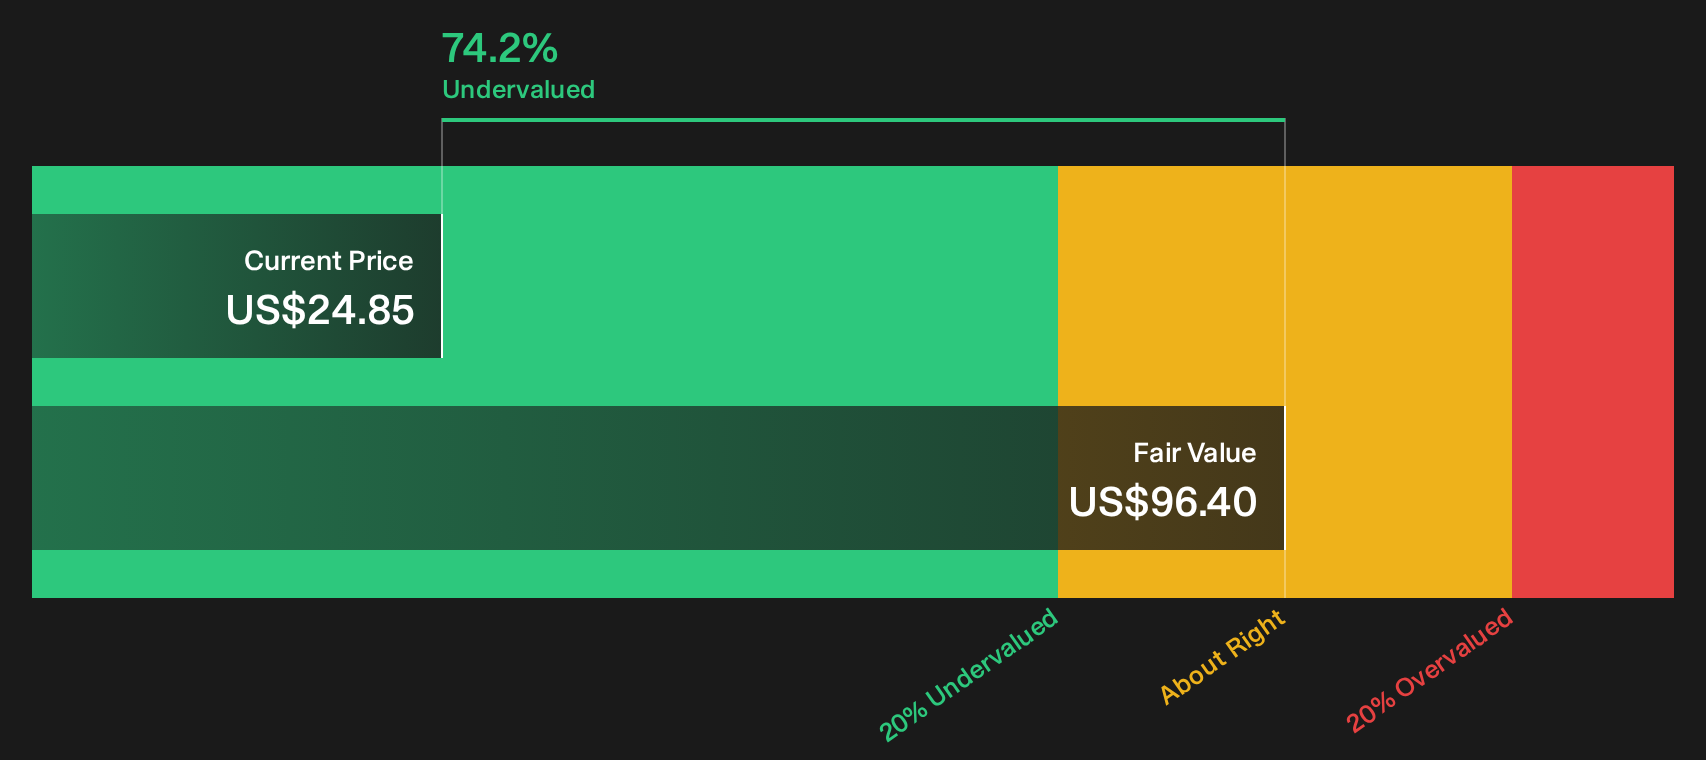
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DraftKings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around DraftKings is split, so treat this as a prompt to move quickly, test the assumptions against your own criteria, and pressure test the 3 key rewards.
Looking for more DraftKings investment ideas?
If DraftKings has you rethinking your next move, broaden your watchlist now and stress test your portfolio against fresh ideas before the market moves without you.
- Target steady compounders by scanning a curated set of companies that look underpriced relative to quality through the 35 high quality undervalued stocks.
- Strengthen your income stream by checking out potential high yield opportunities screened as 6 dividend fortresses.
- Dial down portfolio stress by focusing on defensiveness first and reviewing 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com