
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Stewart Information Services (STC) Looks Undervalued, Is The Premium P/E Already A Risk?
Stewart Information Services (STC) is on investors’ radar after recent trading left the stock at US$67.02, with returns mixed across different periods and long term performance stronger than short term moves.
For Stewart Information Services, the recent 1-day share price return of 1.18% compares with a 30-day share price return that is down 1.73%. The 3-year total shareholder return of 62.08% indicates momentum has been stronger over the longer stretch than in the past few months.
Scan beyond Stewart Information Services and size up other under-the-radar real estate and financials players with a 15 high quality undiscovered gems for your watchlist.
Stewart Information Services has shown it can compound value over multi year stretches, yet the share price has drifted this year. Does that recent softness leave the stock cheaply priced, or is it already full on valuation?
Most Popular Narrative: 19% Undervalued
Analysts following Stewart Information Services see fair value at $83 per share, compared with the recent $67.02 close, which places a lot of weight on its real estate focused earnings engine.
The company is experiencing significant growth in its Title segment, specifically in commercial services and asset classes like retail and energy, which could positively impact revenue and pretax income.
Strategic acquisitions in targeted Metropolitan Statistical Areas (MSAs) are anticipated to drive growth, increasing future revenue and earnings.
See why 2 investors see Stewart Information Services as 19% undervalued.
Result: Fair Value of $83 (UNDERVALUED)
Still, the Stewart Information Services story can break if housing activity stays weak for longer and higher data and employee costs continue to squeeze profitability.
Find out about the key risks to this Stewart Information Services narrative.
Another View On Stewart Information Services Valuation
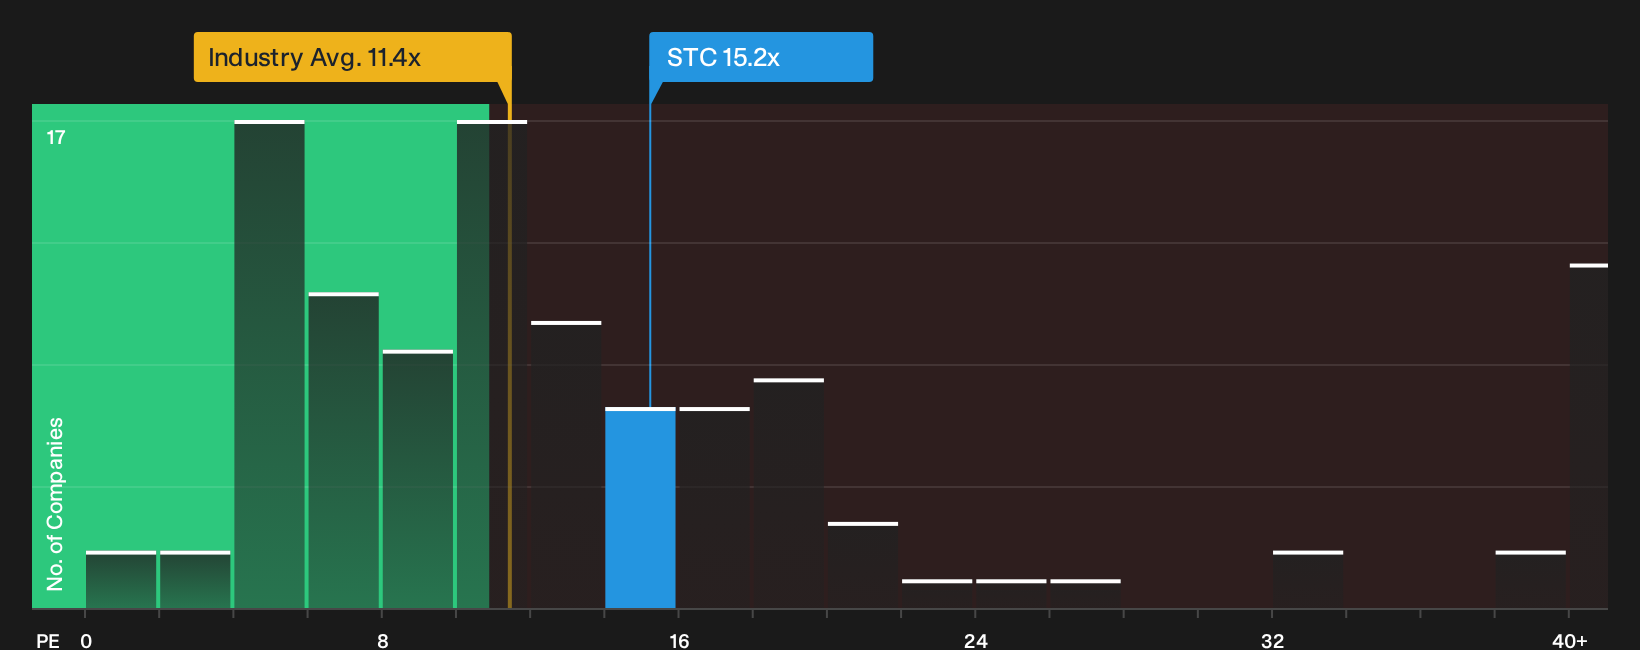
Analysts label Stewart Information Services as undervalued at a fair value of $83, yet the market is already paying a P/E of 15.2x compared with 11.1x for the wider US insurance group and 11.2x for closer peers.
The fair ratio for Stewart Information Services sits at 13.8x, which is lower than the current multiple and suggests less room for error if earnings disappoint. For investors comparing options across the sector, that gap can matter more than a single price target.
To see how this relative pricing stacks up alongside peers and where the fair ratio could shift next, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of optimism and caution around Stewart Information Services feels familiar, you are not alone. Move quickly and review the numbers yourself before sentiment shifts. To see which positives others are focusing on, review the 5 key rewards.
Looking for more investment ideas beyond Stewart Information Services?
If Stewart Information Services has sharpened your thinking, do not stop there. Use the screener to uncover fresh setups before other investors crowd in.
- Target resilient balance sheets and steady fundamentals by scanning a list of solid balance sheet and fundamentals (23 results) that can handle tougher conditions without forcing rushed decisions.
- Hunt for quality at a discount with a focused look at 35 high quality undervalued stocks that may offer more appealing entry points than headline tickers.
- Prioritize stability and income potential by reviewing a 6 dividend fortresses that screens for higher yielding companies with robust payout profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com