
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How New Energy Saving IC Will Impact Power Integrations Stock
- Power Integrations recently introduced its CAPZero-4 X-capacitor discharge ICs, targeting industrial and consumer gear that must meet very tight standby power requirements, support wide temperature ranges, and comply with multiple global safety standards.
- The new CAPZero-4 family is pin compatible with earlier CAPZero parts, which lets existing customers upgrade to lower standby losses without a redesign and can limit engineering time and qualification costs.
- We will now look at how the investment narrative for Power Integrations could be shaped by CAPZero-4's focus on ultra low standby power performance.
Scan beyond Power Integrations and see how other efficiency driven chipmakers are positioned with our hand picked 60 AI infrastructure stocks as interest in low standby power solutions increases across data centers and connected devices.
Power Integrations Investment Narrative Recap
For a shareholder in Power Integrations, the core belief is that demand for high efficiency power conversion keeps broadening across appliances, industrial gear, EVs and data infrastructure. CAPZero-4 fits that story because it tightens standby power performance within existing sockets, which supports the case that the portfolio can stay relevant as efficiency rules tighten.
In the near term, the more pressing swing factors still appear tied to appliance cyclicality, tariffs and the slow ramp in newer markets like automotive and AI data centers. CAPZero-4 helps the product mix, but it does not directly change concentration in consumer appliances or address approval risks with large computing customers.
The CAPZero-4 launch matters because it focuses on efficiency at the low power end while Power Integrations is also pushing high voltage GaN for EVs and AI data centers. That pairing gives the product set exposure to both cost sensitive appliances and premium density applications, which can be useful if any one segment stalls.
Investors watching catalysts may see CAPZero-4 as another proof point that the firm is still iterating on long running franchises. The bigger operational question is how consistently this type of product update converts into design wins in geographies affected by tariffs, and whether it provides time for higher value segments to contribute more of total revenue.
Power Integrations' narrative projects revenues of $690.7 million and earnings of $160.0 million by 2029, which implies forecast revenue growth of 15.4% per year and an earnings increase of about $134.9 million from earnings of $25.1 million today.
Uncover why Power Integrations' fair value indicates a 65% potential upside to its current price that may not last much longer.
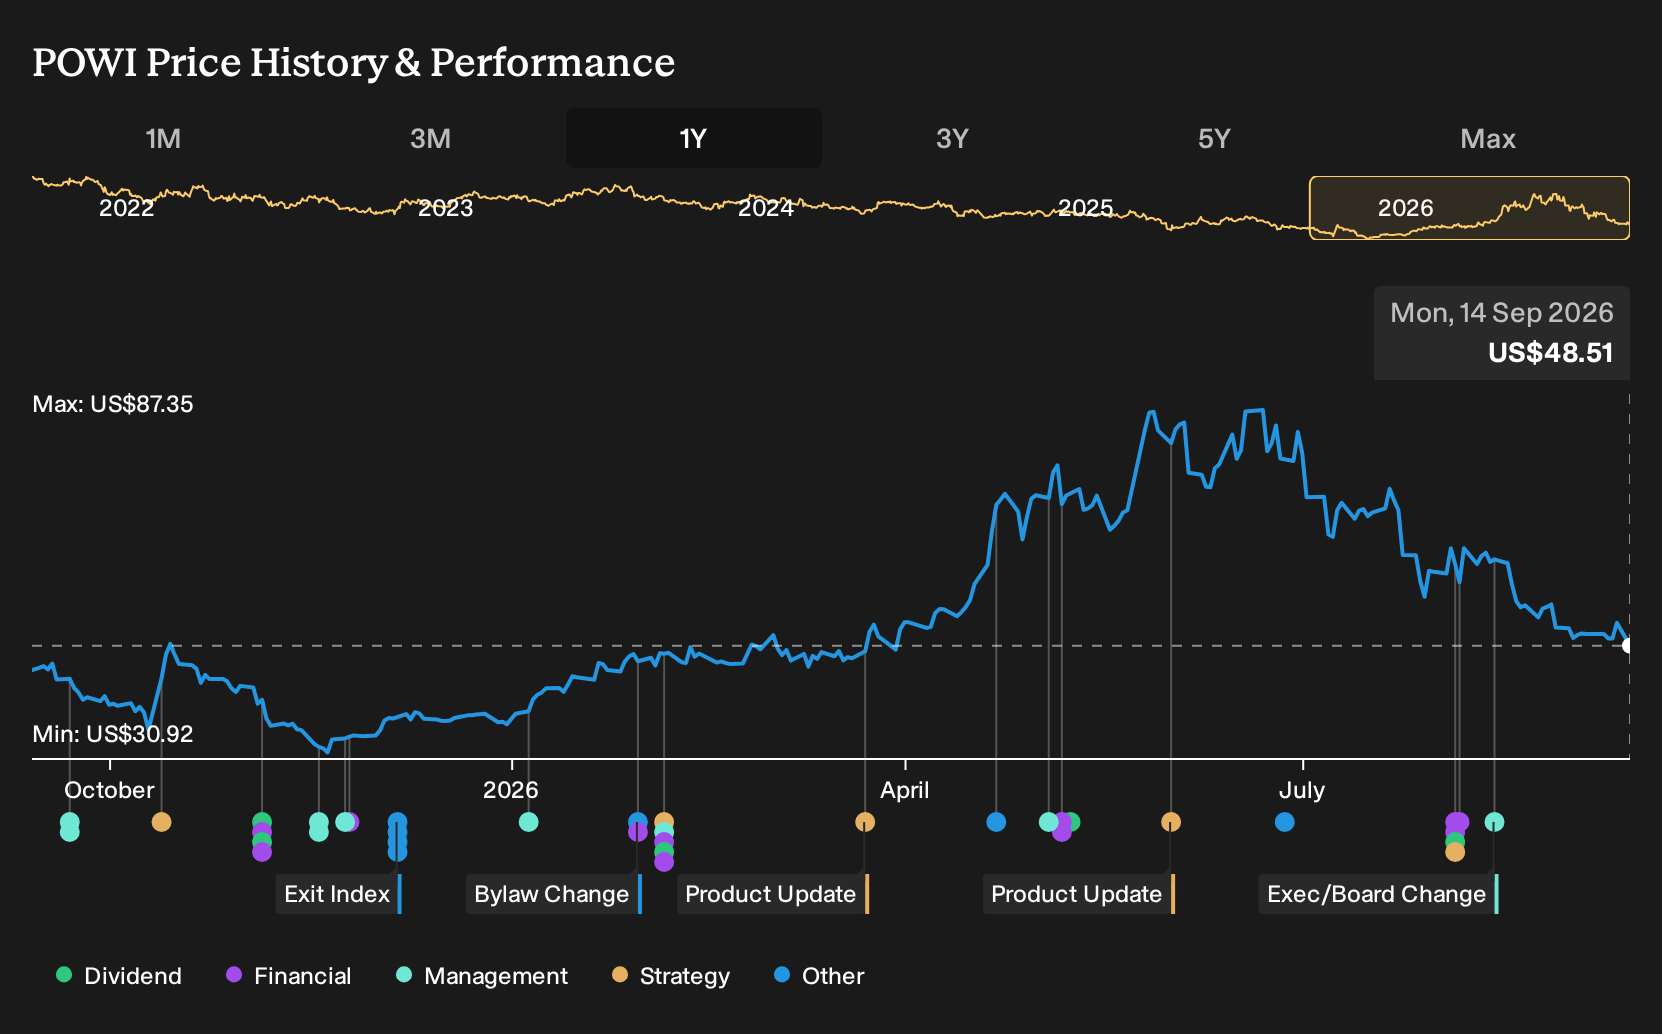
Exploring Other Perspectives
One alternate take on Power Integrations leans heavily into the CAPZero-4 style efficiency story and presents a much brighter picture. The most optimistic analysts were already modeling revenue of $733.6 million and earnings of $165.7 million by 2029. You can treat those as an upper bound and explore how fresh product news might reshape expectations.
Explore 3 other Power Integrations fair value estimates, including one that suggests up to 75% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Power Integrations research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Power Integrations. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Power Integrations' overall financial health at a glance.
Looking for more investment ideas beyond Power Integrations?
If you want to stress test your thesis on Power Integrations against other opportunities, the Simply Wall St Screener lets you filter for different styles of businesses and compare them side by side.
- For investors who want growth potential at lower absolute share prices, scan through 3 elite penny stocks with strong financials that already show meaningful underlying strength.
- If you are more interested in companies where price and business quality look out of sync, review a curated 35 high quality undervalued stocks that may warrant a closer look.
- For a focus on balance sheet resilience and cleaner fundamentals, start with a list of solid balance sheet and fundamentals (23 results) that can help anchor the more speculative parts of a portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com