
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Dividend Raise Might Change The Case For Investing In CNB Financial Stock (CCNE)
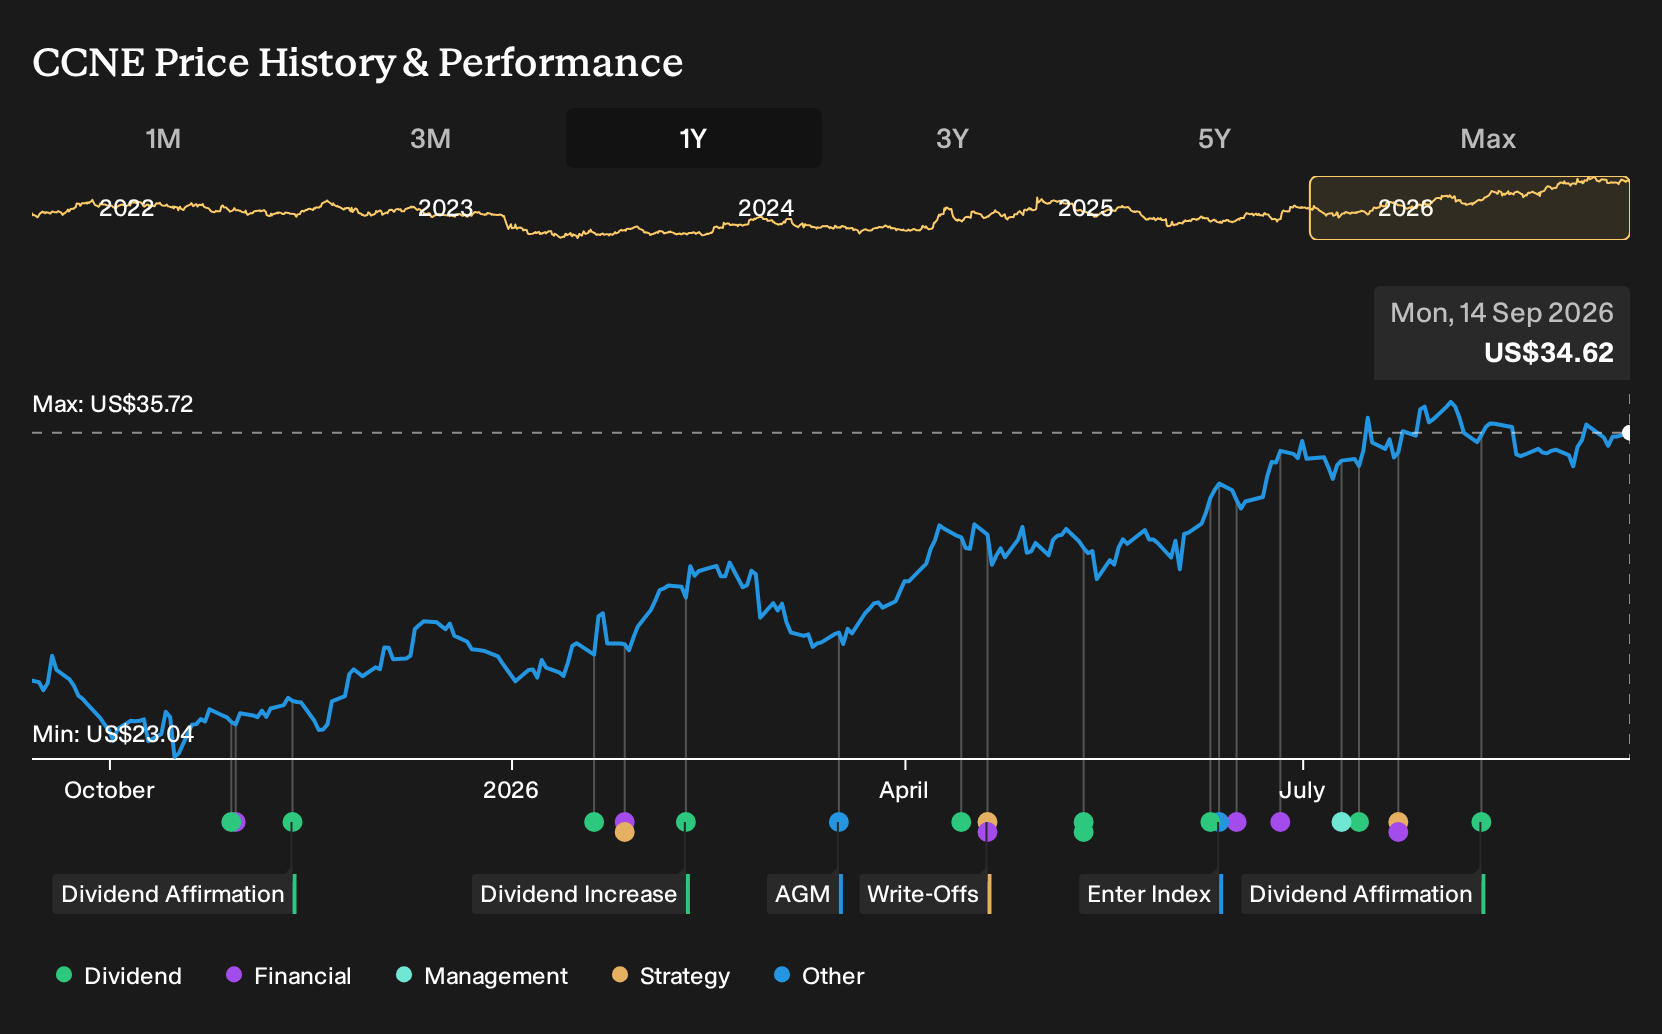
- CNB Financial declared a quarterly dividend of US$0.19 per share, giving the stock a 2.2% yield and reflecting a 5.6% annualized increase from the prior year with a current payout ratio of 22%.
- The combination of measured dividend growth and expectations for 20.27% earnings expansion in fiscal 2026 highlights management’s stated focus on supporting shareholder income while retaining significant capital within the business.
- We will now look at how CNB Financial's higher dividend and earnings outlook could influence its broader investment narrative.
Extend the income story beyond CNB Financial by scanning a curated set of bank stocks that combine dividends with solid balance sheets through our list of solid balance sheet and fundamentals (23 results)
CNB Financial Investment Narrative Recap
To own CNB Financial, you need to be comfortable with a regional bank that focuses on commercial and industrial lending and treasury management while keeping a close grip on credit quality and costs. The dividend news does not fundamentally change that story. It reinforces that management currently feels earnings and capital are sufficient to support regular cash returns.
The main near term swing factor is still how the loan book and funding mix behave as CNB Financial expands across its four state footprint. A sharper slowdown in regional business conditions or tougher deposit competition would matter more to earnings than a 5.6% higher annual dividend.
The new US$0.19 per share dividend, with a 2.2% yield and a 22% payout ratio, is the announcement that ties most closely to this story. It comes on top of earnings that have recently grown and forecasts for further profit expansion, so income-focused investors have a clearer view of how cash returns are currently supported by operations.
With revenue projected to be broadly flat over the next few years and earnings expected to do more of the work, attention remains on execution around loan growth, credit quality and deposit costs. The relatively low payout ratio gives CNB Financial room to fund these priorities while still providing a cash yield for shareholders who care about regular income.
CNB Financial's outlook projects US$332.6 million in revenue and US$133.6 million in earnings by 2029. This suggests essentially flat yearly revenue growth and an earnings increase of about US$42.6 million from US$91.0 million today.
Uncover how CNB Financial's fair value indicates an 8% potential upside to its current price that could narrow quickly if sentiment around CNB Financial shifts.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$37.50 to about US$78.79 per share, so opinions on CNB Financial are wide apart. Consider both perspectives. C&I loan growth at an 18.2% annualized rate and ESSA integration gains could either justify optimism or magnify future credit and cost risks.
Explore 2 other CNB Financial fair value estimates, including one that suggests it could be worth just $37.50.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CNB Financial research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for CNB Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CNB Financial's overall financial health at a glance.
Looking for more investment ideas beyond CNB Financial?
Once you have formed a view on CNB Financial, it can help to compare it with other opportunities that fit your income, quality, or risk profile. The Simply Wall St Screener lets you filter for traits that match how you like to invest instead of relying on headlines alone.
- If capital preservation and steadier businesses matter most to you, start with a 11 resilient stocks with low risk scores that have historically shown more resilient characteristics through different conditions.
- If you are hunting for income ideas, scan a curated set of companies offering stronger yields and balance sheet support through our 6 dividend fortresses.
- If you want to widen the search to under-followed opportunities, consider a 15 high quality undiscovered gems that pair solid fundamentals with less crowd attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com