
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
EVERTEC (EVTC) Following A Recent Pullback Has Its Undervalued Narrative Back In Focus
EVERTEC (EVTC) drew investor attention after its recent share move, with the price closing at $29.33. The payment processor’s mixed return pattern over the past year now sits in sharper focus.
Recent trading tells a mixed story for EVERTEC. The 7 day share price return is down 3.36% and the 30 day move is down 7.10%, while a 90 day share price gain of 7.75% alongside a 1 year total shareholder return decline of 10.77% points to momentum that has picked up in the short run but still trails over longer periods.
Scan beyond EVERTEC and explore other payment and fintech stocks with compressed valuations and improving trends using our hand picked 35 high quality undervalued stocks list.
Bulls view EVERTEC’s recent pullback, alongside improving revenue and net income trends, as a mismatch. Bears point to the extended decline in multi‑year returns. The key question is which side the current valuation supports next.
Most Popular Narrative: 18% Undervalued
EVERTEC’s most followed narrative pegs fair value at $35.60, above the latest $29.33 close. This puts the focus on what might support that gap.
Structural tailwinds from expanding e-commerce and regulatory initiatives that promote financial inclusion in both the Caribbean and Latin America are enlarging Evertec's addressable market, likely translating to sustained top-line growth and recurring revenue streams.
See why 2 investors see EVERTEC as 18% undervalued.
Result: Fair Value of $35.60 (UNDERVALUED)
Still, the EVERTEC story hinges on a few pressure points, including heavy dependence on key clients and ongoing currency swings across its Latin American footprint.
Find out about the key risks to this EVERTEC narrative.
Another View On EVERTEC’s Valuation
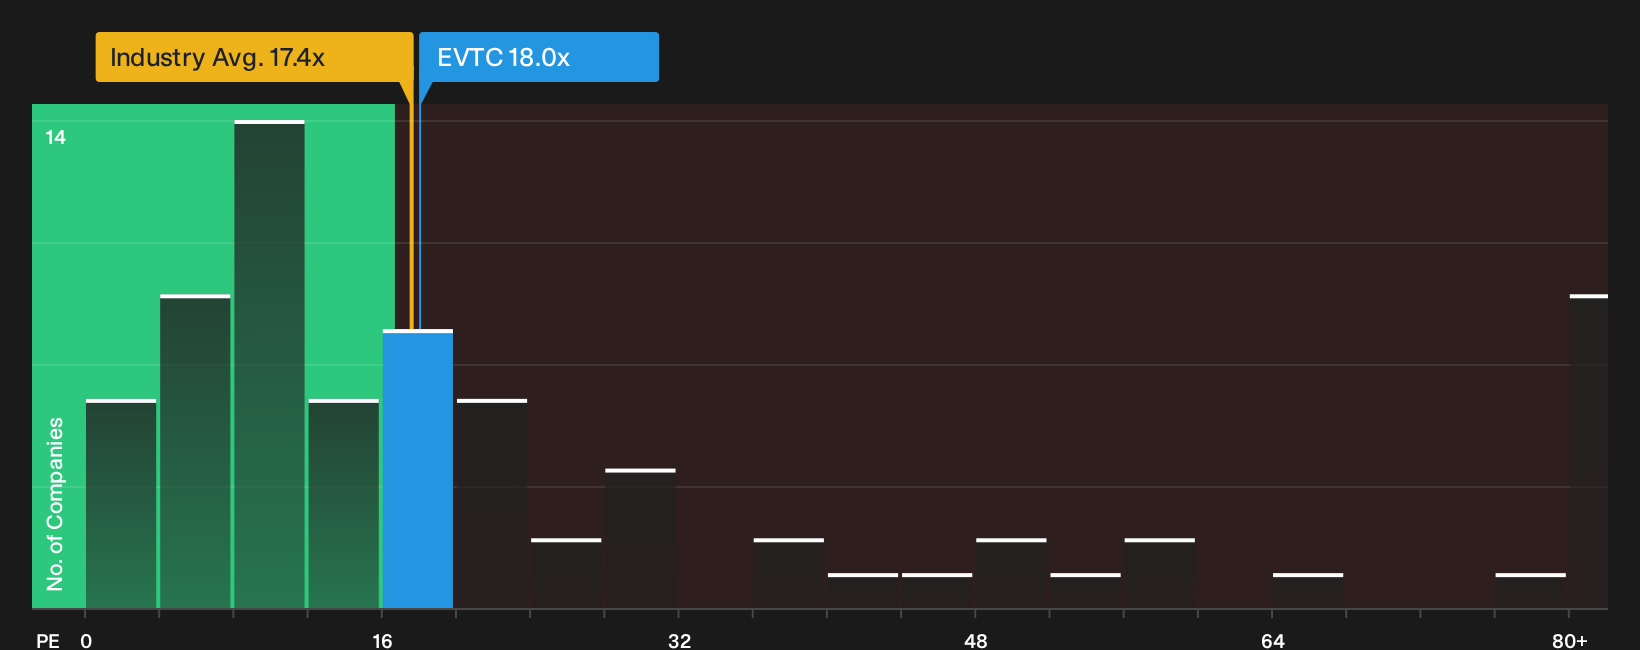
The earlier argument leans on fair value estimates that frame EVERTEC as undervalued. A simple P/E check lands in a different place. The share price trades on roughly 18x earnings, slightly above the US Diversified Financial industry at 17.6x and above a fair ratio of 17.1x. That kind of premium hints at less margin for error than the discount story suggests. This raises the question of which signal you put more weight on.
For a closer look at how this earnings multiple stacks up against peers and that 17.1x fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on EVERTEC’s valuation story can be useful if you test them against your own expectations. Consider reviewing both the bullish and cautious arguments and compare them carefully with the 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond EVERTEC?
Do not stop at EVERTEC. Use this momentum to refresh your watchlist with fresh ideas that match the way you like to invest.
- Target resilient balance sheets and steadier ride potential by reviewing a curated list of solid balance sheet and fundamentals (23 results) that filters for financial strength and durability.
- Hunt for mispriced quality by scanning the hand picked 35 high quality undervalued stocks that combines fundamentals with compressed valuations before attention fully returns.
- Build a pipeline of future watchlist candidates by checking a focused 15 high quality undiscovered gems where strong fundamentals have not yet attracted wide coverage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com