
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Loblaw Companies (TSX:L) Ramps Up 2026 Spending On A Valuation Narrative In Focus
Loblaw Companies (TSX:L) is stepping up capital spending for the rest of 2026, allocating about CA$1.2b to new and refurbished grocery stores, pharmacies, and trial formats aimed at meeting rising demand for discount-focused options.
The latest capital plan lands after a mixed stretch for the stock, with the share price at CA$63.05 and a small 1-day share price gain of 2.89% but a 90-day share price return that has slipped 2.82% as investors reassess execution risk and timing. Over a longer horizon the picture is very different, with Loblaw Companies delivering a 1-year total shareholder return of 17.43% and a 5-year total shareholder return of 213.56%. This suggests momentum has been building for patient holders even as short-term moves stay more muted.
Scan how Loblaw Companies stacks up against other retailers putting serious money into expansion by reviewing the hand picked list of solid balance sheet and fundamentals (7 results)
After a long run of strong total returns and a fresh round of heavy spending on stores and pharmacies, does Loblaw Companies still offer enough upside to justify the risk at around CA$63, or has the easy money already been made?
Most Popular Narrative: 8% Undervalued
Loblaw Companies is trading at CA$63.05 against a widely followed fair value estimate of CA$68.80, which frames the current capital spend and earnings profile as supporting a small valuation gap rather than a big dislocation.
Ongoing investments in AI-driven supply chain optimization and retail automation are reducing logistics, inventory, and labor costs, directly benefiting gross and operating margins over time.
Rapid digital transformation through PC Optimum loyalty and personalized e-commerce offerings increases customer engagement, basket size, and data-driven upselling, supporting both same-store sales and higher earnings per share.
See why 48 investors see Loblaw Companies as 8% undervalued.
Result: Fair Value of CA$68.80 (UNDERVALUED)
Still, Loblaw Companies faces pressure from tighter food price scrutiny and rising online competition, either of which could challenge the perception that the company is currently undervalued.
Find out about the key risks to this Loblaw Companies narrative.
Another View: What Loblaw Companies' P/E Is Telling You
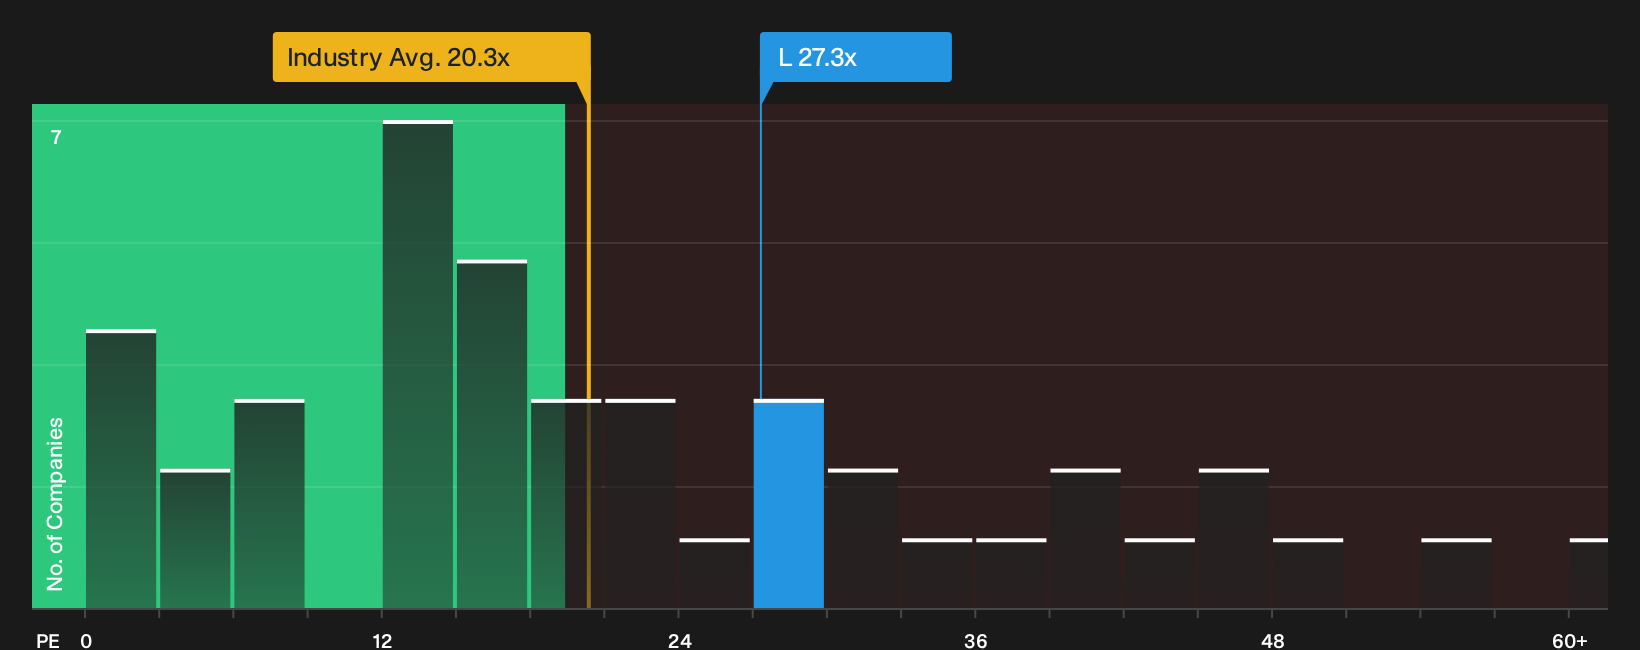
Most of the fair value debate around Loblaw Companies leans on cash flow and analyst targets. The simple earnings multiple presents a more direct perspective. The stock trades at a P/E of 27.3x versus a North American Consumer Retailing industry average of 19.4x and a peer average of 32.5x, while the fair ratio is 29.9x. That mix of slightly below fair ratio, above industry and below peer group leaves a narrow margin for error. If growth or pricing power disappoint, how much room is there before the multiple starts to compress?
For a closer look at how current pricing stacks up against earnings expectations and risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Questioning whether the mixed signals around Loblaw Companies really add up to a clear verdict right now? Move quickly, review the full picture of upside and downside, then anchor your own stance with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Loblaw Companies?
If you feel the Loblaw Companies story is only one piece of your portfolio puzzle, use the Simply Wall Street Screener to pressure test fresh ideas fast.
- Target resilient compounding by reviewing the 1 resilient stocks with low risk scores that aim to keep portfolio swings in check.
- Hunt for quality at a discount and scan the 3 high quality undervalued stocks that align with your return and risk preferences.
- Stack potential income streams by lining up the 2 dividend fortresses that might help anchor total returns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com