
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Constellation Software (TSX:CSU) Strong Revenue Growth
- Constellation Software recently reported 17.7% revenue growth, which pointed to solid demand across its portfolio of vertical market software businesses.
- The strong top line result reinforced how Constellation Software’s broad base of mission critical products can help steady performance even when individual units face pressure.
- We will now explore how Constellation Software’s 17.7% revenue growth might influence its investment narrative, particularly in areas such as durability, reinvestment and AI execution.
Scan other potential compounders showing similar resilience by reviewing the hand picked 9 high quality undiscovered gems that echo Constellation Software’s mix of durable demand and reinvestment potential.
Constellation Software Investment Narrative Recap
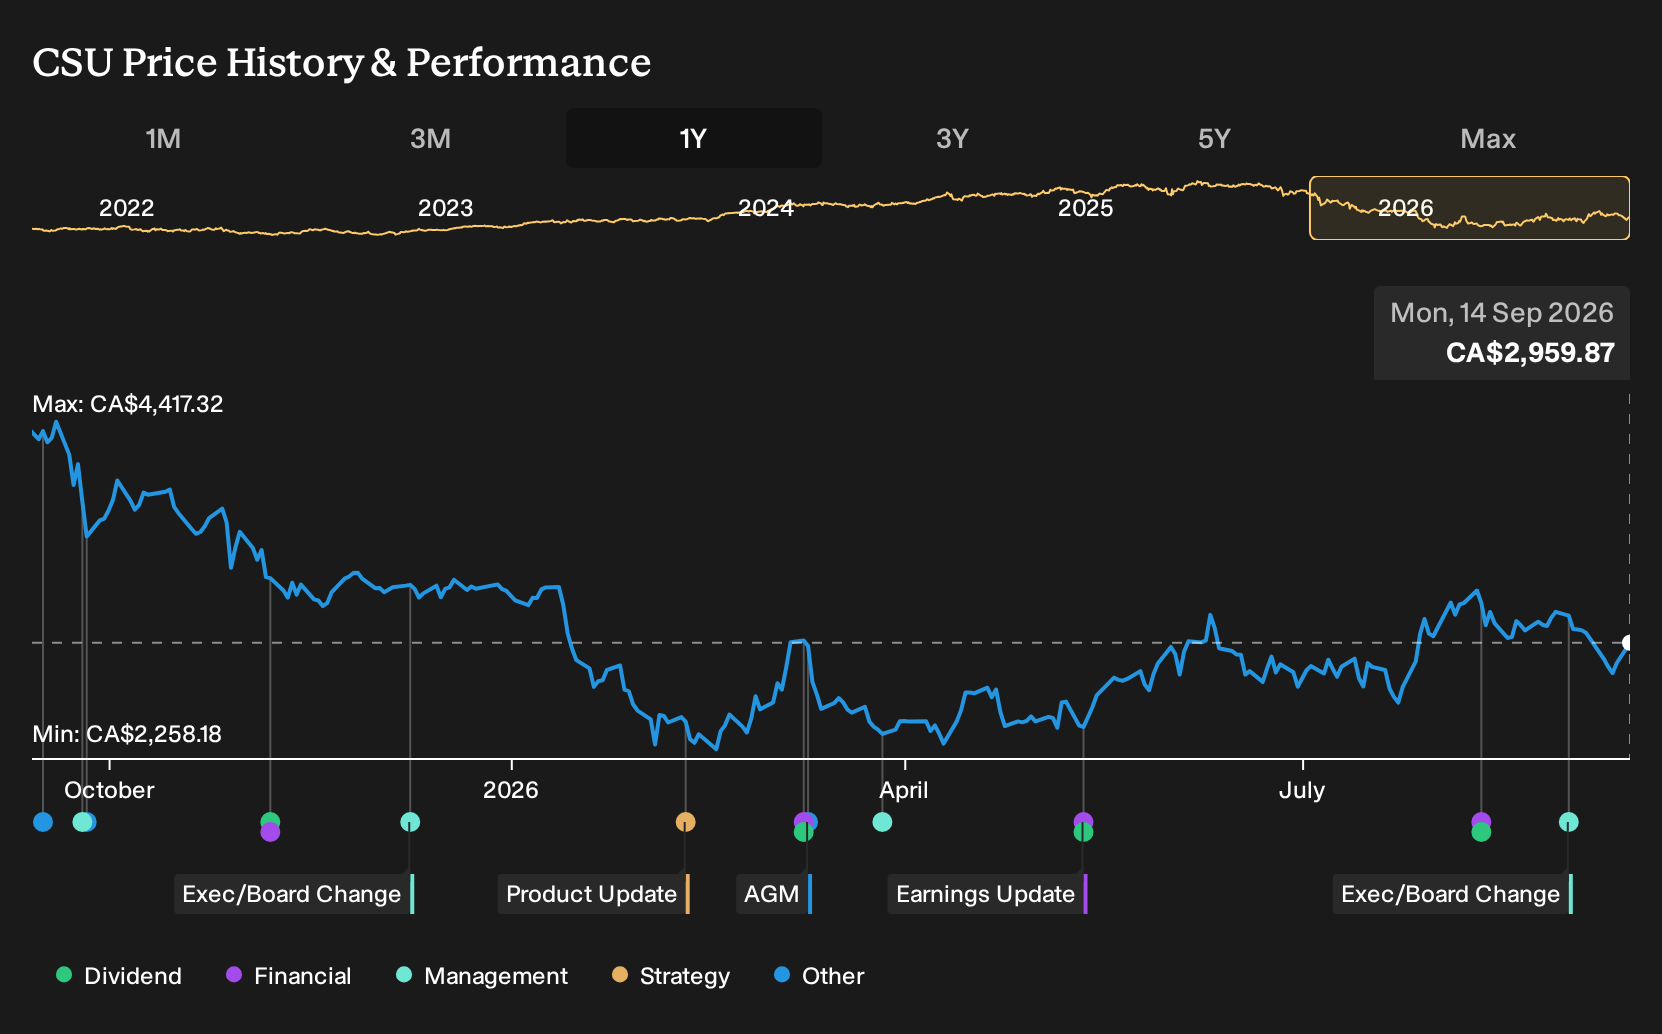
To own Constellation Software, you need to believe that a portfolio of mission critical vertical software, combined with disciplined capital deployment and AI heavy product work, can keep the business compounding through different conditions. The recent 17.7% revenue growth and 5.2% share price move support that narrative, but do not fundamentally change it.
The key near term catalyst is execution on AI augmented development and cross-portfolio knowledge sharing so that new modules and features translate into higher customer spend. The biggest risk remains misallocated capital, whether through high priced acquisitions or Permanent Engaged Minority positions that under earn, especially given the firm’s high debt levels.
Among the recent items, the most relevant piece of context for this move in Constellation Software is that analysts currently expect earnings to grow about 14.9% per year and revenue about 12.7% per year, ahead of the broader Canadian market. The latest 17.7% revenue result sits against those expectations and keeps attention on whether that kind of compounding is sustainable.
This matters for the main catalysts. If AI augmented coding and tighter capital allocation support that type of earnings expansion, then the current discount of about 33% to the average analyst price target and to a DCF based fair value estimate of CA$5,841.53 become more interesting. If acquisitions or minority stakes underperform, that gap could simply reflect the risk investors are already pricing in.
What Constellation Software’s Analyst Forecasts Really Assume
Constellation Software's narrative projects revenue of $19.1b and earnings of $1.8b by 2029, based on analyst modelling that builds off the latest reported results and AI related execution plans.
Analysts are assuming 14.8% yearly revenue growth over the next few years and see earnings moving from $961.0m today to $1.8b by 2029. This would be an increase of about $839m in profit on their central case.
Uncover why Constellation Software's fair value indicates a 32% potential upside to its current price, before momentum around Constellation Software’s compounding story closes that gap.
Exploring Other Perspectives
You are not the only one rethinking Constellation Software after a 17.7% revenue print. The most optimistic analysts already pencilled in revenue of about $20.0b and earnings of $2.3b by 2029, assuming AI efforts speed up both product output and monetization. Those views came before this update, so opinions may shift; be prepared to compare several narratives rather than relying on just one.
Explore 14 other Constellation Software fair value estimates, including one that suggests as much as 97% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Constellation Software research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Constellation Software. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Constellation Software's overall financial health at a glance.
Looking for more investment ideas beyond Constellation Software?
Once the Constellation Software thesis is clear in your mind, it can help to compare it with a few very different business profiles so you can see where the risk and return trade offs really sit.
- For investors who want potential upside without accepting the weakest balance sheets, scan a 3 elite penny stocks with strong financials that filters for smaller companies with financials that can withstand tougher conditions.
- If resilience and capital preservation matter most to you, review a 1 resilient stocks with low risk scores that highlights businesses with fewer red flags in their fundamentals.
- When income is a priority and you prefer cash in hand, check a 2 dividend fortresses that focuses on companies offering higher yields alongside underlying business support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com