
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Quality Push At Humana (HUM) Has Changed Its Investment Story
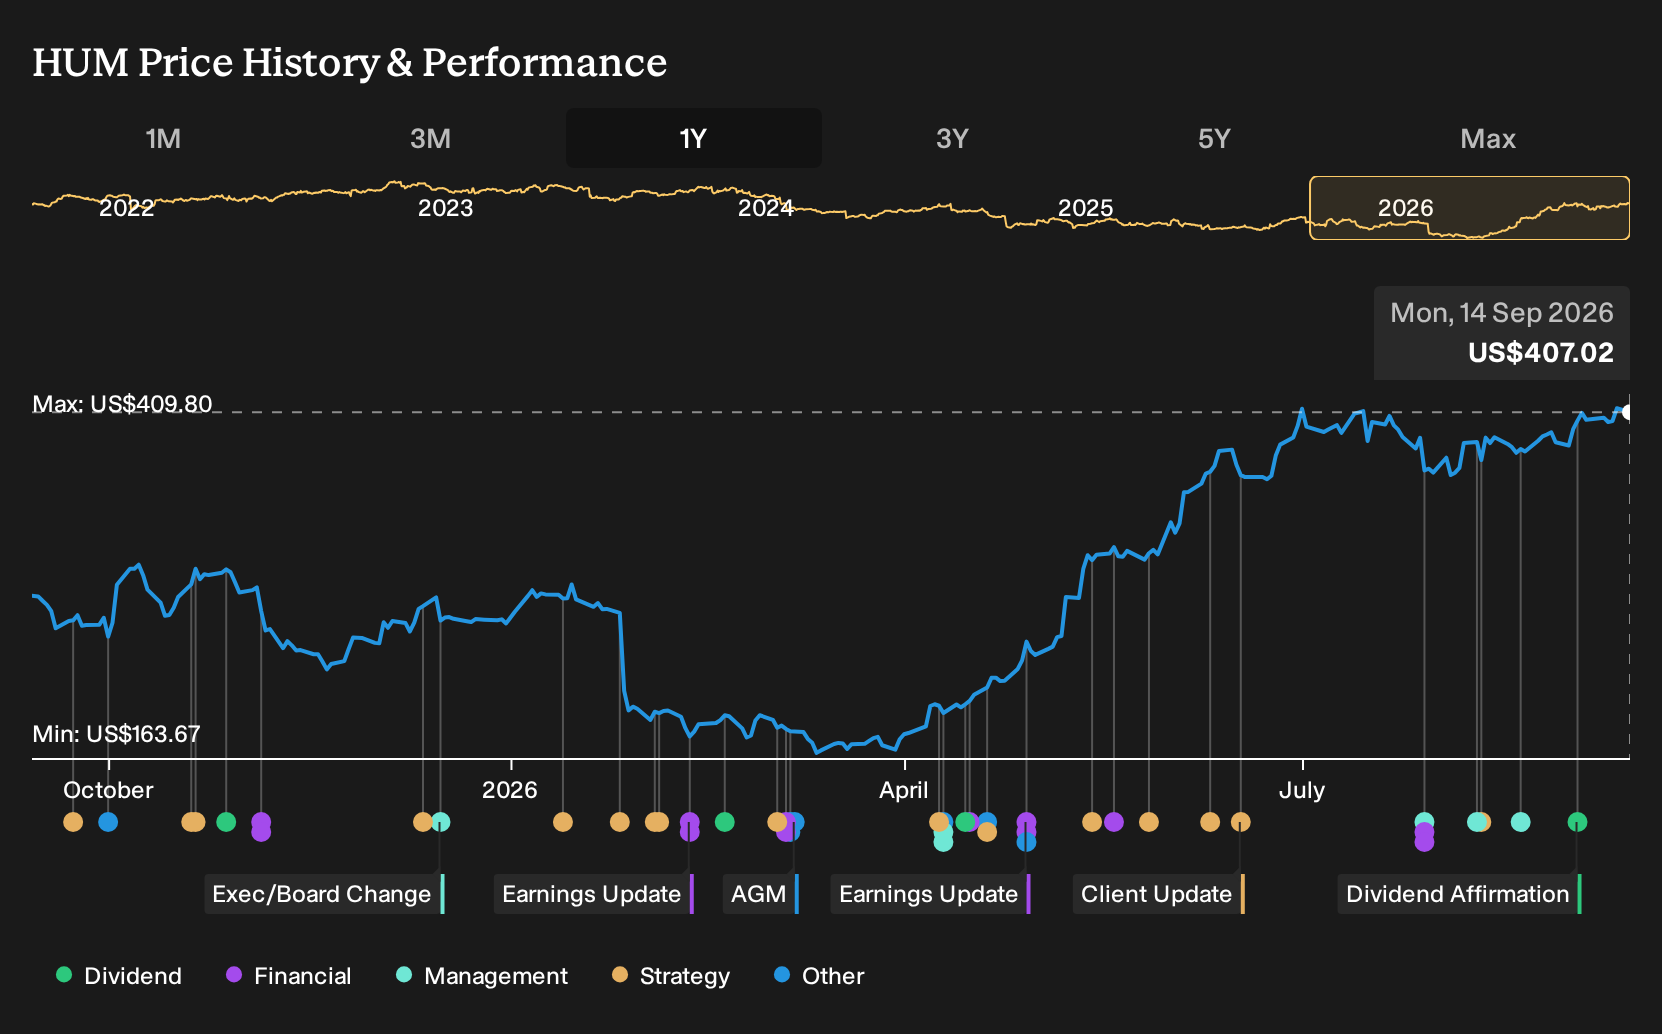
- Humana's board previously approved a cash dividend of $0.885 per share, scheduled for payment on November 27, 2026 to stockholders of record on October 30, 2026.
- The payout lands while Humana works to offset expected 2026 profit pressure from weak Medicare Advantage Star Ratings through pharmacy integration and the use of quality vendors such as Counterpart Health.
- We will examine how Humana's investment narrative is influenced by its quality initiatives as it maintains a cash dividend of $0.885 per share.
Scan how Humana’s dividend story compares with other income-focused opportunities by reviewing our curated list of 6 dividend fortresses in the current market.
Humana Investment Narrative Recap
To own Humana, you need to be comfortable with a health insurer that leans heavily on Medicare Advantage, value based care through CenterWell, and tight cost control. The immediate swing factor is how well Humana can blunt the expected US$3.5b profit hit tied to weak 2026 Star Ratings through pharmacy integration and quality programs.
The dividend affirmation at US$0.885 per share is, on its own, not a major swing item for the thesis. The bigger near term risk remains pressure on medical cost trends and any further disruption from coding, reimbursement or litigation around Star Ratings that could strain already thin 0.9% net margins.
The most relevant piece of context for this dividend decision is Humana’s push into integrated specialty pharmacy and lower drug cost models. Management is tying member engagement, medication adherence and coordinated pharmacy care together, which aims to support more stable medical cost ratios and help offset quality related funding pressure.
Counterpart Health’s role in closing HEDIS gaps and supporting better clinical quality for PPO members fits directly into that effort. Execution on these quality and pharmacy initiatives will influence whether Humana can meaningfully reduce the impact of weaker 2026 Star Ratings on earnings volatility, while maintaining enough cash flow flexibility to keep funding dividends and growth projects.
Humana Earnings Path Behind the Dividend
Humana's long term story that sits behind a steady US$0.885 per share dividend is built on analysts expecting the business to compound revenue at 8.5% per year and expand margins from 0.9% to 1.8% over the next three years. The earnings bridge is sizeable in dollar terms. Consensus points to net income rising from US$1.3b today to US$3.4b by 2029, with some analysts seeing as much as US$4.3b and others closer to US$2.6b, which shows how sensitive the outcome is to execution on quality, pharmacy integration and Stars recovery.
On those projections, analysts see Humana generating US$186.1b of revenue and US$3.4b of earnings by 2029. That profile implies 8.5% yearly revenue growth and an earnings increase of about US$2.1b from current earnings of US$1.3b.
Uncover how Humana's fair value indicates a 3% potential upside to its current price before that discount feels less comfortable.
Exploring Other Perspectives
One alternate view leans on Humana’s Medicare Advantage and CenterWell expansion as a powerful long term tailwind. The most optimistic analysts were penciling in revenue of US$207.8b and earnings of US$4.2b by 2029 before this dividend news. That is far above consensus, so it is worth exploring how those forecasts might shift.
Explore 5 other Humana fair value estimates, including one that suggests potential upside of as much as 149% from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Humana research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Humana. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Humana's overall financial health at a glance.
Looking For More Ideas Beyond Humana?
Once you have formed a view on Humana, it can help to widen the search and line it up against other opportunities with different risk and income profiles.
Use the Simply Wall St Screener to find other stocks that fit your style. A few angles to consider are:
- If capital preservation and steady fundamentals matter most to you, check out our 11 resilient stocks with low risk scores that may appeal to more cautious investors.
- For those hunting for mispriced quality, review a focused 35 high quality undervalued stocks that could highlight candidates for deeper research.
- If you enjoy finding early stories before they are widely followed, spend time with a curated 15 high quality undiscovered gems that emphasises strong underlying business quality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com