
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Undervalued Small Caps With Insider Action To Watch In September 2026
Over the last 7 days, the United States market has experienced a 1.5% drop, yet it has risen by 13% over the past year with earnings forecasted to grow by 17% annually. In this dynamic environment, identifying small-cap stocks that are perceived as undervalued and exhibit insider activity can be crucial for investors looking to capitalize on potential growth opportunities.
Top 10 Undervalued Small Caps With Insider Buying In The United States
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Cardinal Infrastructure Group | NA | 1.0x | 31.21% | ★★★★★★ |
| Regional Management | 6.5x | 0.5x | 35.14% | ★★★★★★ |
| Financial Institutions | 10.0x | 3.3x | 20.98% | ★★★★★☆ |
| Bank of the James Financial Group | 10.9x | 2.4x | 26.49% | ★★★★☆☆ |
| Union Bankshares | 9.7x | 2.1x | 45.12% | ★★★★☆☆ |
| Shore Bancshares | 11.9x | 3.4x | 35.47% | ★★★★☆☆ |
| Five Star Bancorp | 15.7x | 6.7x | 43.23% | ★★★☆☆☆ |
| German American Bancorp | 13.2x | 4.9x | 25.83% | ★★★☆☆☆ |
| Franklin Financial Services | 11.5x | 3.1x | -40.80% | ★★★☆☆☆ |
| Orion Group Holdings | 101.3x | 0.4x | 46.17% | ★★★☆☆☆ |
Below we spotlight a couple of our favorites from our exclusive screener.
Alerus Financial (ALRS)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Alerus Financial operates in the financial services sector, offering banking, wealth advisory, and retirement and benefit services with a market cap of $0.46 billion.
Operations: The company's primary revenue streams include Banking (including Mortgage), Wealth Advisory Services, and Retirement and Benefit Services. Operating expenses are primarily driven by General & Administrative costs, which reached $155.37 million in the latest period. The net income margin has shown variability over time, with a recent figure of 11.40%.
PE: 30.1x
Alerus Financial, a small-cap player in the U.S. financial sector, is catching attention with its earnings forecast set to grow 40.56% annually. Recent insider confidence is evident as they initiated a share repurchase program valid until August 2029, having already bought back 500,000 shares for US$12.56 million by June 2026. The company also declared an increased quarterly dividend of US$0.22 per share and filed a US$200 million shelf registration for potential capital raising activities on September 2, 2026.
- Unlock comprehensive insights into our analysis of Alerus Financial stock in this valuation report.
Evaluate Alerus Financial's historical performance by accessing our past performance report.
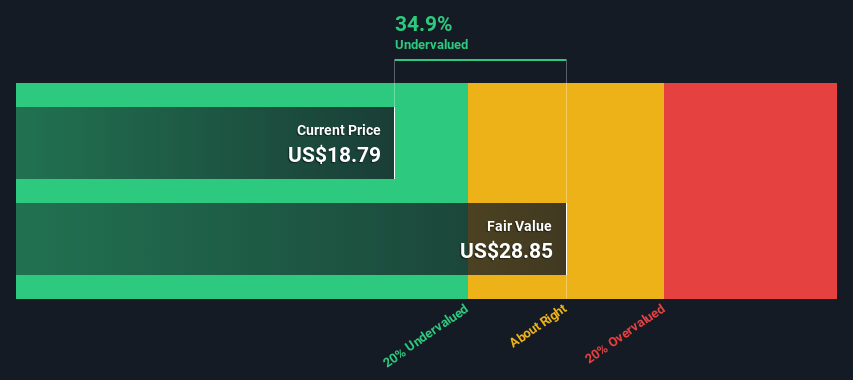
Kemper (KMPR)
Simply Wall St Value Rating: ★★★★★☆
Overview: Kemper is a company that primarily operates in the insurance sector, offering life insurance and specialty property & casualty insurance, with a market capitalization of $3.68 billion.
Operations: The primary revenue stream is derived from Specialty Property & Casualty Insurance, with additional contributions from Life Insurance and Non-Core Operations. The gross profit margin has shown variability, reaching a high of 36.63% in recent periods after experiencing lower levels, such as 16.78% in earlier quarters. Operating expenses have consistently been a significant cost component impacting profitability.
PE: -3.3x
Kemper, a smaller company in the U.S. market, is navigating challenges with recent financial results showing a net loss of US$464.8 million for Q2 2026. Despite this, earnings are projected to grow by 108% annually, suggesting potential upside. Insider confidence is evident as they increase their holdings, reflecting belief in future prospects despite current losses and goodwill impairments of US$460 million. The company's shift to the Russell 2000 Index highlights its evolving market position and potential appeal to value-focused investors.
- Click here and access our complete valuation analysis report to understand the dynamics of Kemper.
Understand Kemper's track record by examining our Past report.
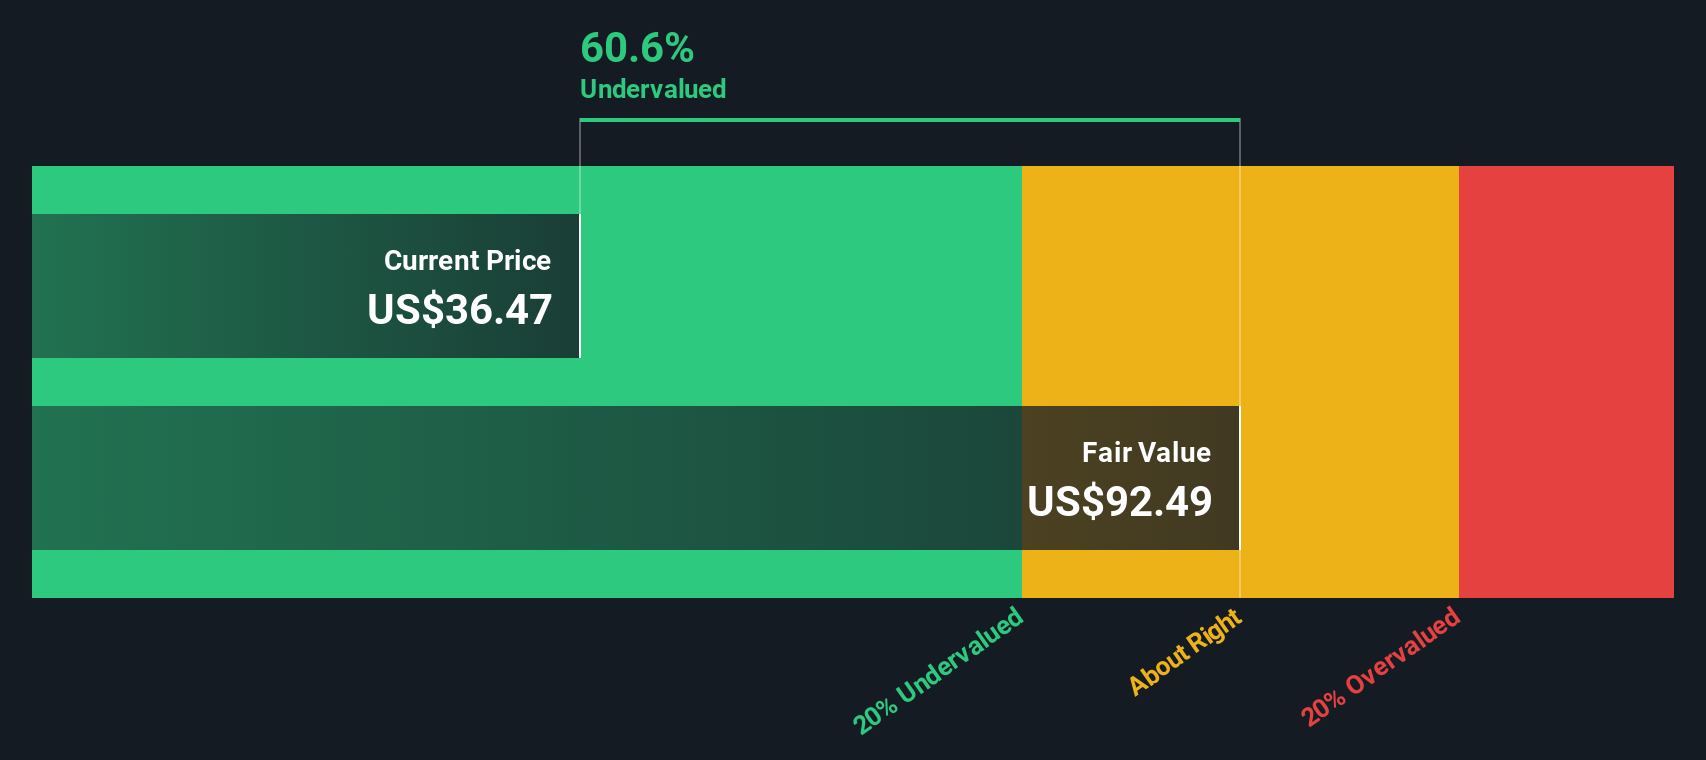
Regional Management (RM)
Simply Wall St Value Rating: ★★★★★★
Overview: Regional Management is a consumer finance company that provides personal loans primarily to customers with limited access to traditional credit, and it has a market cap of approximately $0.29 billion.
Operations: The company generates revenue primarily from consumer finance, with recent figures reaching $647.84 million. Over the years, its net income margin has fluctuated, recently standing at 7.23%. Operating expenses have consistently been a significant component of costs, with general and administrative expenses frequently exceeding $230 million in recent periods. Notably, the gross profit margin has seen variations but was last reported at 59.75%.
PE: 6.5x
Regional Management, a smaller company in the U.S., shows potential as an undervalued investment. Insider confidence is evident with President Lakhbir Lamba purchasing 10,000 shares for US$316,495 recently. Despite earnings being insufficient to cover interest payments and reliance on higher-risk funding sources, the company anticipates net income growth of 6% to 9% for 2026. Recent buybacks reduced outstanding shares by 11.72%, while dividends remain steady at US$0.30 per share for Q3 2026.
- Dive into the specifics of Regional Management here with our thorough valuation report.
Assess Regional Management's past performance with our detailed historical performance reports.

Turning Ideas Into Actions
- Unlock our comprehensive list of 59 Undervalued US Small Caps With Insider Buying by clicking here.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com